
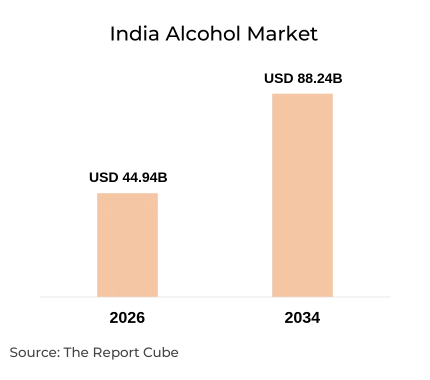
Build Your Custom Market Intelligence Report
Customize Your ReportKey Highlights
- The India Alcohol Market is estimated at USD 44.94 billion in FY2026, an analyst-derived base-year estimate.
- Market size is projected to reach USD 88.24 billion by FY2034.
- The market is forecast to grow at a CAGR of 8.80% during FY2026-FY2034, using a constant exchange rate of INR 87 per USD.
- Spirits lead the beverage-type segment, with whisky the largest spirits subcategory.
- Regional share data is not available from approved sources, so no leading region is named.
- Premiumisation and rising disposable income are the major growth drivers.
- Competition spans domestic spirits makers, multinational brewers and wine producers such as United Spirits, United Breweries, Radico Khaitan and Sula Vineyards.
Market Outlook
The India Alcohol Market covers spirits, beer, wine, ready-to-drink (RTD) beverages and country liquor. It is a state-regulated consumer market where excise policy, licensing and distribution shape how companies compete and how products reach consumers.
Spirits remain the largest category, with whisky leading, while beer and wine add breadth. Consumption is concentrated in off-trade channels, and Agriculture and Agri-Food Canada reports an 84% off-trade share of consumption in 2022. Premium, craft and RTD formats are widening the demand base among younger adult consumers.
The market is estimated at USD 44.94 billion in FY2026 and is projected to reach USD 88.24 billion by FY2034 at an 8.80% CAGR. Published valuations differ by market definition. The Ministry of Food Processing Industries (MOFPI) cites USD 39.3 billion for 2024 and USD 68.75 billion by 2034, so this forecast is a higher-growth scenario.
Domestic and multinational producers compete through premium portfolios, brand extensions and distribution reach. Opportunities lie in Indian single malts, craft spirits, premium beer and RTDs. State taxation, input costs and affordability will shape how far value growth can continue.
Government Regulations
Alcohol regulation in India sits largely with state governments, whose excise departments control licensing, duties, retail and distribution, and set legal drinking ages. The Food Safety and Standards Authority of India sets quality and labelling standards for alcoholic beverages, and import duties affect the pricing of foreign spirits. Advertising restrictions limit brand communication and push marketing toward permitted channels. Different state rules create operational complexity for nationwide distribution, so producers manage separate pricing, licensing and logistics. Alcohol also contributes significantly to state own-tax revenue, which makes excise policy a recurring source of change. The World Health Organization’s alcohol and health reporting informs public health policy discussions. Companies with strong compliance systems and state-level relationships are better placed to manage these requirements.
India Alcohol Market Dynamics
Market dynamics reflect value-led growth in which premium products, state policy and input costs matter more than volume alone. Annual value growth is expected to moderate from 9.5% in FY2027 to 8.1% in FY2034 as the market matures.
|
Factor |
Type |
Specific Impact on Market |
Magnitude |
|---|---|---|---|
|
Rising disposable income |
Driver |
Supports trading up to prestige and premium products |
High |
|
Beer and innovative beverage demand |
Driver |
Broadens categories and consumer entry points |
Medium–High |
|
Domestic craft and premium spirits |
Opportunity |
Enables differentiated Indian brands and luxury positioning |
Medium–High |
|
RTD and low-alcohol formats |
Opportunity |
Convenient formats for younger adult consumers |
Medium |
|
State excise and taxation differences |
Challenge |
Raises compliance cost and affects retail pricing |
High |
|
Input cost and affordability pressure |
Challenge |
Barley, glass, packaging and logistics costs squeeze margins |
Medium–High |
|
Premiumisation |
Trend |
Lifts average selling prices and value growth |
High |
Growth Drivers
Rising Disposable Income and Premiumisation: Higher purchasing power supports migration from economy to prestige and premium products. Value growth can outpace volume growth as consumers trade up. Radico Khaitan’s FY2025 annual report shows its Prestige & Above portfolio at 69.4% of IMFL value sales, which is company-level evidence of the shift.
Beer and Product Diversification: Beer, wine and RTDs widen the consumer base beyond traditional spirits. Agriculture and Agri-Food Canada records beer consumption rising 30.5% in 2022 over 2021 and projects RTD growth of 12.7% annually over 2023-2027, supporting category expansion.
Market Opportunities
Indian Premium Spirits and Craft Distilleries: Indian single malts, craft gin and luxury whisky let domestic producers build differentiated brands. Company disclosures show growing premium portfolios, which gives distillers room to expand pricing power and export potential.
RTD and Innovative Formats: Pre-mixed cocktails, flavoured alcoholic beverages and canned formats can attract younger adults. RTD consumption rose from 41 million litres in 2021 to 46 million litres in 2022, indicating a small but fast-growing base.
Industry Challenges
State-Level Excise and Taxation: Each state sets its own licensing, duty and distribution rules, which complicates national scale. Excise-led price changes can alter brand pricing and consumption patterns across regions and require state-specific strategies.
Input Costs and Affordability: Barley, wheat, glass, packaging and logistics costs can compress margins. Where price increases cannot be passed on, affordability limits growth in mass segments, and this may moderate volume growth over the forecast period.
Need Specific Data, Let’s Customize the Report for You
Request CustomizationMarket Trends
Premiumisation Across Categories: Prestige, premium and luxury offerings are gaining attention across spirits, beer and wine. This supports revenue growth even when volumes grow slowly, and it favours producers with strong brand equity.
Low-Alcohol and Innovative Beverages: Product innovation is creating alternatives to traditional alcoholic drinks, including low-alcohol beer, flavoured drinks and mixers. Adoption varies by state and consumer segment, so quantified penetration data is limited.
India Alcohol Market Segment Analysis
The India Alcohol Market is segmented by beverage type, price category and distribution channel. Leading-segment shares are shown only where supported by approved sources.
By Beverage Type
- Spirits
- Beer
- Wine
- RTD Beverages
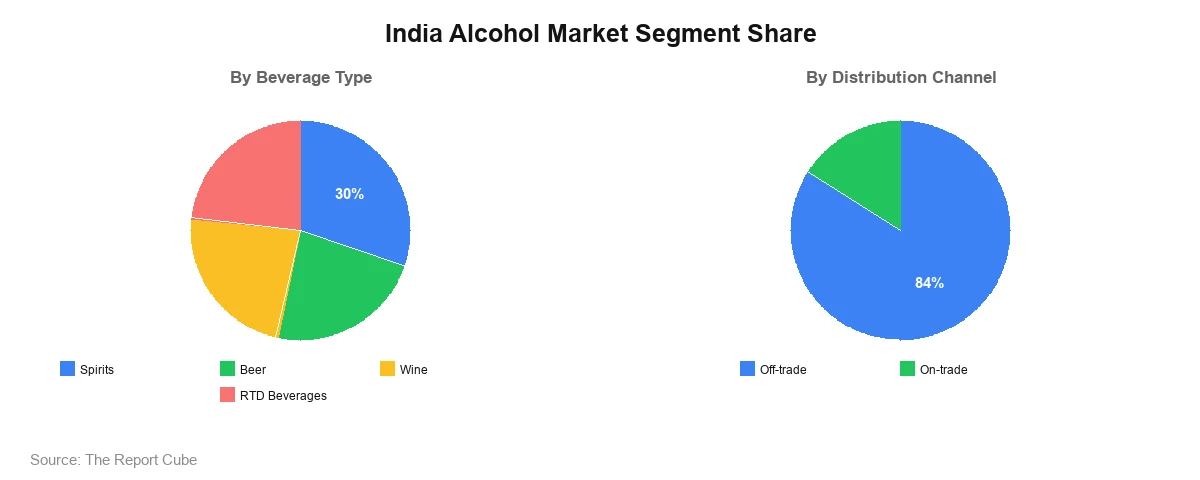
Spirits lead the beverage-type segment and are the largest category by value, with whisky the largest subcategory. They benefit from premium whisky, Indian single malts and craft gin, and from the prestige-and-above shift. Beer is the second leading segment, supported by lager, strong beer and premium and craft formats, with 30% consumption growth recorded in 2022. Wine is smaller but growing, with consumption rising from 34.5 million to 37.5 million litres in 2022. RTD beverages are the smallest and fastest-emerging category. An authoritative category-level market share is not available, so no percentage is displayed.
By Distribution Channel
- Off-trade
- On-trade
Off-trade leads, accounting for an estimated 84% of total alcoholic beverage consumption in 2022 (consumption basis, not value), according to Agriculture and Agri-Food Canada. It covers licensed retail stores and permitted outlets, where state-regulated retail dominates access. On-trade, including bars, pubs, restaurants and hotels, held about 16% and is closely tied to hospitality recovery, tourism and premium brand visibility.
India Alcohol Market Regional Analysis
India’s alcohol demand is shaped by state excise policy, consumer preferences, licensing structures and distribution systems. Verified regional market-share data is not available, so shares are not estimated.
|
Region |
Estimated Market Share |
Key Growth Factors |
Industry Trends |
|---|---|---|---|
|
North India |
- |
Delhi, Uttar Pradesh, Punjab, Haryana and Rajasthan drive spirits and premium liquor demand |
Regional distribution and premium spirits |
|
South India |
- |
Karnataka, Telangana, Andhra Pradesh, Tamil Nadu and Kerala have significant state-controlled retail |
Heavy state tax dependence on alcohol |
|
East India |
- |
West Bengal, Odisha, Bihar and Jharkhand reflect regional liquor preferences |
Differing state regulations |
|
West India |
- |
Maharashtra, Goa and Gujarat combine tourism with regional beverage production |
Premium spirits and hospitality |
|
Central India |
- |
Madhya Pradesh and Chhattisgarh |
Country liquor and IMFL distribution |
Competitive Landscape
The India Alcohol Market includes domestic spirits producers, multinational brewers and distillers, and domestic wine makers. The table lists relevant participants by capability and does not represent a ranking or market share.
|
Company |
Competitive Strength |
Primary Segment Served |
|---|---|---|
|
United Spirits Limited |
Extensive brand portfolio |
Spirits |
|
United Breweries Limited |
Established distribution and brands |
Beer |
|
Radico Khaitan Limited |
Premiumisation and Indian luxury spirits |
Spirits |
|
Pernod Ricard India |
International brands and premium positioning |
Spirits |
|
Allied Blenders and Distillers |
Large whisky portfolio |
Spirits |
|
Sula Vineyards |
Domestic wine production |
Wine |
|
Tilaknagar Industries |
Brandy expertise |
Spirits |
|
Carlsberg India |
International beer portfolio |
Beer |
|
AB InBev |
Global brands and brewing capabilities |
Beer |
|
John Distilleries |
Premium Indian single malt |
Spirits |
Radico Khaitan Limited: Radico Khaitan is an Indian spirits manufacturer with brands including 8PM, Magic Moments, Rampur and Jaisalmer. Its FY2025 annual report shows Prestige & Above at 46.1% of IMFL volumes and 69.4% of IMFL value sales, with sales in that tier up 21.1%. Its strength is its premium and luxury portfolio.
United Breweries Limited: United Breweries is a major beer manufacturer with brands including Kingfisher, Heineken and Amstel. It reported FY2025 net turnover of INR 8,907.35 crore, up 9.8% from FY2024, and highlights premium beer growth and product innovation. Its strength lies in distribution reach and a broad brewing portfolio.
Recent Developments and Updates
- December 2025: Aspri Spirits filed a draft red herring prospectus that estimates the alcoholic beverage market at INR 3.552 trillion in FY2025 and INR 5.850 trillion by FY2030. The filing is a regulatory reference point for valuation and for the growth of domestic and imported spirits.
- July 2025: Monika Alcobev’s prospectus, filed with the Securities and Exchange Board of India, estimated the market at INR 3.255 trillion in FY2024. It projected INR 5.049 trillion by FY2029 and a shift of share toward undistilled beverages.
- 2025: United Breweries reported FY2025 net turnover of INR 8,907.35 crore, up 9.8%, and Radico Khaitan reported 21.1% growth in Prestige & Above sales. Both results point to premiumisation across beer and spirits.
India Alcohol Market Future Outlook
The India Alcohol Market is expected to grow from USD 44.94 billion in FY2026 to USD 88.24 billion by FY2034, with annual growth moderating from 9.5% to 8.1%. Value growth should stay ahead of volume growth as premium spirits, craft products, beer and RTDs gain share. Undistilled beverages are expected to grow faster than distilled ones under the scenario assumptions. These are analyst projections, not official statistics.
Competition is likely to centre on premium portfolios, domestic single malts, brand extensions and distribution depth. State excise changes, input costs and affordability remain the main risks. MOFPI’s lower benchmark of USD 68.75 billion by 2034, at a 5.8% CAGR, shows the sensitivity to market definition. Companies with compliance depth and premium brand equity are best placed.
India Alcohol Market Report Coverage
This report summarises the market size, forecast, segmentation, regional framework and competitive environment of the India Alcohol Market.
|
Parameter |
Details |
|---|---|
|
Market Name |
India Alcohol Market |
|
Market Size (Base Year) |
USD 44.94 billion (FY2026) |
|
Market Size (Forecast Year) |
USD 88.24 billion (FY2034) |
|
CAGR |
8.80% (FY2026-FY2034) |
|
Base Year |
FY2026 |
|
Historical Period |
FY2021-FY2025 |
|
Forecast Period |
FY2026-FY2034 |
|
Geographic Scope |
India |
|
Segmentation |
By Beverage Type; By Price Category; By Distribution Channel |
|
Regions Covered |
North, South, East, West and Central India |
|
Key Companies |
United Spirits; United Breweries; Radico Khaitan; Pernod Ricard India; Allied Blenders and Distillers; Sula Vineyards; Tilaknagar Industries; Carlsberg India; AB InBev; John Distilleries |
|
Customization |
Available as per requirement |
Why Choose This India Alcohol Market Report?
- Presents market sizing and a FY2026-FY2034 forecast with stated assumptions.
- Segments the market by beverage type, price category and distribution channel.
- Reviews drivers, opportunities, challenges and trends affecting market participants.
- Provides regional context across five Indian regions, with unavailable shares identified.
- Profiles ten key companies by capability and primary segment.
- Highlights premiumisation, RTD and craft spirits as emerging opportunities.
- Supports strategic planning with transparent disclosure of estimate limitations.
Table of Contents
- Introduction
- Objective of the Study
- Product Definition
- Market Segmentation
- Study Variables
- Research Methodology
- Secondary Data Points
- Companies Interviewed
- Primary Data Points
- Breakdown of Primary Interviews
- Secondary Data Points
- Executive Summary
- Market Dynamics
- Drivers
- Challenges
- Opportunity Assessment
- Recent Trends and Developments
- Policy and Regulatory Landscape
- India Alcohol Market Overview and Forecast Analysis (2021-2034)
- Market Size, By Value, By Growth Rate (CAGR/USD Billions)
- Demand – Supply Trends
- Market Share, By Beverage Type
- IMFL
- IMIL / Country Liquor
- Beer
- Wine
- RTD Alcoholic Beverages
- Imported Alcoholic Beverages*
- Market Share, By Spirits Type
- Whisky
- Brandy
- Rum
- Vodka
- Gin
- Tequila and Other Spirits
- Liqueurs
- Market Share, By Beer Type
- Strong Beer
- Mild Beer
- Lager
- Craft Beer
- Other Specialty Beer
- Market Share, By Wine Type
- Red Wine
- White Wine
- Rosé Wine
- Sparkling Wine
- Fortified Wine
- Market Share, By RTD Type
- Spirit-Based RTDs
- Malt-Based RTDs
- Wine-Based RTDs
- Other Alcoholic RTDs
- Market Share, By Price Category
- Economy
- Regular / Popular
- Prestige
- Premium
- Luxury / Super-Premium
- Market Share, By Distribution Channel
- Off-Trade
- On-Trade
- Market Share, By Region
- North India
- South India
- East India
- West India
- Central India
- Northeast India
- Market Share, By Competitors
- Competition Characteristics
- Revenue Shares
- IMFL India Alcohol Market Overview, 2021-2034F
- By Value (USD Million)
- By Spirits Type – Market Size & Forecast 2021-2034, USD Million
- Whisky
- Brandy
- Rum
- Vodka
- Gin
- Tequila and Other Spirits
- Liqueurs
- IMIL / Country Liquor India Alcohol Market Overview, 2021-2034F
- By Value (USD Million)
- By Spirits Type – Market Size & Forecast 2021-2034, USD Million
- Whisky
- Brandy
- Rum
- Vodka
- Gin
- Tequila and Other Spirits
- Liqueurs
- Beer India Alcohol Market Overview, 2021-2034F
- By Value (USD Million)
- By Spirits Type – Market Size & Forecast 2021-2034, USD Million
- Whisky
- Brandy
- Rum
- Vodka
- Gin
- Tequila and Other Spirits
- Liqueurs
- Wine India Alcohol Market Overview, 2021-2034F
- By Value (USD Million)
- By Spirits Type – Market Size & Forecast 2021-2034, USD Million
- Whisky
- Brandy
- Rum
- Vodka
- Gin
- Tequila and Other Spirits
- Liqueurs
- RTD Alcoholic Beverages India Alcohol Market Overview, 2021-2034F
- By Value (USD Million)
- By Spirits Type – Market Size & Forecast 2021-2034, USD Million
- Whisky
- Brandy
- Rum
- Vodka
- Gin
- Tequila and Other Spirits
- Liqueurs
- Imported Alcoholic Beverages* India Alcohol Market Overview, 2021-2034F
- By Value (USD Million)
- By Spirits Type – Market Size & Forecast 2021-2034, USD Million
- Whisky
- Brandy
- Rum
- Vodka
- Gin
- Tequila and Other Spirits
- Liqueurs
- Competitive Outlook (Company Profile – Partial List)
- United Spirits
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- United Breweries
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Radico Khaitan Spirits
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Pernod Ricard
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- 5 Allied Blenders Spirits
- 14.5.1 Company Overview
- 14.5.2 Business Segments
- 14.5.3 Strategic Alliances/Partnerships
- 14.5.4 Recent Developments
- Sula Vineyards Wine
- 14.6.1 Company Overview
- 14.6.2 Business Segments
- 14.6.3 Strategic Alliances/Partnerships
- 14.6.4 Recent Developments
- Tilaknagar Industries
- 14.7.1 Company Overview
- 14.7.2 Business Segments
- 14.7.3 Strategic Alliances/Partnerships
- 14.7.4 Recent Developments
- Carlsberg India Beer
- 14.8.1 Company Overview
- 14.8.2 Business Segments
- 14.8.3 Strategic Alliances/Partnerships
- 14.8.4 Recent Developments
- AB InBev Beer
- 14.9.1 Company Overview
- 14.9.2 Business Segments
- 14.9.3 Strategic Alliances/Partnerships
- 14.9.4 Recent Developments
- John Distilleries
- 14.10.1 Company Overview
- 14.10.2 Business Segments
- 14.10.3 Strategic Alliances/Partnerships
- 14.10.4 Recent Developments
- United Spirits
- Contact Us & Disclaimer
Top Key Players & Market Share Outlook
- United Spirits
- United Breweries
- Radico Khaitan Spirits
- Pernod Ricard
- Allied Blenders Spirits
- Sula Vineyards Wine
- Tilaknagar Industries
- Carlsberg India Beer
- AB InBev Beer
- John Distilleries
Frequently Asked Questions