
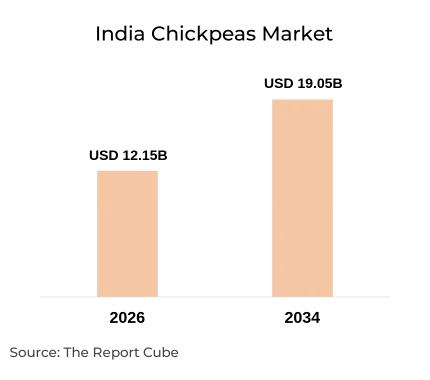
Build Your Custom Market Intelligence Report
Customize Your ReportKey Takeaways
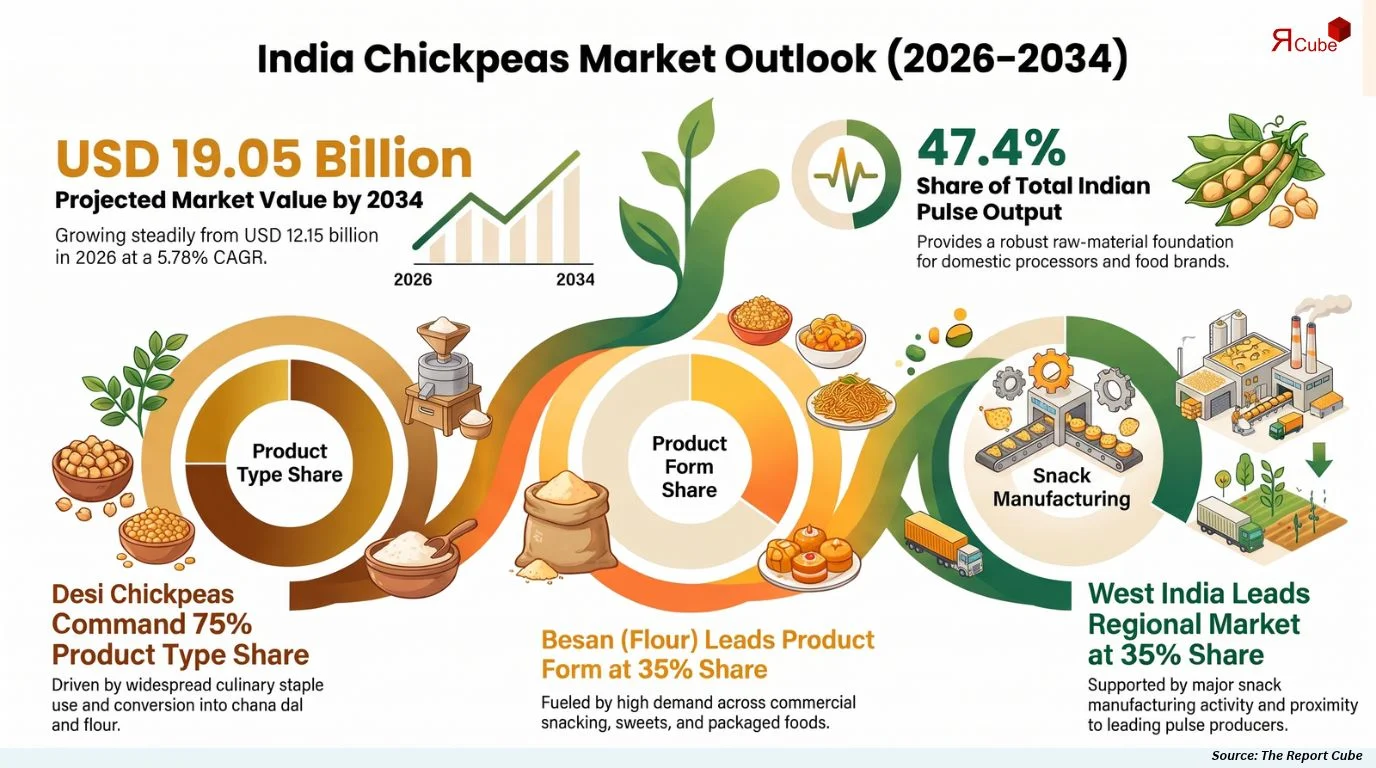
- India chickpeas market valued at USD 12.15 billion in 2026, reflecting broad domestic pulse demand.
- Industry projected to reach USD 19.05 billion by 2034 at a 5.78% CAGR.
- Desi chickpeas lead the product type segment with an estimated 75% share in 2026.
- Chickpea flour (besan) leads the product form segment with an estimated 35% share in 2026.
- West India holds the leading regional position with an estimated 35% share in 2026.
- Adani Wilmar, ITC, Tata Consumer Products, and Balaji Wafers feature among key market participants.
- Value-added processing across besan, chana dal, and snack products continues shaping market development.
Market Overview
Chickpeas, also known as chana, are pulses harvested mainly during the rabi season and consumed as whole grain, split chickpeas (chana dal), and chickpea flour (besan). Desi and Kabuli varieties serve household cooking, snack manufacturing, and food processing, while chickpeas also supply plant-based protein for emerging alternative-protein products across packaged foods.
This India Chickpeas Market Analysis shows demand shaped by domestic cooking habits, large pulse output, and processor requirements for besan and dal. NITI Aayog data indicates chickpeas made up about 47.4% of India’s pulse output across its review period, which supports raw-material availability for millers, snack makers, and packaged-food companies.
The market was valued at USD 12.15 billion in 2026 and is expected to reach USD 19.05 billion by 2034. Processed formats, commercial snacking, and export channels add further demand layers beyond direct household consumption and traditional retail. The market is projected to grow at a CAGR of 5.78% during 2026–2034.
India Chickpeas Market Dynamics
India’s chickpeas market is shaped by domestic pulse production, food-processing requirements, agricultural conditions, and trade flows. Seasonal output affects raw-material availability, while processed formats such as besan and chana dal widen demand. Qualitative assessments below reflect available evidence and do not quantify the supplied revenue forecast.
|
Factor |
Type |
Specific Impact on Market |
Magnitude |
|---|---|---|---|
|
Large domestic pulse base |
Driver |
Chickpeas accounted for about 47.4% of pulse output in NITI Aayog’s review period, supporting raw-material supply |
High (qualitative) |
|
Multiple processing applications |
Driver |
Whole, split, besan, and roasted formats broaden demand across food categories |
Medium to High (qualitative) |
|
Value-added chickpea ingredients |
Opportunity |
Besan and ingredient-grade flour can serve snack, sweet, and processed-food applications |
Medium (qualitative) |
|
Seasonal production variability |
Challenge |
Crop output changes affect raw-material availability and procurement planning |
Medium to High (qualitative) |
|
Diversification into processed formats |
Trend |
Flour, dal, and roasted products create a varied processing base |
Medium to High (qualitative) |
India Chickpeas Market Growth Drivers
India Chickpeas Market Growth is anchored in the crop’s weight within domestic pulse production. NITI Aayog reports that chickpeas accounted for approximately 47.4% of total pulse output over the five years in its analysis. This is a historical figure, but it indicates a broad raw-material base for household consumption and processing.
Established processing pathways add a second demand layer. An industry document filed with SEBI identifies whole chickpeas, split dal, besan, and roasted or puffed chickpeas as important applications. Processors can therefore serve staple retail, snack, and sweet-making channels, although the filing does not quantify current revenue by individual application or product format.
India Chickpeas Market Opportunities
Value-added chickpea ingredients present a practical opportunity. Chickpea flour is used in traditional snacks, sweets, batters, and other processed foods, according to the SEBI-filed industry document. Processors can assess besan, ingredient-grade flour, and other chickpea-based products, subject to quality specifications, customer requirements, and commercially validated demand rather than assumed volumes.
Export development offers a second avenue. APEDA publishes pulses export statistics and destination information, and reported pulse exports of approximately USD 969.53 million in FY2025–26 across all categories. Chickpea suppliers therefore need detailed product-level trade records to assess destinations, since all-pulses figures describe sector context rather than chickpea-specific export potential.
India Chickpeas Industry Challenges
Agricultural production variability affects raw-material availability and procurement planning. The Department of Agriculture and Farmers Welfare publishes advance and final production estimates for foodgrains and commercial crops, which processors can monitor seasonally. Chickpea-specific crop tables should be checked before quantifying the effect of any season on supply or input costs.
Trade and procurement conditions add uncertainty for chickpea businesses. Changes in international demand, domestic supply, and trade policy can influence sourcing and sales decisions. APEDA’s all-pulses export figure does not establish chickpea-specific exposure, so companies need detailed product-level data to judge how external conditions affect procurement margins and inventory levels.
Need Specific Data, Let’s Customize the Report for You
Request CustomizationIndia Chickpeas Market Trends
India Chickpeas Market Trends include diversification into processed formats. The SEBI-filed industry document describes flour, split dal, whole chickpeas, and roasted or puffed products as distinct uses, and discusses chickpea flour in snacks, sweets, and other foods. This indicates a varied processing base, though it does not measure current growth rates for each format.
Production geography and regional sourcing remain relevant to procurement planning. NITI Aayog identifies Madhya Pradesh, Maharashtra, and Rajasthan among India’s leading pulse-producing states, which makes proximity to major growing areas important for processors and distributors. This does not necessarily demonstrate that any sales region holds the largest overall market share.
India Chickpeas Market Segment Analysis
Chickpea demand is segmented by variety, processing form, end-use application, and distribution pathway. Each category reflects a different stage of the value chain, from farm-gate trade to packaged consumer products.
By Product Type
- Desi Chickpeas
- Kabuli Chickpeas
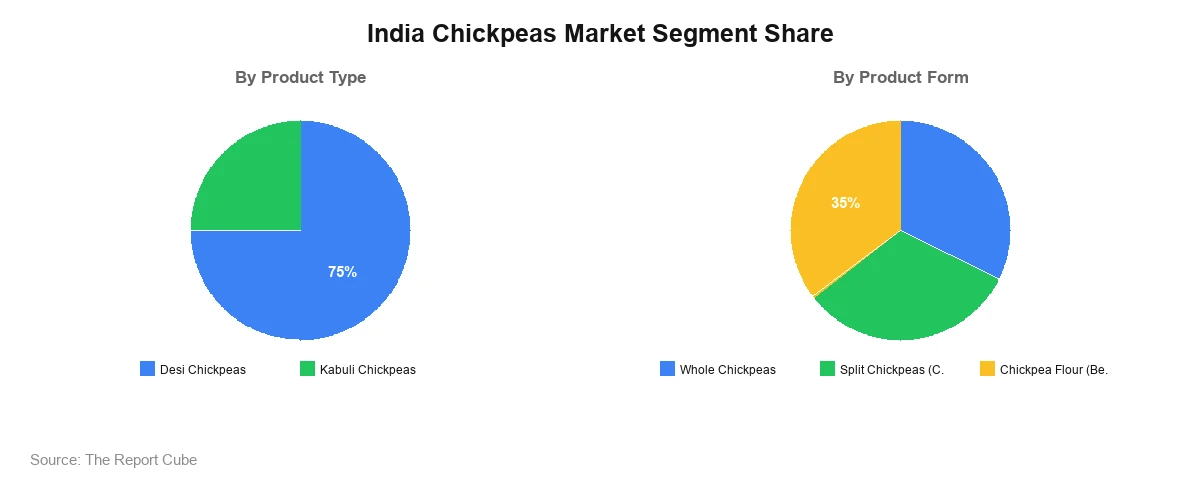
Desi chickpeas lead the product type category with an estimated 75% share in 2026, supported by their central role in everyday Indian cooking, widespread cultivation, and use in chana dal and besan. Branded food companies such as ITC, Tata Consumer Products, and AWL Agri Business participate in staple pulse and flour categories that draw on desi grades. Kabuli chickpeas follow, serving larger-grain culinary uses and export-oriented trade. This distribution of India Chickpeas Market Share reflects the weight of traditional consumption patterns, while Kabuli’s position depends more on export demand and product positioning than on domestic volume. Kabuli chana exports reportedly rose to 195,427 tonnes in FY2025–26, indicating external demand for this variety.
By Product Form
- Whole Chickpeas
- Split Chickpeas (Chana Dal)
- Chickpea Flour (Besan)
Chickpea flour (besan) leads the product form category with an estimated 35% share in 2026, driven by its use in snacks, sweets, batters, and other processed foods described in industry documentation. Balaji Wafers, whose range includes chana dal-based snacks, and branded staples companies such as ITC and Tata Consumer Products operate in flour and pulse categories. Whole chickpeas follow, serving household cooking and further processing, while split chickpeas (chana dal) support dal preparations, roasted snacks, and milling into flour. These formats remain closely linked because processors convert whole grain into dal and flour, though the supplied data does not quantify their individual shares.
Regional Analysis of India Chickpeas Market
|
Region |
Estimated Market Share |
Key Growth Factors |
Industry Trends |
|---|---|---|---|
|
North |
- |
Regional drivers require validation |
Not supplied |
|
South |
- |
Regional drivers require validation |
Not supplied |
|
East |
- |
Regional drivers require validation |
Not supplied |
|
West |
35% (2026) |
Snack and food-processing presence; Gujarat-based Balaji Wafers and AWL Agri Business; Maharashtra among leading pulse-producing states (NITI Aayog) |
Processing-led demand and proximity to producers |
West India leads regional revenue with an estimated 35% share in 2026. Processing and snack-manufacturing activity supports regional demand, with Balaji Wafers and AWL Agri Business headquartered in Gujarat, and Maharashtra identified by NITI Aayog among India’s leading pulse-producing states. Proximity to producers and processors supports sourcing efficiency, although state-level market values are not supplied.
North, South, and East India complete the regional picture; individual shares for these regions were not supplied and are not estimated here. Regional demand differences primarily depend on dietary patterns, procurement networks, mandi access, and local processing capacity. Comparative percentages for these regions therefore require validation against verified, region-level data.
Market Share & Competitive Landscape
The India chickpeas industry combines branded food companies, snack manufacturers, and regional pulse processors. Competitive positioning below reflects verified business scope and is not a ranking by market share. Company-level revenue shares were not supplied.
|
Company |
Competitive Strength |
Primary Segment Served |
|---|---|---|
|
Adani Wilmar (AWL Agri Business Limited) |
Integrated food and FMCG portfolio of kitchen staples with an extensive distribution network |
Packaged staples and flours |
|
ITC Limited |
Diversified FMCG company with a branded packaged foods and staples portfolio |
Branded pulses and chickpea flour |
|
Tata Consumer Products Limited |
Branded food and staples portfolio with national retail presence |
Branded pulses and flours |
|
Kishor Kalyanji Corp LLP |
Listed participant; company-specific capabilities not independently verified |
To be confirmed |
|
House of Rasa |
Listed participant; company-specific capabilities not independently verified |
To be confirmed |
|
IndiaFeast |
Listed participant; company-specific capabilities not independently verified |
To be confirmed |
|
Balaji Wafers Pvt. Ltd. |
Large snack manufacturer with automated factories and chana dal-based snack products |
Commercial snacking |
Key Companies in the India Chickpeas Market
Balaji Wafers Pvt. Ltd.: Balaji Wafers, founded in 1974 and headquartered in Rajkot, Gujarat, is one of India’s largest snack food brands. Its range includes chana dal and moong dal snacks produced in automated factories. In January 2026, it signed a definitive agreement for a strategic investment from General Atlantic.
AWL Agri Business Limited (Adani Wilmar): AWL Agri Business Limited, formerly Adani Wilmar, is headquartered in Ahmedabad, Gujarat, and operates in edible oils, staples, and packaged foods. In March 2026 it added Fortune Atta with Multigrains, and in May 2026 announced a collaboration with Shree Renuka Sugars, expanding its food portfolio and distribution reach.
Recent Developments
|
Year / Month |
Company |
Development |
|---|---|---|
|
January 2026 |
Balaji Wafers |
Signed a definitive agreement for a strategic investment from General Atlantic, with closing expected later in 2026 subject to approvals |
|
March 2026 |
Balaji Wafers |
Competition Commission of India cleared General Atlantic Singapore BWP Pte. Ltd.’s proposed share acquisition |
|
March 2026 |
AWL Agri Business |
Added Fortune Atta with Multigrains to its flour portfolio, available in 5-kg packs across select metro cities and quick-commerce and e-commerce platforms |
|
May 2026 |
AWL Agri Business |
Announced a strategic collaboration with Shree Renuka Sugars Limited to strengthen its food portfolio and branded sugar business |
India Chickpeas Market Future Outlook
The India Chickpeas Market Forecast indicates growth from USD 12.15 billion in 2026 to USD 19.05 billion by 2034, equivalent to a CAGR of 5.78%. Expansion is expected to depend on stable domestic pulse supply, continued demand for dal and besan, and wider use of chickpea ingredients in packaged foods. Projections remain conditional on crop conditions, trade policy, and procurement dynamics throughout the forecast period.
Processors are likely to focus on value-added formats, including besan, ingredient-grade flour, and snack inputs, while exporters assess destinations using product-level trade data. Climate-related yield variation, import and procurement conditions, and input costs represent key risks. Companies with reliable sourcing, quality control, and distribution capabilities are better positioned to respond as demand patterns evolve across household, commercial, and industrial channels.
India Chickpeas Market Report Coverage
The India Chickpeas Market Report covers the following scope and specifications.
|
Parameter |
Details |
|---|---|
|
Market Name |
India Chickpeas Market |
|
Market Size 2026 |
USD 12.15 Billion |
|
Market Size 2034 |
USD 19.05 Billion |
|
Forecast Period |
2026–2034 |
|
CAGR |
5.78% |
|
Base Year |
2026 |
|
Historical Years |
2021–2025 |
|
Forecast Years |
2026–2034 |
|
Segments Covered |
By Product Type, By Product Form, By End-Use, By Distribution |
|
Regions Covered |
North, South, East, West |
|
Key Companies |
Adani Wilmar Limited, ITC Limited, Tata Consumer Products Limited, Kishor Kalyanji Corp LLP, House of Rasa, IndiaFeast, Balaji Wafers Pvt. Ltd. |
|
Customization |
Available as per client requirements |
Why Choose This India Chickpeas Market Report?
- Market scope covering chickpea varieties, product forms, end-use applications, and distribution channels.
- Market sizing from 2026 to 2034 with a clearly stated CAGR.
- Segmentation across product type, product form, end-use, and distribution pathways.
- Regional analysis highlighting West India’s estimated share and regional demand factors.
- Competitive profiling of food companies, snack manufacturers, and chickpea processors.
- Analysis of production, trade, and processing trends supported by named public sources.
- Forecast insights that support planning, with assumptions and limitations stated clearly.
Table of Contents
- Introduction
- Objective of the Study
- Product Definition
- Market Segmentation
- Study Variables
- Research Methodology
- Secondary Data Points
- Companies Interviewed
- Primary Data Points
- Breakdown of Primary Interviews
- Secondary Data Points
- Executive Summary
- Market Dynamics
- Drivers
- Challenges
- Opportunity Assessment
- Recent Trends and Developments
- Policy and Regulatory Landscape
- India Chickpeas Market Overview and Forecast Analysis (2021-2034)
- Market Size, By Value, By Growth Rate (CAGR/USD Billions)
- Demand – Supply Trends
- Market Share, By Product Type
- Desi Chickpeas
- Kabuli Chickpeas
- Market Share, By Product Form
- Whole Chickpeas
- Split Chickpeas (Chana Dal)
- Chickpea Flour (Besan)
- Market Share, By End-Use
- Direct Culinary Consumption
- Commercial Snacking
- Food Processing & Alternative Proteins
- Market Share, By Distribution
- Rural vs. Urban Channels
- Domestic Mandis vs. Export
- Market Share, By Region
- North
- South
- East
- West
- Market Share, By Competitors
- Competition Characteristics
- Revenue Shares
- Desi Chickpeas India Chickpeas Market Overview, 2021-2034F
- By Value (USD Million)
- By Product Form – Market Size & Forecast 2021-2034, USD Million
- Whole Chickpeas
- Split Chickpeas (Chana Dal)
- Chickpea Flour (Besan)
- Kabuli Chickpeas India Chickpeas Market Overview, 2021-2034F
- By Value (USD Million)
- By Product Form – Market Size & Forecast 2021-2034, USD Million
- Whole Chickpeas
- Split Chickpeas (Chana Dal)
- Chickpea Flour (Besan)
- Competitive Outlook (Company Profile – Partial List)
- Adani Wilmar Limited
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- ITC Limited
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Tata Consumer Products Limited
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Kishor Kalyanji Corp LLP
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- House of Rasa
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- IndiaFeast
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Balaji Wafers Pvt. Ltd.
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Adani Wilmar Limited
- Contact Us & Disclaimer
Top Key Players & Market Share Outlook
- Adani Wilmar Limited
- ITC Limited
- Tata Consumer Products Limited
- Kishor Kalyanji Corp LLP
- House of Rasa
- IndiaFeast
- Balaji Wafers Pvt. Ltd.
Frequently Asked Questions