
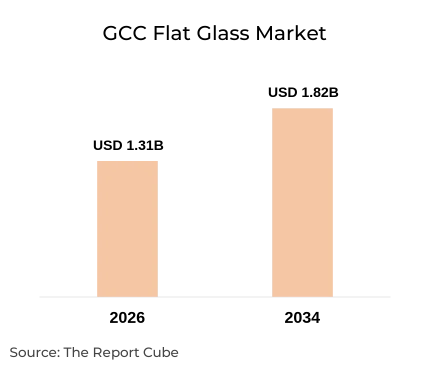
Build Your Custom Market Intelligence Report
Customize Your ReportKey Highlights
- The GCC Flat Glass Market was valued at USD 1.3182 billion in 2026.
- Market size is projected to reach USD 1.8235 billion by 2034.
- The market is forecast to expand at a CAGR of 4.14% during 2026–2034.
- Saudi Arabia led regional demand with a 60% share in 2026, supported by large construction pipelines and domestic manufacturing investment.
- Construction and infrastructure expansion, together with demand for energy-efficient glazing, is the major growth driver.
- Gulf Guard’s second float glass line and coater project in Jubail is a significant development in regional manufacturing capacity.
Market Outlook
Flat glass is a core industrial material produced by melting silica sand, soda ash, limestone and dolomite into uniform sheets. In the GCC it is used in windows, façades, partitions, vehicle glazing, solar modules, furniture and electronics. The market covers float, annealed, coated, tempered, laminated and insulated products across Saudi Arabia, the UAE, Qatar, Kuwait, Oman and Bahrain.
Demand follows construction activity, urbanisation and industrial diversification. Building and construction is the dominant application, with automotive, solar and other industrial uses contributing smaller volumes. Saudi Arabia and the UAE act as the main demand and processing centres. Hot-climate requirements are shifting buyers toward coated, reflective and insulated glazing that reduces solar heat gain and cooling loads.
The GCC Flat Glass Market is valued at USD 1.3182 billion in 2026 and is projected to reach USD 1.8235 billion by 2034, a CAGR of 4.14%. Growth is expected from infrastructure investment, rising adoption of value-added glazing, renewable energy projects and expanding regional production capacity, partly offset by energy-intensive manufacturing costs.
The competitive environment includes regional manufacturers, international producers, processors and distributors. Opportunities lie in processed glass, energy-efficient architectural glazing and solar glass. Producers that combine local capacity, coating and processing technology and project-supply capability are expected to strengthen their position over the forecast period.
Government Regulations
Building-efficiency regulation is the main policy influence on GCC flat glass demand. In Dubai, Al Sa’fat replaced the Dubai Green Building Regulations and Specifications from 19 October 2020, with mandatory requirements for all new buildings to obtain the Silver Sa’fa. Dubai Municipality reports that the Silver Sa’fa level delivers 19% energy savings, with Gold at 32% and Platinum at 35%, and the 2023 update aligned the system with the Dubai Building Code. The code includes building-envelope performance standards, glazing and U-value requirements, which favour coated and insulated glass. Saudi Arabia and other GCC states apply their own building and energy-conservation codes and industrial licensing frameworks. Manufacturers must therefore document thermal performance, safety classification and product compliance to qualify for large projects.
GCC Flat Glass Market Dynamics
Demand is shaped by construction investment, building-envelope efficiency requirements, manufacturing capacity and renewable energy deployment. Conventional float glass remains the volume base, while processed and coated products are gaining importance. Energy-intensive furnace operations, raw-material costs and import competition continue to influence profitability and the pace of capacity expansion.
|
Factor |
Type |
Specific Impact on Market |
Magnitude |
|---|---|---|---|
|
Construction and infrastructure pipeline |
Driver |
Sustains demand for architectural glazing in façades, windows and partitions |
High |
|
Energy-efficient building requirements |
Driver |
Raises adoption of coated, low-emissivity and insulated glass |
Medium–High |
|
Solar glass and renewable energy investment |
Opportunity |
Creates a specialised demand channel, rising from 3.5% to 6.5% of applications by 2034 |
Medium |
|
Energy-intensive manufacturing costs |
Challenge |
Fuel and raw-material price movements affect margins |
Medium–High |
|
Import competition |
Challenge |
Pressure on pricing in standard float glass categories |
Medium |
|
Shift to processed and specialty glass |
Trend |
Moves the product mix toward higher-value glazing |
Medium–High |
Growth Drivers: Expansion of Construction and Infrastructure Projects
Residential, commercial, hospitality and infrastructure development across the GCC is the principal source of flat glass demand. Glass is used in windows, curtain walls, façades, partitions and interiors, so project pipelines translate directly into orders for float and processed products. Saudi Arabia’s urban development programmes and the UAE’s commercial and residential construction are the most important generators of demand. Large projects also favour suppliers able to deliver consistent quality, processing services and reliable lead times.
Market Opportunities: Growth in Solar Glass and High-Performance Glazing
Solar photovoltaic installations are creating demand for glass with high light transmission, durability and anti-reflective surfaces. Solar glass is projected to rise from a 3.5% application share in 2026 to 6.5% by 2034. In parallel, commercial buildings, hotels and premium residential projects increasingly specify coated, laminated and insulated glazing. Manufacturers investing in coating, tempering and lamination capability can move toward higher-value segments and reduce exposure to commodity pricing.
Industry Challenges: Energy-Intensive Manufacturing and Import Competition
Flat glass production depends on continuous high-temperature furnace operation, so fuel, electricity and raw-material costs form a large part of total production cost. Price swings can compress margins, and furnace efficiency, waste control and process technology become competitive factors. Producers also face imports of standard float and processed glass from international suppliers. In basic categories, competition centres on price, availability and freight, which encourages regional producers to differentiate through quality, service and value-added products.
Need Specific Data, Let’s Customize the Report for You
Request CustomizationMarket Trends: Expansion of Regional Capacity and Processed Glass
Regional producers are adding float and coating capacity while the product mix shifts toward tempered, laminated, coated and insulated glass. Gulf Guard plans a second float glass line and a second glass coater at its Jubail Industrial City site, which is expected to strengthen local supply of higher-specification products. Processed glass is expected to grow faster than the overall market, with a 7.95% CAGR during 2026–2034, reflecting demand for safety, insulation and acoustic performance in modern building envelopes.
GCC Flat Glass Market Segment Analysis
The GCC Flat Glass Market is segmented by product type, application, technology, processing type, raw material, end user and country. Each category below lists all supplied segments, followed by an analysis of the two most commercially relevant segments.
By Product Type
- Annealed Glass
- Coated Glass
- Processed Glass
- Mirror Glass
- Patterned Glass
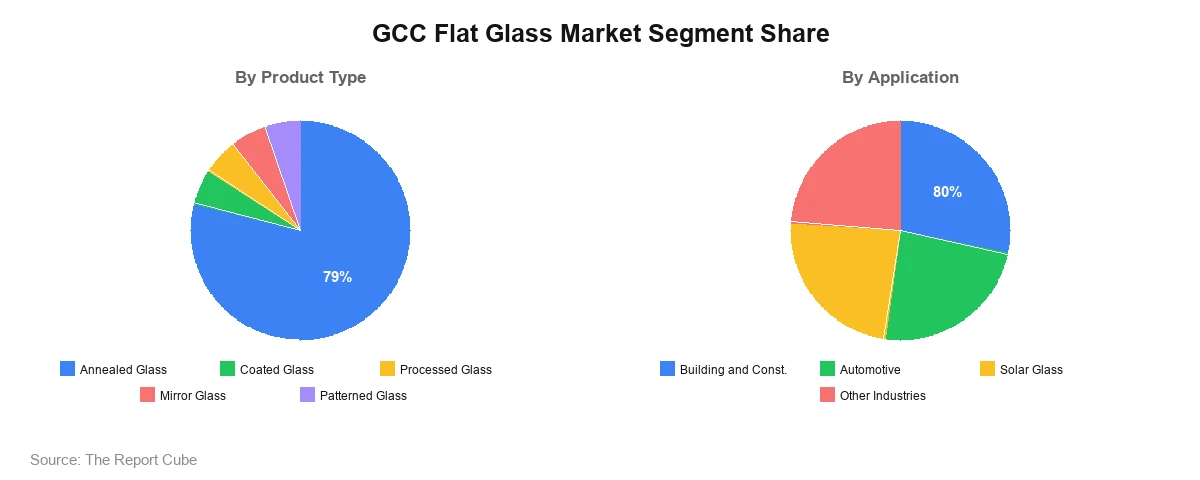
Annealed glass leads the product category with a 79% share in 2026. It is the base material for construction, furniture and industrial use and the feedstock for tempering, lamination and coating, which sustains its volume position. Processed glass is the second segment analysed. It covers tempered, laminated and insulated products used where safety, strength, thermal insulation and acoustic control are required, and it is expected to be the fastest-growing category as building envelopes become more sophisticated. Coated, mirror and patterned glass serve solar-control, interior and decorative applications.
By Application
- Building and Construction
- Automotive
- Solar Glass
- Other Industries
Building and construction leads the application category with an 80% share in 2026, driven by residential, commercial and infrastructure development, where glass is used in windows, doors, façades, curtain walls and partitions. Automotive is the second segment analysed. It covers windshields, side and rear windows and sunroofs, and depends on vehicle assembly, ownership and replacement demand, along with safety and visibility requirements. Solar glass is an emerging use tied to photovoltaic installations, and other industries include furniture, electronics and appliances.
GCC Flat Glass Market Regional Analysis
The GCC Flat Glass Market varies across its six member countries according to construction activity, industrial development, manufacturing capability and infrastructure investment. Saudi Arabia and the UAE form the largest demand and supply centres, while Qatar, Oman, Kuwait and Bahrain add demand through construction, diversification and commercial development. Cross-border trade also supports regional supply.
|
Region |
Estimated Market Share |
Key Growth Factors |
Industry Trends |
|---|---|---|---|
|
Saudi Arabia |
60% |
Large construction pipeline, urban development, domestic manufacturing |
Capacity expansion in float and coated glass |
|
UAE |
- |
Commercial and residential development, glass processing ecosystem |
Demand for coated, laminated and insulated glazing |
|
Qatar |
- |
Commercial construction, infrastructure modernisation |
Interest in energy-efficient glazing |
|
Oman |
- |
Residential and industrial development |
Rising demand for processed glass |
|
Kuwait |
- |
Residential and commercial construction, renovation |
Gradual adoption of high-performance glazing |
|
Bahrain |
3.0% |
Residential, hospitality and commercial properties |
Reliance on imported and processed glass |
Saudi Arabia’s market is supported by large-scale construction, residential expansion, tourism and commercial projects, and by domestic production investment that is strengthening its role as a regional supply centre. Demand favours architectural float glass and, increasingly, processed and coated products for façades and energy-efficient buildings.
The UAE is a major market for architectural and processed glass. Hotels, offices, retail and residential projects drive demand for coated, tempered, laminated and insulated products. Dubai’s green building framework supports glazing specifications that improve building thermal performance.
Qatar’s demand reflects commercial construction, residential development and public infrastructure. Offices, hotels and retail properties require architectural glazing, and energy-efficient building materials offer additional room for market participants.
Oman’s market is supported by residential development, industrial diversification and infrastructure programmes. Demand for architectural and processed glass is expected to rise as urban and industrial projects expand.
Kuwait’s demand is shaped by residential construction, commercial buildings and renovation work. Glass is used in windows, façades and partitions, and demand for performance glazing may grow as energy-efficiency requirements develop.
Bahrain is the smallest market in the GCC. Residential, commercial, hospitality and industrial projects support demand, and the market relies on regional trade and imported glass and processed glazing.
Competitive Landscape
The GCC Flat Glass Market includes regional float glass producers, international manufacturers, architectural processors and distributors. Competition rests on manufacturing capacity, product quality, processing capability, pricing, supply-chain efficiency and the ability to serve large construction projects. The table summarises companies by general capability and does not represent numerical market share.
|
Company |
Competitive Strength |
Primary Segment Served |
|---|---|---|
|
Guardian Glass |
Float, coated and architectural glazing; Saudi production through GulfGuard |
Building and construction; automotive |
|
AGC Obeikan Glass |
Saudi architectural and value-added glass manufacturing and processing |
Building and construction |
|
Emirates Glass |
UAE manufacturer and processor of coated and processed architectural glass |
Building and construction |
|
Saudi American Glass |
Saudi architectural glass processing |
Building and construction |
|
Saint-Gobain |
Global glazing and construction solutions portfolio |
Building and construction |
|
National Company for Glass Industries (Zoujaj) |
Saudi-listed glass industry participant with interests in regional glass manufacturers |
Float glass; building and construction |
Guardian Glass: Guardian Glass is an international glass manufacturer whose portfolio covers float glass, coated glass and advanced architectural glazing. In Saudi Arabia it operates through GulfGuard, a joint venture with Zoujaj at Jubail Industrial City. Trade press describes GulfGuard’s Jubail plant as the first float glass production of its kind in the Kingdom. Its competitive position rests on manufacturing expertise, coating technology and relationships with architectural customers, and its planned second float and coater lines would add local capacity.
National Company for Glass Industries (Zoujaj): Zoujaj is listed on the Saudi Exchange and holds interests in regional glass manufacturers. It owns 55% of Saudi Guardian International Float Glass Company (Gulf Guard), giving it exposure to float glass manufacturing in Jubail. Its Saudi Exchange disclosures document the Gulf Guard 2 expansion, and its competitive position rests on domestic manufacturing investment and partnership with an international producer.
Recent Developments and Updates
- December 2025: Zoujaj announced that Gulf Guard approved a new glass manufacturing project in Jubail Industrial City at an estimated cost of USD 267 million, comprising a float glass line and a coater glass line. The project follows a planned capacity of 750 tonnes per day and is relevant to domestic supply of float and coated glass.
- December 2025: The sputter glass coater is expected to begin operations in 2027, followed by the float glass line in 2028, according to Guardian Glass. The phasing indicates when additional coated and float capacity may reach the Saudi market, subject to execution and commissioning.
GCC Flat Glass Market Future Outlook
The GCC Flat Glass Market is expected to grow steadily from USD 1.3182 billion in 2026 to USD 1.8235 billion by 2034. Building and construction will remain the dominant application, while processed, coated and insulated glass gain importance as developers prioritise safety, thermal performance and architectural design. Solar glass offers a longer-term opportunity as renewable energy capacity expands, with its application share projected to rise from 3.5% to 6.5%.
Saudi Arabia is expected to remain the largest country market, with the UAE continuing as a processing and distribution hub. Competition will be shaped by capacity additions, energy and raw-material costs, import pressure and project execution. Producers with efficient furnaces, coating and processing capability and strong contractor relationships are best positioned, though growth will depend on construction delivery and regional economic conditions.
GCC Flat Glass Market Report Coverage
This GCC Flat Glass Market report covers market size, forecast, segmentation, country analysis and competitive positioning for 2026–2034.
|
Parameter |
Details |
|---|---|
|
Market Name |
GCC Flat Glass Market |
|
Market Size (Base Year) |
USD 1.3182 billion |
|
Market Size (Forecast Year) |
USD 1.8235 billion |
|
CAGR |
4.14% |
|
Base Year |
2026 |
|
Historical Period |
2021–2025 |
|
Forecast Period |
2026–2034 |
|
Geographic Scope |
GCC |
|
Segmentation |
Product Type; Application; Technology; Processing Type; Raw Material; End User |
|
Regions Covered |
Saudi Arabia, UAE, Qatar, Oman, Kuwait, Bahrain |
|
Key Companies |
Guardian Glass; AGC Obeikan Glass; Emirates Glass; Saudi American Glass; Saint-Gobain; National Company for Glass Industries (Zoujaj) |
|
Customization |
Available as per requirement |
Why Choose This GCC Flat Glass Market Report?
- Presents market sizing and a 2026–2034 forecast with the 4.14% CAGR.
- Segments the market by product type, application, technology, processing type, raw material, end user and country.
- Reviews drivers, opportunities, challenges and trends affecting GCC flat glass demand.
- Provides a country-level assessment across Saudi Arabia, the UAE, Qatar, Oman, Kuwait and Bahrain.
- Profiles key manufacturers and processors by capability and segment served.
- Highlights emerging opportunities in processed, coated and solar glass.
- Supports capacity, investment and product-positioning decisions for manufacturers, processors and suppliers.
Table of Contents
- Introduction
- Objective of the Study
- Product Definition
- Market Segmentation
- Study Variables
- Research Methodology
- Secondary Data Points
- Companies Interviewed
- Primary Data Points
- Breakdown of Primary Interviews
- Secondary Data Points
- Executive Summary
- Market Dynamics
- Drivers
- Challenges
- Opportunity Assessment
- Recent Trends and Developments
- Policy and Regulatory Landscape
- GCC Flat Glass Market Overview and Forecast Analysis (2021-2034)
- Market Size, By Value, By Growth Rate (CAGR/USD Billions)
- Demand – Supply Trends
- Market Share, By Product Type
- Annealed Glass
- Coated Glass
- Processed Glass
- Mirror Glass
- Patterned Glass
- Market Share, By Technology
- Float Glass
- Sheet Glass
- Rolled Glass
- Market Share, By Processing Type
- Non-Fabricated Glass
- Cut and Edged Glass
- Tempered Glass
- Laminated Glass
- Coated Glass
- Insulated Glass Units (IGUs)
- Market Share, By Application
- Building and Construction
- Residential
- Commercial
- Industrial
- Others
- Automotive
- Windshields
- Side Windows
- Rear Windows
- Sunroofs
- Solar Energy
- Solar Photovoltaic Glass
- Solar Thermal Glass
- Other Industries
- Building and Construction
- Market Share, By Raw Material
- Silica Sand
- Soda Ash
- Recycled Glass (Cullet)
- Dolomite
- Limestone
- Other Raw Materials
- Market Share, By End User
- Construction Companies
- Automotive Manufacturers
- Solar Energy Companies
- Industrial Manufacturers
- Furniture Manufacturers
- Glass Processors and Fabricators
- Other Commercial Users
- Market Share, By Country
- Saudi Arabia
- United Arab Emirates (UAE)
- Qatar
- Oman
- Kuwait
- Bahrain
- Market Share, By Competitors
- Competition Characteristics
- Revenue Shares
- Annealed Glass GCC Flat Glass Market Overview, 2021-2034F
- By Value (USD Million)
- By Technology – Market Size & Forecast 2021-2034, USD Million
- Float Glass
- Sheet Glass
- Rolled Glass
- Coated Glass GCC Flat Glass Market Overview, 2021-2034F
- By Value (USD Million)
- By Technology – Market Size & Forecast 2021-2034, USD Million
- Float Glass
- Sheet Glass
- Rolled Glass
- Processed Glass GCC Flat Glass Market Overview, 2021-2034F
- By Value (USD Million)
- By Technology – Market Size & Forecast 2021-2034, USD Million
- Float Glass
- Sheet Glass
- Rolled Glass
- Mirror Glass GCC Flat Glass Market Overview, 2021-2034F
- By Value (USD Million)
- By Technology – Market Size & Forecast 2021-2034, USD Million
- Float Glass
- Sheet Glass
- Rolled Glass
- Patterned Glass GCC Flat Glass Market Overview, 2021-2034F
- By Value (USD Million)
- By Technology – Market Size & Forecast 2021-2034, USD Million
- Float Glass
- Sheet Glass
- Rolled Glass
- Competitive Outlook (Company Profile – Partial List)
- Guardian Glass
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- AGC Obeikan Glass
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Emirates Glass
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Saudi American Glass
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Saint-Gobain
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- National Company for Glass Industries (Zoujaj)
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Guardian RAK
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Gulf Guard
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Guardian Glass
- Contact Us & Disclaimer
Top Key Players & Market Share Outlook
- Guardian Glass
- AGC Obeikan Glass
- Emirates Glass
- Saudi American Glass
- Saint-Gobain
- National Company for Glass Industries (Zoujaj)
- Guardian RAK
- Gulf Guard
Frequently Asked Questions