
Build Your Custom Market Intelligence Report
Customize Your ReportKey Takeaways
- Philippines Food Delivery Platform Market valued at USD 2.09 billion in 2026, reflecting accelerating digital adoption.
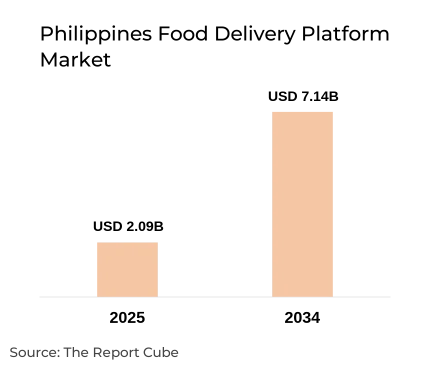
- Market projected to reach USD 7.14 billion by 2034, expanding at a 16.60% CAGR through the forecast period.
- A comprehensive Philippines Food Delivery Platform Market Analysis reveals mobile applications as the dominant platform interface segment.
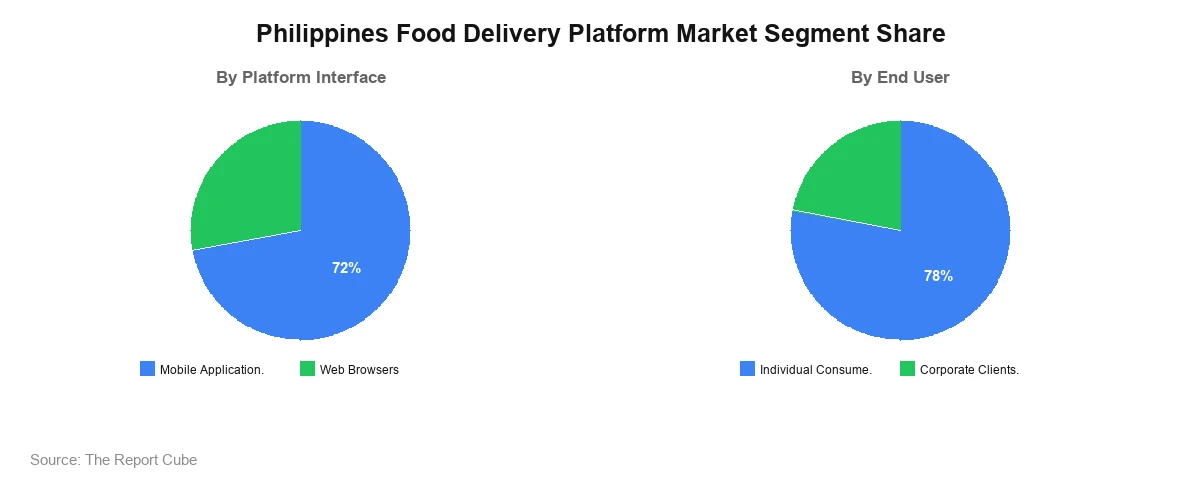
- Mobile applications lead the platform interface segment, commanding approximately 72% of total market share in 2026.
- Individual consumers represent the largest end-user segment, accounting for an estimated 78% of platform-driven order volumes.
- Corporate clients emerge as the fastest-growing end-user segment, driven by rising enterprise meal benefit adoption.
- GrabFood Philippines, Foodpanda Philippines, and ShopeeFood Philippines lead platform operator activity across the archipelago.
- Super-app integration, real-time delivery tracking, and subscription loyalty programs are reshaping food delivery platform engagement nationwide.
Market Overview
The Philippines Food Delivery Platform Market is anticipated to register a 16.60% CAGR during 2026–2034. The market was valued at USD 2.09 billion in 2026 and is projected to reach USD 7.14 billion by 2034. Rapid smartphone penetration, expanding 4G and 5G connectivity across major urban centers, and post-pandemic normalization of app-based food ordering are collectively driving platform adoption. Government digitalization programs under the Philippine Digital Economy Roadmap are facilitating e-commerce infrastructure investment, enabling faster logistics network expansion for GrabFood Philippines, Foodpanda Philippines, and ShopeeFood Philippines across Metro Manila and secondary cities.
Rising urban consumer demand for convenience-led dining, growing participation of restaurant partners in commission-based delivery ecosystems, and increasing corporate adoption of employee meal subsidy platforms are reshaping procurement behavior across the Philippines. Jollibee Foods Corporation (JFC) has deepened its digital channel integration, supplementing traditional quick-service operations with proprietary app-based ordering that competes alongside third-party platform listings. Sustainable packaging mandates, contactless payment infrastructure expansion, and hyperlocal delivery model development are further elevating quality standards across the Philippines Food Delivery Platform Market's competitive landscape.
Market Size & Forecast
|
Metric |
Details |
|---|---|
|
Market Size (2026) |
USD 2.09 Billion |
|
Market Size (2034) |
USD 7.14 Billion |
|
CAGR (2026–2034) |
16.60% |
|
Base Year |
2026 |
|
Historical Years |
2021–2025 |
|
Forecast Years |
2026–2034 |
The Philippines Food Delivery Platform Market Size study values the industry at USD 2.09 billion in 2026, with projections reaching USD 7.14 billion by 2034 at a 16.60% CAGR. This trajectory significantly outpaces Southeast Asia's regional average of approximately 9.8%, underpinned by accelerating mobile internet penetration, expanding delivery fleet infrastructure, and the surge in corporate meal benefit programs driving recurring platform transaction volumes through the forecast period.
Market Dynamics
The Philippines food delivery platform sector is evolving rapidly as smartphone adoption deepens, restaurant digitalization accelerates, and consumer expectations for real-time delivery visibility rise across urban and peri-urban geographies. The Philippines Food Delivery Platform Market Growth is primarily driven by super-app ecosystem expansion, government digital economy investment, and growing millennial and Gen Z spending on platform-mediated food services across Metro Manila and provincial cities.
|
Factor |
Type |
Specific Impact on Market |
Magnitude |
|---|---|---|---|
|
Smartphone and mobile internet expansion |
Driver |
Broadens addressable user base for app-based food ordering platforms |
High |
|
Super-app ecosystem development |
Driver |
Increases platform stickiness through integrated payments, loyalty, and logistics |
High |
|
Rider fleet retention and cost management |
Challenge |
Constrains delivery capacity expansion and raises operational cost structures |
Medium |
|
Corporate meal benefit program adoption |
Opportunity |
Opens high-volume recurring revenue streams via enterprise platform subscriptions |
High |
|
Sustainable packaging regulatory mandates |
Trend |
Drives operational compliance investment and reshapes restaurant packaging procurement |
Medium |
- Growth Drivers - Smartphone Penetration and Super-App Ecosystem Expansion: The Philippines recorded over 86 million mobile internet users in 2024, with smartphone penetration exceeding 75% of the adult population. GrabFood Philippines and ShopeeFood Philippines leverage their broader super-app ecosystems - encompassing ride-hailing, payments, and e-commerce - to drive food delivery order frequency and user retention across the archipelago.
- Market Opportunities - Corporate Client and Enterprise Meal Platform Growth: Enterprise adoption of digital meal allowance platforms represents an underpenetrated revenue segment within the Philippines Food Delivery Platform Market. Corporate clients increasingly integrate third-party food delivery platforms into employee benefit programs, creating recurring high-average-order-value transaction streams that reduce platform reliance on promotional discounting to sustain order volumes.
- Industry Challenges - Platform Commission Disputes and Restaurant Partner Retention: Sustained tension between platform operators and restaurant partners over commission rate structures - which typically range from 20% to 30% per order - risks increasing direct-ordering channel investment by larger restaurant chains. Jollibee Foods Corporation (JFC) has expanded its proprietary Jollibee Delivery app as a direct-to-consumer alternative, reflecting broader industry pressure to reduce dependency on third-party marketplace platforms.
Need Specific Data, Let’s Customize the Report for You
Request CustomizationMarket Trends
- Emerging Trends: Among the most significant Philippines Food Delivery Platform Market Trends is the rapid convergence of food delivery with broader digital commerce ecosystems. ShopeeFood Philippines exemplifies this integration, embedding food ordering within Shopee's established e-commerce super-app to capture existing high-frequency buyer bases and accelerate new user acquisition across Luzon and Visayas.
- Technology Trends: Artificial intelligence-driven route optimization, predictive demand forecasting, and real-time kitchen dispatch management tools are being deployed by GrabFood Philippines and Foodpanda Philippines to reduce average delivery time below 30 minutes. Drone delivery pilots and autonomous last-mile vehicle feasibility studies are emerging as longer-horizon technology investment priorities for platform operators targeting Metro Manila's congested urban corridors.
- Consumer / Buyer Trends: Individual consumers across the Philippines increasingly prioritize platform subscription bundles - offering free delivery and exclusive restaurant discounts - over one-time order promotions. Over 60% of repeat platform users report subscription plan participation as a primary retention driver, compelling GrabFood Unlimited, Foodpanda Pro, and ShopeeFood's loyalty programs to compete aggressively on bundle value and restaurant partner exclusivity arrangements.
Philippines Food Delivery Platform Market Segment Analysis
The Philippines Food Delivery Platform Market serves distinct end-user categories and platform interface preferences, each shaped by device adoption patterns, corporate procurement behavior, and varying restaurant partnership structures across urban and provincial delivery zones.
By Platform Interface
- Mobile Applications
- Web Browsers
Mobile applications dominate the By Platform Interface segment, commanding an estimated 72% Philippines Food Delivery Platform Market Share in 2026. GrabFood Philippines, ShopeeFood Philippines, and Foodpanda Philippines operate predominantly through iOS and Android native applications, leveraging push notification systems, in-app loyalty reward tracking, and integrated digital wallet payments to maximize order frequency. Web browser-based ordering, accounting for approximately 28%, serves corporate procurement managers and enterprise meal coordinators placing bulk or scheduled orders through desktop interfaces, representing a structurally distinct but complementary demand channel for platform operators.
By End User
- Individual Consumers
- Corporate Clients
Individual consumers represent the dominant end-user segment at an estimated 78% market share in 2026. GrabFood Philippines and Foodpanda Philippines serve the largest concentrations of individual consumer users, supported by tiered subscription plans and geo-targeted promotional campaigns across Metro Manila. Corporate clients, accounting for approximately 22% of platform-driven revenues in 2026, are the fastest-growing end-user segment as Jollibee Foods Corporation (JFC) and third-party platform operators expand enterprise meal subsidy integrations with large employers, business process outsourcing firms, and multinational corporate accounts headquartered across Metro Manila's central business districts.
Regional Analysis
|
Region |
Estimated Market Share |
Key Growth Factors |
Consumer Trends |
|---|---|---|---|
|
Metro Manila |
52% |
Highest restaurant density, corporate BPO cluster concentration, 5G network availability |
Premium platform subscription adoption, corporate meal ordering, multicuisine demand |
|
Northern Luzon |
14% |
Expanding provincial city connectivity, growing urban middle-class consumer base |
Value-tier platform usage, local restaurant discovery behavior |
|
Central Luzon |
20% |
Industrial corridor expansion, suburban residential growth, rising digital payment adoption |
Family bundle ordering, mid-market platform engagement, local chain integration |
|
Southern Luzon |
14% |
Tourism-driven HoReCa recovery, expanding delivery fleet networks beyond Metro Manila |
Leisure dining delivery, resort and hotel food ordering platform integration |
- Metro Manila - Accounting for approximately 52% of total Philippines Food Delivery Platform Market demand, Metro Manila houses the highest concentration of platform-active restaurant partners, corporate employer accounts, and tech-savvy individual consumers. GrabFood Philippines, ShopeeFood Philippines, and Foodpanda Philippines allocate the majority of their operational and promotional budgets toward Metro Manila's 17 cities and municipalities, where order density supports sub-30-minute average delivery times across established delivery zones.
- Central Luzon - Representing approximately 20% of platform-driven revenues, Central Luzon's urbanizing suburban corridors - including Clark Freeport Zone and Angeles City - are generating rising demand as BPO satellite offices and residential communities integrate food delivery platforms into daily meal routines. Expanding GCash and Maya digital payment infrastructure supports platform transaction growth across the region.
- Northern Luzon - Accounting for an estimated 14% of market revenues, Northern Luzon cities including Baguio, Dagupan, and Laoag are demonstrating increasing platform adoption as internet connectivity improves. Local restaurant digital onboarding programs by Foodpanda Philippines and ShopeeFood Philippines are accelerating partner network expansion across Ilocos and Cordillera provinces.
- Southern Luzon - Contributing approximately 14% of total market revenues, Southern Luzon's platform market is supported by tourism corridor recovery across Batangas, Tagaytay, and Bicol regions. Expanding GrabFood Philippines delivery zone coverage and local cloud kitchen operator growth are generating incremental order volume as weekend leisure and resort-area dining delivery demand develops through 2034.
Market Share & Competitive Landscape
The Philippines Food Delivery Platform Market features a concentrated competitive structure dominated by three major platform operators competing on delivery speed, subscription value, restaurant network breadth, and digital payment ecosystem integration. Commission rate negotiation, exclusive restaurant partner agreements, and loyalty program differentiation remain primary competitive battlegrounds.
|
Company |
Competitive Strength |
Primary Segment Served |
|---|---|---|
|
GrabFood Philippines |
Super-app integration, GrabPay wallet, widest restaurant network |
Individual consumers, corporate clients |
|
Foodpanda Philippines |
Pandamart grocery delivery, subscription bundles, tech-first logistics |
Individual consumers, suburban markets |
|
ShopeeFood Philippines |
Shopee e-commerce ecosystem, ShopeePay integration, promo-driven acquisition |
Individual consumers, value-tier buyers |
|
Jollibee Foods Corporation (JFC) |
Proprietary delivery app, brand loyalty, largest QSR chain network |
Individual consumers, family segment |
|
Others |
Niche platforms, cloud kitchen operators, hyperlocal delivery services |
Regional and specialized end-users |
Key Companies in the Philippines Food Delivery Platform Market
GrabFood Philippines
GrabFood Philippines, the food delivery vertical of Grab Holdings headquartered in Singapore, operates the Philippines' largest third-party food delivery platform by active restaurant listings and monthly order volumes. In 2025, GrabFood Philippines expanded its GrabUnlimited subscription plan nationally, offering tiered free delivery benefits and exclusive restaurant partner access. Its integration with GrabPay digital wallet and GrabMart grocery delivery positions it as the leading super-app food commerce operator across Metro Manila and provincial urban centers.
Foodpanda Philippines
Foodpanda Philippines, operating under Delivery Hero SE headquartered in Berlin, Germany, is one of the country's longest-established third-party food delivery platforms, active since 2012. In 2024, Foodpanda Philippines accelerated its Pandamart dark store grocery delivery expansion across Metro Manila, adding over 15 new fulfillment hubs to reduce grocery delivery times. Its subscription-based Pandapro loyalty program and logistics-first operational model reinforce its competitive positioning within the Philippines Food Delivery Platform Market's individual consumer segment.
Recent Developments
|
Year |
Company |
Development |
|---|---|---|
|
2025 |
GrabFood Philippines |
Expanded GrabUnlimited national subscription plan with enhanced free delivery tiers and restaurant partner exclusives |
|
2025 |
ShopeeFood Philippines |
Integrated ShopeePay Later buy-now-pay-later payment option into food delivery checkout flow |
Market Future Outlook
The Philippines Food Delivery Platform Market Forecast projects expansion from USD 2.09 billion in 2026 to USD 7.14 billion by 2034, advancing at a 16.60% CAGR through the forecast period. Corporate client segment growth, driven by rising enterprise meal benefit adoption across Metro Manila's BPO and technology employer base, will supplement individual consumer order volume growth. GrabFood Philippines, ShopeeFood Philippines, and Foodpanda Philippines are expected to deepen provincial delivery zone coverage and accelerate restaurant partner digital onboarding programs across Central and Southern Luzon through 2034.
Technology adoption - including AI-driven demand forecasting, cloud kitchen integration tools, and fleet electrification programs - will progressively reduce per-order delivery costs and expand platform operator margin structures. Regulatory compliance with data privacy standards under the Data Privacy Act and evolving DTI digital commerce guidelines will become baseline operational requirements. Sustainable packaging mandates and contactless payment infrastructure expansion will further shape platform operator investment priorities and restaurant partner compliance frameworks across the Philippines Food Delivery Platform Market through 2034.
Philippines Food Delivery Platform Market Report Coverage
This Philippines Food Delivery Platform Market Report covers the complete forecast period from 2026 to 2034, providing structured analysis across platform interface types, end-user categories, and regional delivery markets.
|
Report Attribute |
Details |
|---|---|
|
Market Name |
Philippines Food Delivery Platform Market |
|
Market Size (2026) |
USD 2.09 Billion |
|
Market Size (2034) |
USD 7.14 Billion |
|
Forecast Period |
2026–2034 |
|
CAGR |
16.60% |
|
Base Year |
2026 |
|
Historical Years |
2021–2025 |
|
Forecast Years |
2026–2034 |
|
Segments Covered |
By Business Model, By Product, By Platform Interface, By End-User |
|
Regions Covered |
Metro Manila, Northern Luzon, Central Luzon, Southern Luzon |
|
Key Companies |
GrabFood Philippines, Foodpanda Philippines, ShopeeFood Philippines, Jollibee Foods Corporation (JFC), Others |
|
Report Format |
PDF, Excel, PPT |
|
Customization |
Available as per client requirements |
Why Choose This Philippines Food Delivery Platform Market Report?
- Comprehensive coverage of the Philippines' rapidly expanding digital food delivery platform landscape through 2034.
- Accurate market sizing from USD 2.09 billion in 2026 through USD 7.14 billion forecast for 2034.
- Detailed segmentation by platform interface (Mobile Applications vs. Web Browsers) and end-user category (Individual Consumers vs. Corporate Clients).
- Regional insights covering Metro Manila, Central Luzon, Northern Luzon, and Southern Luzon with estimated market share percentages.
- Competitive profiling of 5 leading platform operators including GrabFood Philippines, Foodpanda Philippines, and ShopeeFood Philippines.
- Analysis of super-app integration, corporate meal benefit adoption, and fleet electrification trends reshaping platform operator strategies.
- Forecast data supporting strategic investment, market entry planning, and restaurant partner digital onboarding decisions.
- Research aligned with the Philippine Digital Economy Roadmap and DICT digital commerce development priorities through 2034.
Table of Contents
- Introduction
- Objective of the Study
- Product Definition
- Market Segmentation
- Study Variables
- Research Methodology
- Secondary Data Points
- Companies Interviewed
- Primary Data Points
- Breakdown of Primary Interviews
- Secondary Data Points
- Executive Summary
- Market Dynamics
- Drivers
- Challenges
- Opportunity Assessment
- Recent Trends and Developments
- Policy and Regulatory Landscape
- Philippines Food Delivery Platform Market Overview and Forecast Analysis (2021-2034)
- Market Size, By Value, By Growth Rate (CAGR/USD Billions)
- Demand – Supply Trends
- Market Share, By Business Model
- Logistics-Based Aggregators
- Restaurant-Specific Delivery
- Market Share, By Product
- Ready-to-Eat Meals
- Quick Commerce
- Specialty Niches
- Market Share, By Platform Interface
- Mobile Applications
- Web Browsers
- Market Share, By End-User
- Individual Consumers
- Corporate Clients
- Market Share, By Region
- Metro Manila
- Northern Luzon
- Central Luzon
- Southern Luzon
- Market Share, By Competitors
- Competition Characteristics
- Revenue Shares
- Logistics-Based Aggregators Philippines Food Delivery Platform Market Overview, 2021-2034F
- By Value (USD Million)
- By Product – Market Size & Forecast 2021-2034, USD Million
- Ready-to-Eat Meals
- Quick Commerce
- Specialty Niches
- Restaurant-Specific Delivery Philippines Food Delivery Platform Market Overview, 2021-2034F
- By Value (USD Million)
- By Product – Market Size & Forecast 2021-2034, USD Million
- Ready-to-Eat Meals
- Quick Commerce
- Specialty Niches
- Competitive Outlook (Company Profile - Partial List)
- GrabFood Philippines
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Foodpanda Philippines
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- ShopeeFood Philippines
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Jollibee Foods Corporation (JFC)
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Others
- GrabFood Philippines
- Contact Us & Disclaimer
Top Key Players & Market Share Outlook
- GrabFood Philippines
- Foodpanda Philippines
- ShopeeFood Philippines
- Jollibee Foods Corporation (JFC)
- Others
Frequently Asked Questions