
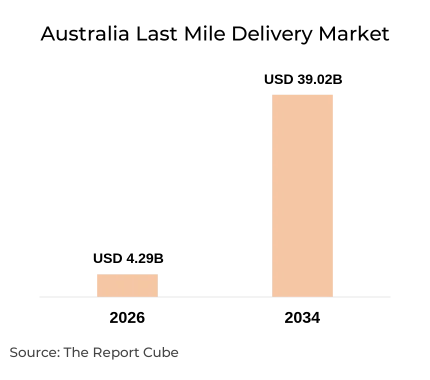
Build Your Custom Market Intelligence Report
Customize Your ReportAustralia Last Mile Delivery Market Key Takeaways
- A comprehensive Australia Last Mile Delivery Market Analysis reveals a sector valued at USD 4.29 billion in 2026, driven by accelerating e-commerce adoption.
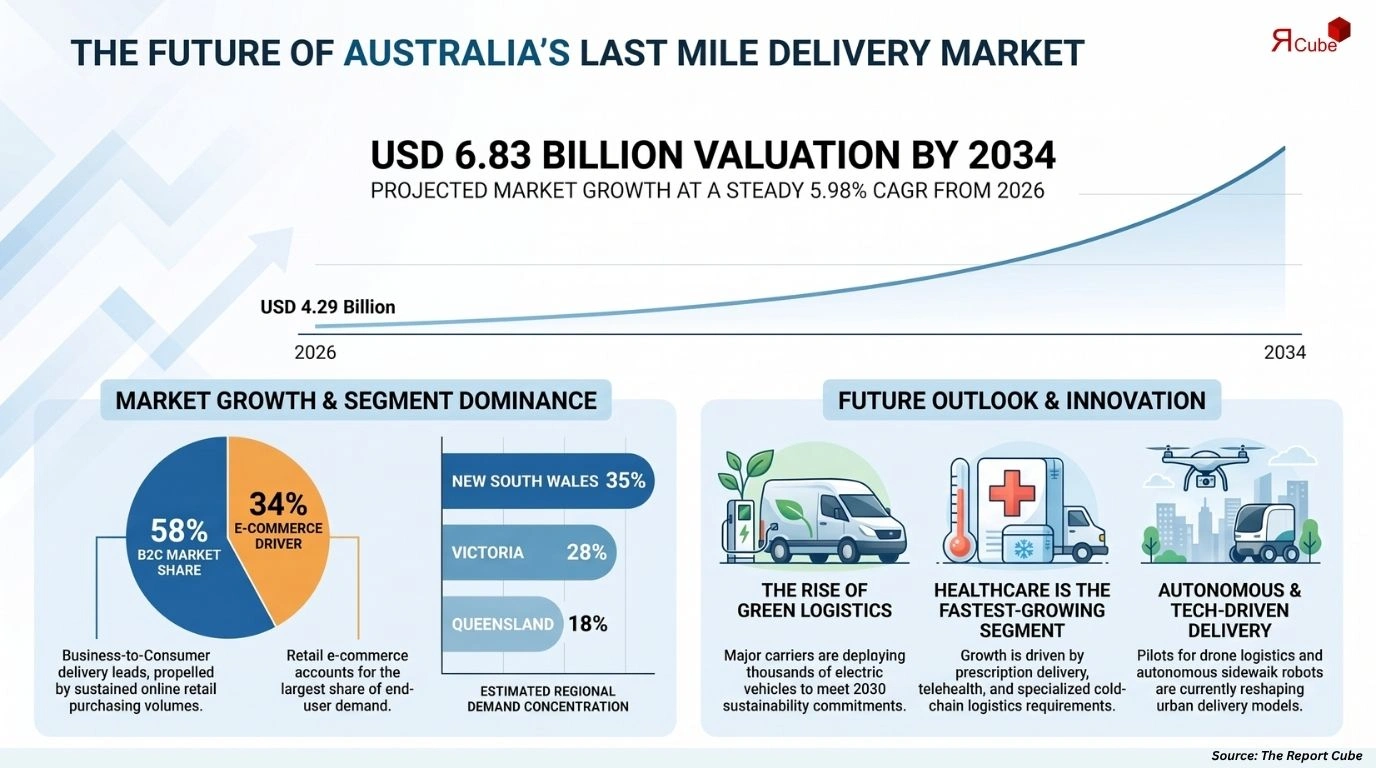
- Market projected to reach USD 6.83 billion by 2034, growing at a 5.98% CAGR across the forecast period.
- Business-to-Consumer (B2C) leads the business model segment, propelled by sustained online retail purchasing volumes.
- E-commerce retail dominates end-user industry procurement, commanding the largest share of last mile delivery demand.
- Healthcare and medical supplies is the fastest-growing end-user segment, driven by prescription delivery and cold-chain expansion.
- New South Wales holds the leading regional share, anchored by Sydney's dense urban logistics infrastructure.
- Australia Post, StarTrack, DHL Express, and Toll Group lead carrier operations across Australian last mile networks.
- Autonomous delivery vehicles, drone logistics pilots, and real-time tracking platforms are reshaping final-mile operational models.
Australia Last Mile Delivery Market Overview
The Australia Last Mile Delivery Market is projected to grow from USD 4.29 billion in 2026 to USD 6.83 billion by 2034, registering a 5.98% CAGR across the forecast period. Rapid expansion of domestic e-commerce platforms, increasing smartphone-enabled purchasing behavior, and growing demand for same-day and next-day delivery services are collectively driving procurement volumes across B2B, B2C, and C2C channels. Federal investment in urban logistics infrastructure, Australia Post's ongoing fleet electrification program, and government-supported last mile innovation grants under the National Freight and Supply Chain Strategy are reinforcing carrier capabilities. DHL Express, FedEx Express, and Toll Group have strengthened their regional distribution networks to address rising fulfillment demand across Australia's metropolitan and suburban delivery corridors.
Consumer expectations for transparent, contactless, and time-definite delivery experiences continue to accelerate digital transformation across Australia's last mile ecosystem. Retailers operating across fashion, electronics, and home furnishings categories are renegotiating carrier contracts to secure dedicated delivery windows aligned with premium customer experience standards. CouriersPlease and Aramex Australia have expanded their parcel locker networks and on-demand delivery platforms, targeting residential and small-business customers across high-density urban catchments. The growth of marketplace-driven C2C logistics and third-party seller fulfillment across platforms such as eBay Australia and Facebook Marketplace is broadening demand beyond traditional retail-initiated shipments into peer-driven delivery volumes nationwide.
Australia Last Mile Delivery Market Size & Forecast
|
Metric |
Details |
|---|---|
|
Market Size (2026) |
USD 4.29 Billion |
|
Market Size (2034) |
USD 6.83 Billion |
|
CAGR (2026–2034) |
5.98% |
|
Base Year |
2026 |
|
Historical Years |
2021–2025 |
|
Forecast Years |
2026–2034 |
This Australia Last Mile Delivery Market Size study values the sector at USD 4.29 billion in 2026, with projections reaching USD 6.83 billion by 2034 at a 5.98% CAGR. Growth significantly outpaces the broader Asia-Pacific logistics average, driven by Australia's advanced e-commerce penetration, rising healthcare delivery demand, and rapid adoption of technology-enabled carrier routing platforms across urban fulfillment networks.
Australia Last Mile Delivery Market Dynamics
Australia's last mile delivery sector is undergoing structural transformation as e-commerce volumes intensify, consumer delivery expectations rise, and logistics operators invest in automation, electrification, and data-driven route optimization. Expanding suburban residential zones, healthcare delivery mandates, and government freight infrastructure programs collectively strengthen network coverage and accelerate carrier service diversification across Australia's diverse geographic delivery landscape.
|
Factor |
Type |
Specific Impact on Market |
Magnitude |
|---|---|---|---|
|
E-commerce retail volume expansion |
Driver |
Increases parcel delivery frequency and B2C carrier procurement volumes |
High |
|
Same-day and express delivery demand |
Driver |
Accelerates investment in urban micro-fulfillment and dedicated delivery fleet capacity |
High |
|
Rising fuel and operational costs |
Challenge |
Compresses carrier margins and limits route expansion into lower-density regional areas |
Medium |
|
Healthcare and pharmaceutical delivery growth |
Opportunity |
Opens high-value regulated delivery segment with temperature-controlled cold chain requirements |
High |
|
Autonomous vehicle and drone delivery pilots |
Trend |
Enables cost-reduction and coverage expansion across suburban and remote delivery zones |
Medium |
- Growth Drivers - E-Commerce Volume and Express Delivery Mandates: The Australia Last Mile Delivery Market Growth is primarily driven by accelerating domestic e-commerce transaction volumes and the proliferation of same-day fulfillment commitments by major retail platforms. Australia Post processed over 750 million domestic parcels in 2024, reflecting structural demand intensity across the B2C delivery segment. StarTrack and Toll Group have correspondingly expanded their urban micro-fulfillment facility networks to shorten delivery radius distances and support tight delivery window commitments for retail partners.
- Market Opportunities - Healthcare Delivery and Cold Chain Logistics: Expanding telehealth adoption, prescription delivery mandates under Australia's digital health strategy, and post-pandemic pharmaceutical home delivery normalization collectively position healthcare and medical supplies as the highest-value growth opportunity across last mile delivery channels. Aramex Australia and DHL Express have invested in temperature-controlled last mile delivery infrastructure to capture regulated pharmaceutical and pathology sample transport contracts from hospital networks and retail pharmacy chains.
- Industry Challenges - Geographic Dispersion and Urban Congestion: Australia's vast geographic spread creates inherent per-parcel cost disadvantages relative to more densely populated markets. Simultaneously, major city congestion across Sydney, Melbourne, and Brisbane increases delivery time variability and reduces carrier fleet utilization efficiency. Regulatory restrictions on drone delivery altitude and urban airspace usage create compliance complexity for carriers piloting autonomous last mile solutions across metropolitan zones.
Australia Last Mile Delivery Market Trends
- Emerging Trends: Among the most significant Australia Last Mile Delivery Market Trends is the rapid scaling of parcel locker and out-of-home delivery point networks across supermarkets, petrol stations, and transit hubs. Australia Post's 24/7 parcel locker rollout has exceeded 5,000 locations nationwide, responding to consumer demand for flexible, contactless collection options that reduce failed first-attempt delivery rates and associated redelivery costs across dense residential catchments.
- Technology Trends: Artificial intelligence-powered route optimization, electric delivery vehicle adoption, and real-time delivery tracking platforms powered by GPS and IoT telemetry are entering mainstream carrier operations across Australia. FedEx Express and DHL Express are piloting autonomous delivery robots across select suburban precincts in Sydney and Melbourne. Predictive delivery window algorithms are improving first-attempt success rates and reducing customer service escalation volumes for national retail clients.
- Consumer / Buyer Trends: Australian online shoppers increasingly prioritize delivery speed, flexibility, and sustainability credentials when selecting retail platforms. Over 70% of Australian consumers surveyed in 2024 expressed willingness to pay a premium for same-day delivery on high-value purchases across electronics and fashion categories. Corporate B2B buyers are integrating carrier API connectivity directly into procurement and inventory management platforms, enabling real-time shipment visibility and automated carrier selection based on route-specific performance benchmarks.
Need Specific Data, Let’s Customize the Report for You
Request CustomizationAustralia Last Mile Delivery Market Segment Analysis
Australia's last mile delivery market encompasses distinct business model structures and end-user industry verticals, each shaped by unique shipment frequency requirements, delivery urgency profiles, and specialized handling mandates.
By Business Model
|
Business Model |
Estimated Share (2026) |
Key Characteristics |
|---|---|---|
|
Business-to-Consumer (B2C) |
58% |
Dominant segment; driven by e-commerce parcel volumes, fashion, electronics, and home goods delivery |
|
Business-to-Business (B2B) |
31% |
Stable; driven by wholesale distribution, medical supply chain, and corporate document logistics |
|
Customer-to-Consumer (C2C) |
11% |
Growing; driven by marketplace resale platforms, peer-to-peer delivery, and social commerce logistics |
Business-to-Consumer delivery commands the largest Australia Last Mile Delivery Market Share at an estimated 58% in 2026, anchored by Australia Post's national parcel network and StarTrack's premium B2C express service. CouriersPlease and Aramex Australia serve mid-market e-commerce retailers with flexible residential delivery solutions. B2B delivery, representing approximately 31%, is sustained by Toll Group's industrial distribution capabilities and Allied Express's metropolitan freight network. The C2C segment, though the smallest at 11%, is expanding rapidly as eBay Australia, Facebook Marketplace, and peer-to-peer platforms deepen integration with on-demand delivery carriers.
By End-User Industry
|
End-User Industry |
Estimated Share (2026) |
Growth Outlook |
|---|---|---|
|
E-commerce Retail |
34% |
Steady-high; core demand driver across B2C parcel networks nationally |
|
Fashion and Lifestyle |
18% |
Moderate; growth linked to returns management and same-day express commitments |
|
Consumer Electronics and Appliances |
15% |
Steady; supported by high-value, signature-required delivery requirements |
|
Home and Furniture |
13% |
Growing; driven by large-format and white-glove delivery service expansion |
|
Healthcare and Medical Supplies |
11% |
Fastest-growing; cold chain, regulated delivery, and prescription fulfillment demand |
|
Beauty, Wellness and Personal Care |
6% |
Growing; driven by subscription box and direct-to-consumer wellness platform growth |
|
Others |
3% |
Stable; includes automotive parts, industrial supplies, and government procurement |
E-commerce retail dominates the end-user segment at approximately 34% in 2026, with Australia Post, StarTrack, and DHL Express serving the largest national retail and marketplace accounts. Fashion and lifestyle represents 18% of delivery volumes, with CouriersPlease and Aramex Australia providing next-day residential services for apparel and footwear brands. Healthcare and medical supplies, while representing 11%, is the fastest-growing end-user category as Toll Group and FedEx Express expand temperature-controlled pharmaceutical delivery infrastructure to serve hospital networks, aged care facilities, and retail pharmacy chains across metropolitan and regional Australia.
Australia Last Mile Delivery Market Regional Analysis
|
Region |
Estimated Market Share |
Key Growth Factors |
Consumer Trends |
|---|---|---|---|
|
New South Wales |
35% |
Sydney metropolitan density, largest e-commerce consumer base, port logistics proximity |
High B2C parcel frequency, premium express delivery adoption |
|
Victoria |
28% |
Melbourne urban growth, fashion and lifestyle retail concentration, cold chain expansion |
Same-day delivery uptake, healthcare logistics growth |
|
Queensland |
18% |
Brisbane suburban expansion, tourism logistics, medical supply chain growth |
Regional parcel locker adoption, C2C platform growth |
|
Western Australia |
12% |
Perth peri-urban expansion, mining sector B2B logistics, drone delivery pilot programs |
Extended delivery radius, autonomous delivery trials |
|
Rest of Australia |
7% |
Regional and remote coverage mandates, community service obligations |
Rural parcel consolidation, community hub collection points |
- New South Wales - Accounting for approximately 35% of national last mile delivery demand, New South Wales is anchored by Sydney's role as Australia's largest consumer market and primary international port gateway. Australia Post's primary distribution hub and StarTrack's Sydney metro express network serve the region's dense residential and commercial delivery corridors. High B2C parcel volumes from major fashion, electronics, and grocery platforms sustain carrier procurement intensity across inner-city and suburban zones.
- Victoria - Victoria contributes approximately 28% of market demand, with Melbourne's expanding population base and high fashion and lifestyle retail concentration driving sustained delivery volumes. DHL Express and Toll Group maintain significant operational footprints across Melbourne's metropolitan freight network. Cold chain delivery expansion for pharmaceutical and meal-kit categories is accelerating infrastructure investment in temperature-controlled last mile assets across the state's suburban corridors.
- Queensland - Representing approximately 18% of national delivery demand, Queensland's growth is driven by Brisbane's rapid suburban expansion, the state's diverse tourism logistics requirements, and increasing medical supply chain delivery frequency. CouriersPlease and Aramex Australia have expanded parcel locker rollouts across Queensland's regional commercial hubs as part of broader network densification strategies targeting peri-urban residential growth zones.
- Western Australia - Western Australia accounts for approximately 12% of market share, with Perth's peri-urban sprawl, significant B2B mining sector logistics demand, and active drone delivery pilot programs defining the state's distinctive delivery profile. Allied Express and FedEx Express serve the region's extended geographic delivery requirements. CASA-approved drone delivery trials in Western Australia represent some of Australia's most advanced autonomous last mile technology deployments.
- Rest of Australia - The remaining 7% of market demand is distributed across South Australia, Tasmania, the Australian Capital Territory, and the Northern Territory, where community service obligation delivery mandates sustain Australia Post's operational presence. Rural parcel consolidation models and community collection point networks are the primary fulfillment mechanisms for low-density regional catchments.
Australia Last Mile Delivery Market Share & Competitive Landscape
Australia's last mile delivery competitive environment is characterized by the dominance of Australia Post's national network alongside intensifying competition from global express carriers, regional specialists, and technology-enabled delivery platforms. Key players differentiate through network coverage breadth, delivery speed commitments, technology integration capabilities, and specialized handling services for high-value or regulated shipment categories.
|
Company |
Competitive Strength |
Primary Segment Served |
|---|---|---|
|
Australia Post |
National network scale, parcel locker infrastructure, community service obligation coverage |
B2C e-commerce, government, regional delivery |
|
StarTrack |
Premium express B2C and B2B delivery, Australia Post integration |
B2B express, premium retail, corporate accounts |
|
DHL Express |
Global network integration, cold chain capability, premium international last mile |
Healthcare, e-commerce retail, fashion |
|
FedEx Express |
International connectivity, temperature-controlled logistics, high-value delivery |
Healthcare, electronics, corporate B2B |
|
Toll Group |
Industrial B2B logistics, large-format freight, national warehouse integration |
B2B distribution, home and furniture, mining |
|
Aramex Australia |
Flexible residential delivery, parcel locker network, SME e-commerce focus |
B2C e-commerce, fashion, beauty and wellness |
|
CouriersPlease |
SME parcel delivery, suburban network, competitive pricing |
B2C retail, fashion and lifestyle, C2C |
|
Allied Express |
Metropolitan freight, same-day delivery, industrial distribution |
B2B logistics, consumer electronics |
|
Others |
Regional specialists, niche sector delivery, technology-enabled platforms |
Various segments |
Key Companies in the Australia Last Mile Delivery Market
Australia Post
Australia Post, headquartered in Melbourne, Victoria, is Australia's national postal carrier and the country's largest last mile delivery network operator, processing over 750 million domestic parcels annually. In 2025, Australia Post accelerated its fleet electrification program, deploying over 3,000 electric delivery vehicles across Sydney, Melbourne, and Brisbane metropolitan networks. Its integrated parcel locker infrastructure, MyPost Digital platform, and e-commerce merchant API ecosystem position Australia Post as the structurally dominant carrier across B2C last mile delivery operations nationally.
DHL Express
DHL Express, a division of Deutsche Post DHL Group headquartered in Bonn, Germany, operates one of Australia's most extensive international and domestic express delivery networks. In 2025, DHL Express expanded its GoGreen Plus sustainable delivery program in Australia, introducing carbon-neutral last mile delivery options for e-commerce and pharmaceutical clients across major metropolitan zones. Its temperature-controlled delivery infrastructure, real-time tracking platforms, and healthcare logistics expertise make DHL Express a preferred carrier for regulated and high-value last mile shipment categories.
Australia Last Mile Delivery Market Recent Developments
|
Year |
Company |
Development |
|---|---|---|
|
2025 |
Australia Post |
Deployed 3,000+ electric delivery vehicles across Sydney, Melbourne, and Brisbane; accelerated fleet electrification as part of 2030 sustainability commitment |
|
2025 |
DHL Express |
Expanded GoGreen Plus carbon-neutral last mile delivery program in Australia for e-commerce and pharmaceutical clients |
|
2025 |
Toll Group |
Launched expanded white-glove home delivery service for furniture and appliance retailers across eastern Australian metro markets |
|
Jan 2025 |
FedEx Express |
Announced expanded temperature-controlled pharmaceutical delivery corridors across Queensland and Western Australia |
Australia Last Mile Delivery Market Future Outlook
The Australia Last Mile Delivery Market Forecast projects continued growth at a 5.98% CAGR through 2034, reaching USD 6.83 billion as e-commerce penetration deepens, healthcare delivery mandates expand, and B2B logistics modernization accelerates across industrial and corporate procurement channels. Australia Post, Toll Group, and DHL Express are expected to lead market penetration through investments in electric vehicle fleets, autonomous delivery technology, and AI-driven fulfillment platforms. Expanding suburban residential zones and growing regional coverage obligations will sustain carrier network investment across all five major state markets through the forecast period.
Technological advancement in last mile delivery - including drone delivery commercialization under evolving CASA regulatory frameworks, autonomous sidewalk robot deployments, and predictive route optimization powered by machine learning - will progressively reduce per-parcel delivery costs for metropolitan operators. Sustainability compliance requirements, including carrier carbon disclosure mandates and packaging recyclability standards, will become baseline operational requirements as Australian retail brands and corporate shippers integrate environmental performance metrics into carrier selection and contract renewal criteria through 2034.
Australia Last Mile Delivery Market Report Coverage
This Australia Last Mile Delivery Market Report covers comprehensive market sizing, segmentation, competitive intelligence, and regional analysis across the 2026–2034 forecast period.
|
Report Attribute |
Details |
|---|---|
|
Market Name |
Australia Last Mile Delivery Market |
|
Market Size (2026) |
USD 4.29 Billion |
|
Market Size (2034) |
USD 6.83 Billion |
|
Forecast Period |
2026–2034 |
|
CAGR |
5.98% |
|
Base Year |
2026 |
|
Historical Years |
2021–2025 |
|
Forecast Years |
2026–2034 |
|
Segments Covered |
By Business Model (B2B, B2C, C2C); By End-User Industry (E-commerce Retail, Fashion and Lifestyle, Beauty, Wellness and Personal Care, Home and Furniture, Consumer Electronics and Appliances, Healthcare and Medical Supplies, Others) |
|
Regions Covered |
New South Wales, Victoria, Queensland, Western Australia, Rest of Australia |
|
Key Companies |
Australia Post, StarTrack, DHL Express, FedEx Express, Toll Group, Aramex Australia, CouriersPlease, Allied Express, Others |
|
Report Format |
PDF, Excel, PPT |
|
Customization |
Available as per client requirements |
Why Choose This Australia Last Mile Delivery Market Report?
- Comprehensive coverage of Australia's rapidly scaling last mile delivery industry across all business model and end-user segments.
- Accurate market sizing from USD 4.29 billion in 2026 through the full 2034 forecast horizon.
- Detailed segmentation by business model (B2B, B2C, C2C) and end-user industry with estimated share percentages.
- State-level regional analysis covering New South Wales, Victoria, Queensland, Western Australia, and Rest of Australia.
- Competitive profiling of 8 leading carriers including Australia Post, DHL Express, Toll Group, and Aramex Australia.
- Analysis of autonomous delivery, electric vehicle adoption, and parcel locker expansion trends reshaping last mile operations.
- Healthcare and pharmaceutical delivery opportunity assessment aligned with Australia's digital health infrastructure strategy.
- Forecast data supporting strategic investment decisions, carrier partnership planning, and market entry evaluation through 2034.
Table of Contents
- Introduction
- Objective of the Study
- Product Definition
- Market Segmentation
- Study Variables
- Research Methodology
- Secondary Data Points
- Companies Interviewed
- Primary Data Points
- Breakdown of Primary Interviews
- Secondary Data Points
- Executive Summary
- Market Dynamics
- Drivers
- Challenges
- Opportunity Assessment
- Recent Trends and Developments
- Policy and Regulatory Landscape
- Australia Last Mile Delivery Market Overview and Forecast Analysis (2021-2034)
- Market Size, By Value, By Growth Rate (CAGR/USD Billions)
- Demand – Supply Trends
- Market Share, By Service
- Standard Delivery
- Same-day
- Express Delivery
- Market Share, By Business Model
- Business-to-Business (B2B)
- Business-to-Consumer (B2C)
- Customer-to-Consumer (C2C)
- Market Share, By End-user Industry
- E-commerce Retail
- Fashion and Lifestyle
- Beauty, Wellness and Personal Care
- Home and Furniture
- Consumer Electronics and Appliances
- Healthcare and Medical Supplies
- Others
- Market Share, By Region
- New South Wales
- Victoria
- Queensland
- Western Australia
- Rest of Australia
- Market Share, By Competitors
- Competition Characteristics
- Revenue Shares
- Standard Delivery Australia Last Mile Delivery Market Overview, 2021-2034F
- By Value (USD Million)
- By Business Model – Market Size & Forecast 2021-2034, USD Million
- Business-to-Business (B2B)
- Business-to-Consumer (B2C)
- Customer-to-Consumer (C2C)
- Same-day Australia Last Mile Delivery Market Overview, 2021-2034F
- By Value (USD Million)
- By Business Model – Market Size & Forecast 2021-2034, USD Million
- Business-to-Business (B2B)
- Business-to-Consumer (B2C)
- Customer-to-Consumer (C2C)
- Express Delivery Australia Last Mile Delivery Market Overview, 2021-2034F
- By Value (USD Million)
- By Business Model – Market Size & Forecast 2021-2034, USD Million
- Business-to-Business (B2B)
- Business-to-Consumer (B2C)
- Customer-to-Consumer (C2C)
- Competitive Outlook (Company Profile - Partial List)
- Australia Post
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- StarTrack
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- DHL Express
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- FedEx Express
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Toll Group
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Aramex Australia
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- CouriersPlease
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Allied Express
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Others
- Australia Post
- Contact Us & Disclaimer
Top Key Players & Market Share Outlook
- Australia Post
- StarTrack
- DHL Express
- FedEx Express
- Toll Group
- Aramex Australia
- CouriersPlease
- Allied Express
- Others
Frequently Asked Questions