
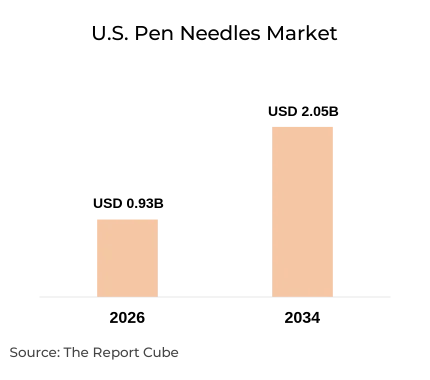
Build Your Custom Market Intelligence Report
Customize Your ReportKey Highlights
- The U.S. Pen Needles Market was valued at USD 0.93 billion in 2026.
- The market is forecast to reach USD 2.05 billion by 2034.
- The market is expanding at a CAGR of 10.40% during 2026-2034.
- By product type, Standard Pen Needles led with approx 85% share in 2026, while Safety Pen Needles are the faster-growing category.
- By therapy, Insulin Therapy remains the largest demand area, with an approx 82% share in 2026.
- Recurring insulin administration across a large diabetes population is the primary growth driver.
- The competitive landscape is consolidating. In May 2026, embecta announced a deal to acquire Owen Mumford.
Market Outlook
Pen needles are sterile, single-use needles fitted to injection pens for subcutaneous medication delivery, mainly insulin. They are replaced after each injection, so every patient on pen therapy generates recurring demand. The U.S. Pen Needles Market therefore ties closely to diabetes care, clinical injection guidance and access to reimbursed medical supplies.
Demand comes from homecare users, hospitals, diabetes clinics and ambulatory care centers, with retail, hospital, online and specialty pharmacies as the main channels. Needle length, gauge and safety design shape purchasing. Homecare accounts for approx 75% of demand in 2026, reflecting self-administered treatment.
The U.S. Pen Needles Market is projected to grow from USD 0.93 billion in 2026 to USD 2.05 billion by 2034 at a CAGR of 10.40%. Growth is supported by diabetes prevalence, recurring needle replacement, shorter and finer needle designs and wider use of injectable therapies delivered through compatible pens.
The competitive environment includes established diabetes-care manufacturers and specialist device suppliers. Opportunities lie in safety designs, 4 mm needles, online replenishment and pharmaceutical co-packaging. Growth in injectable medicines will not automatically convert into detachable pen needle demand, because some therapies use prefilled or integrated devices.
Government Regulations
Pen needles are regulated as medical devices by the U.S. Food and Drug Administration. The FDA classifies hypodermic single-lumen needles under 21 CFR 880.5570 (product code FMI) as Class II devices, generally requiring 510(k) premarket notification. Manufacturers must also meet Quality Management System requirements covering sterility, design controls, labeling and complaint handling. Workplace sharps rules add a second layer: OSHA’s Bloodborne Pathogens Standard, updated under the Needlestick Safety and Prevention Act, requires employers to evaluate and use safer needle devices, which supports institutional demand for safety pen needles. The CDC’s National Diabetes Statistics Report provides the public-health baseline for the treated population. Together, these frameworks raise entry barriers, favor suppliers with documented quality systems and regulatory clearance, and influence product design and institutional purchasing.
U.S. Pen Needles Market Dynamics
Demand is shaped by the diabetes patient base, recurring insulin administration, clinical guidance on injection technique, reimbursement conditions and the spread of alternative delivery formats. These forces determine both the volume of needles consumed and the mix between standard, safety and shorter-length products.
|
Factor |
Type |
Specific Impact on Market |
Magnitude |
|---|---|---|---|
|
Diabetes prevalence and insulin pen use |
Driver |
Large treated population creates recurring needle replacement demand |
High |
|
Preference for convenient injection systems |
Driver |
Pen portability and finer, shorter needles support adherence and repeat purchasing |
Medium-High |
|
Safety pen needle development |
Opportunity |
Needlestick protection supports differentiation in institutional settings |
Medium |
|
Online and direct-to-consumer supply |
Opportunity |
Subscription replenishment and home delivery improve convenience |
Medium |
|
Reimbursement and pricing pressure |
Challenge |
Out-of-pocket costs and margin compression affect standard needles |
Medium-High |
|
Prefilled and integrated delivery formats |
Challenge |
Limits conversion of injectable therapy growth into detachable needle demand |
Medium-High |
Growth Drivers: Rising Diabetes Prevalence and Continued Insulin Use
The CDC’s National Diabetes Statistics Report estimates that 40.1 million people in the United States had diagnosed or undiagnosed diabetes in 2023, including 29.1 million with diagnosed diabetes. Not every patient uses insulin pens, but those who do require a fresh compatible needle for each injection. Because treatment may involve several daily doses, the insulin-treated population creates steady, recurring consumption that underpins the U.S. Pen Needles Market.
Market Opportunities: Safety Pen Needles and Online Distribution
Safety pen needles let manufacturers differentiate through shielding mechanisms that reduce accidental needlestick exposure after injection. Demand is most relevant where healthcare workers, caregivers or patients handle used needles, and OSHA sharps requirements reinforce institutional interest. Online and specialty channels offer a related opportunity, since recurring purchases suit subscription replenishment and home delivery. Adoption will depend on price, usability, prescription rules and insurance coverage, so suppliers with reliable fulfilment and clear compatibility information are better placed.
Industry Challenges: Reimbursement Limits and Alternative Delivery Formats
Pen needles are repeat-purchase supplies, so coverage differences, out-of-pocket costs and price competition directly affect patient purchasing and supplier margins. A second challenge is delivery format. Some injectable medicines, including certain GLP-1 products, are supplied in prefilled pens or autoinjectors that do not need a separately purchased detachable needle. Manufacturers must therefore assess demand at product level rather than assuming total injectable drug growth translates into pen needle sales.
Need Specific Data, Let’s Customize the Report for You
Request CustomizationMarket Trends: Shift Toward Shorter and Safer Needle Designs
Shorter needles, particularly 4 mm, are gaining clinical attention because they reduce the risk of unintended intramuscular insulin delivery, and the American Diabetes Association’s 2026 Standards of Care support 4 mm pen needles across ages and body types. Manufacturers are also pursuing finer gauges for comfort and safety mechanisms for institutional use. Together, these shifts move the product mix toward premium designs and support the faster modelled growth of safety and 4 mm categories.
U.S. Pen Needles Market Segment Analysis
The U.S. Pen Needles Market is segmented by product type, therapy, needle length, distribution channel, end user and application. Each category reflects a different demand dimension, from device design and clinical use to purchasing channel and care setting.
By End User
- Homecare Settings
- Hospitals
- Diabetes Clinics
- Ambulatory Care Centers
- Other Settings
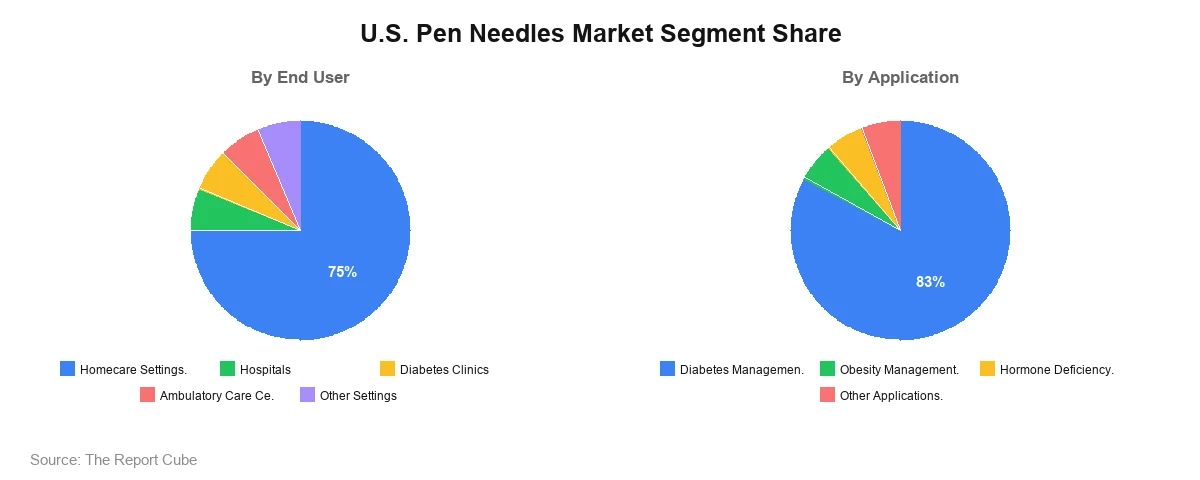
Homecare Settings lead the category with an approx 75% share in 2026, since most patients self-administer insulin and other injectables and buy needles repeatedly through pharmacies or online suppliers. Hospitals are the second analyzed segment, driven by supervised administration, patient education and demand for safety devices to protect staff. Diabetes Clinics, Ambulatory Care Centers and Other Settings contribute smaller volumes through clinical administration and training.
By Application
- Diabetes Management
- Obesity Management
- Hormone Deficiency Treatment
- Other Applications
Diabetes Management leads the category with an approx 82% share in 2026, reflecting the established reliance on insulin pens and the size of the treated population. Obesity Management is the second analyzed segment and is expected to grow quickly as injectable weight-management therapies spread. The addressable need for detachable needles depends on each medicine’s delivery format. Hormone Deficiency Treatment and Other Applications contribute smaller, steadier volumes.
U.S. Pen Needles Market Regional Analysis
The U.S. Pen Needles Market is analyzed across four U.S. regions. Demand varies with diabetes prevalence, insurance coverage, pharmacy networks and the concentration of hospitals and diabetes-care providers. Comparable regional revenue data are not available from the research used, so no regional shares are assigned.
|
Region |
Key Growth Factors |
Industry Trends |
|---|---|---|
|
Northeast |
Established hospital networks and specialist diabetes-care access |
Institutional demand for safety and shorter needle formats |
|
Midwest |
Chronic disease management needs and community providers |
Strong retail pharmacy-based supply |
|
South |
Large population base and diabetes-care requirements |
Homecare-driven recurring demand |
|
West |
Healthcare innovation and digital pharmacy services |
Growing online and subscription replenishment |
Competitive Landscape
The U.S. Pen Needles Market includes established diabetes-care manufacturers and specialist device suppliers. Competition rests on product quality, compatibility with commonly used pens, safety features, distribution partnerships and pricing. The table summarizes participants by general capability and does not represent a market-share ranking.
|
Company |
Competitive Strength |
Primary Segment Served |
|---|---|---|
|
embecta |
Ultra-Fine pen needle portfolio with broad U.S. diabetes-care presence |
Standard and safety pen needles, insulin therapy |
|
Owen Mumford |
Unifine pen needles with comfort and safety-oriented designs |
Standard and safety pen needles |
|
Ypsomed |
Injection systems and Clickfine pen needles |
Insulin and other injectable therapies |
|
Terumo |
Broad injection and healthcare product portfolio |
Pen needles and injection products |
|
B. Braun |
Medical devices and healthcare supplies, category participation requires product-level verification |
Hospital and clinical supplies |
|
HTL-STREFA |
Single-use medical devices, including needles and injection products |
Pen needles and injection-related devices |
|
MHC Medical Products |
EasyTouch diabetes-care range |
Retail and homecare diabetes supplies |
|
Artsana |
InsuPen range and injection-related healthcare products |
Insulin pen needles |
- embecta: embecta is a diabetes-care company based in Parsippany, New Jersey, spun off from Becton, Dickinson and Company in 2022, with BD-branded pen needles and insulin syringes now part of its portfolio. Its products are sold in more than 100 countries. It is expanding into pharmaceutical co-packaging of pen needles with generic GLP-1 therapies and is developing market-appropriate pen needles under FDA review. Its competitive strength lies in scale, brand recognition and distribution.
- Owen Mumford: Owen Mumford is a UK-based medical device company known for the Unifine pen needle range and wider injection and autoinjector technologies for pharmaceutical partners. Its portfolio overlaps with embecta in pen needles, safety pen needles and syringes but extends more broadly into drug-delivery devices. In May 2026, embecta announced an agreement to acquire the company. Its strength lies in comfort-focused needle design, safety products and combination-device development.
Recent Developments and Updates
- August 2026: embecta’s third-quarter fiscal 2026 results reported that its market-appropriate pen needles are progressing through regulatory review with the U.S. FDA. The company also reported generic GLP-1 therapies featuring embecta pen needles launched in Canada, Brazil and South Africa, showing pharmaceutical co-packaging gaining traction.
- May 2026: embecta announced an agreement to acquire Owen Mumford, with the deal announced on May 15, 2026. Trade reports put the value at roughly USD 200 million. The deal combines two pen needle portfolios and adds drug-delivery capabilities, signaling consolidation among established suppliers.
- 2026: FDA records show continued 510(k) activity for pen needle devices under product code FMI and 21 CFR 880.5570, indicating ongoing regulatory submissions and product refresh across the category.
U.S. Pen Needles Market Future Outlook
The U.S. Pen Needles Market is expected to grow steadily through 2034, supported by recurring insulin administration, disposable needle replacement and demand for convenient injection products. Standard pen needles are likely to remain the largest category, while shorter 4 mm needles, finer gauges and safety mechanisms provide differentiation. Online replenishment and pharmaceutical co-packaging offer additional routes to volume, particularly where compatible detachable needles are bundled with injectable therapies.
Competition is likely to center on portfolio breadth, quality systems, distribution reach and pricing, with consolidation such as the embecta and Owen Mumford transaction reshaping positioning. Risks include reimbursement pressure, the shift toward prefilled and integrated delivery devices, and insulin pump adoption reducing demand for traditional pen needles. Manufacturers will need to assess product-level device formats instead of relying on total injectable drug growth.
U.S. Pen Needles Market Report Coverage
This U.S. Pen Needles Market report summarizes market valuation, forecast, segmentation, regional framework and competitive ecosystem for 2026-2034.
|
Parameter |
Details |
|---|---|
|
Market Name |
U.S. Pen Needles Market |
|
Market Size (Base Year) |
USD 0.93 billion (2026) |
|
Market Size (Forecast Year) |
USD 2.05 billion (2034) |
|
CAGR |
10.40% |
|
Base Year |
2026 |
|
Historical Period |
2021-2025 |
|
Forecast Period |
2026-2034 |
|
Geographic Scope |
United States |
|
Segmentation |
By Product Type, By Therapy, By Needle Length, By Distribution Channel, By End User, By Application |
|
Regions Covered |
Northeast, Midwest, South, West |
|
Key Companies |
embecta, Owen Mumford, Ypsomed, Terumo, B. Braun, HTL-STREFA, MHC Medical Products, Artsana |
|
Customization |
Available as per requirement |
Why Choose This U.S. Pen Needles Market Report?
- Presents the 2026 market size, 2034 forecast and 10.40% CAGR for the U.S. Pen Needles Market.
- Segments the market by product type, therapy, needle length, channel, end user and application.
- Reviews drivers, opportunities, challenges and trends shaping pen needle demand.
- Provides regional context across the Northeast, Midwest, South and West, with unavailable shares identified.
- Profiles key manufacturers by capability and primary segment served.
- Covers safety needles, shorter needle formats, online channels and GLP-1 co-packaging.
- Summarizes FDA, CDC and OSHA context to support product, sourcing and investment decisions.
Table of Contents
- Introduction
- Objective of the Study
- Product Definition
- Market Segmentation
- Study Variables
- Research Methodology
- Secondary Data Points
- Companies Interviewed
- Primary Data Points
- Breakdown of Primary Interviews
- Secondary Data Points
- Executive Summary
- Market Dynamics
- Drivers
- Challenges
- Opportunity Assessment
- Recent Trends and Developments
- Policy and Regulatory Landscape
- U.S. Electric Water Heater Market Overview and Forecast Analysis (2021-2034)
- Market Size, By Value, By Growth Rate (CAGR/USD Billions)
- Demand – Supply Trends
- Market Share, By Product Type
- Storage
- Non-Storage
- Market Share, By Technology
- Electric Resistance Storage
- Heat Pump Storage
- Instantaneous / Tankless Electric
- Market Share, By Capacity
- Below 30 Gallons
- 30–50 Gallons
- 51–80 Gallons
- Above 80 Gallons
- Market Share, By Application
- Residential
- Commercial
- Market Share, By Distribution Channel
- Wholesale
- Retail
- Online
- Direct Sales
- Market Share, By End User
- Households
- Hotels
- Hospitals
- Restaurants
- Educational Institutions
- Offices
- Industrial & Other Commercial
- Market Share, By Region
- Northeast
- Midwest
- South
- West
- Market Share, By Competitors
- Competition Characteristics
- Revenue Shares
- Storage U.S. Electric Water Heater Market Overview, 2021-2034F
- By Value (USD Million)
- By Technology – Market Size & Forecast 2021-2034, USD Million
- Electric Resistance Storage
- Heat Pump Storage
- Instantaneous / Tankless Electric
- Non-Storage U.S. Electric Water Heater Market Overview, 2021-2034F
- By Value (USD Million)
- By Technology – Market Size & Forecast 2021-2034, USD Million
- Electric Resistance Storage
- Heat Pump Storage
- Instantaneous / Tankless Electric
- Competitive Outlook (Company Profile – Partial List)
- A.O. Smith Corporation
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Rheem Manufacturing Company
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Bradford White Corporation
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- GE Appliances
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Bosch Thermotechnology
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Stiebel Eltron
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Rinnai America Corporation
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Hubbell Electric Heater Company
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Midea Group
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Others
- A.O. Smith Corporation
- Contact Us & Disclaimer
Top Key Players & Market Share Outlook
- embecta
- Owen Mumford
- Ypsomed
- Terumo
- B. Braun
- HTL-STREFA
- MHC Medical Products
- Artsana
Frequently Asked Questions