
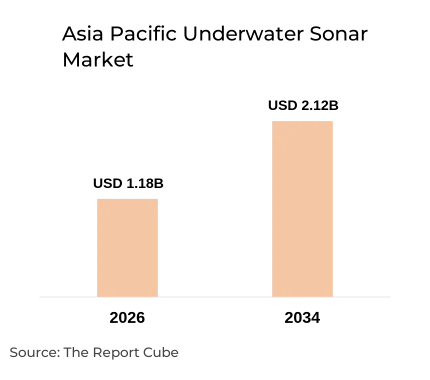
Build Your Custom Market Intelligence Report
Customize Your ReportKey Takeaways
- Asia Pacific Underwater Sonar Market is valued at USD 1.18 billion in 2026.
- The market is projected to reach USD 2.12 billion by 2034 at a CAGR of 7.60%.
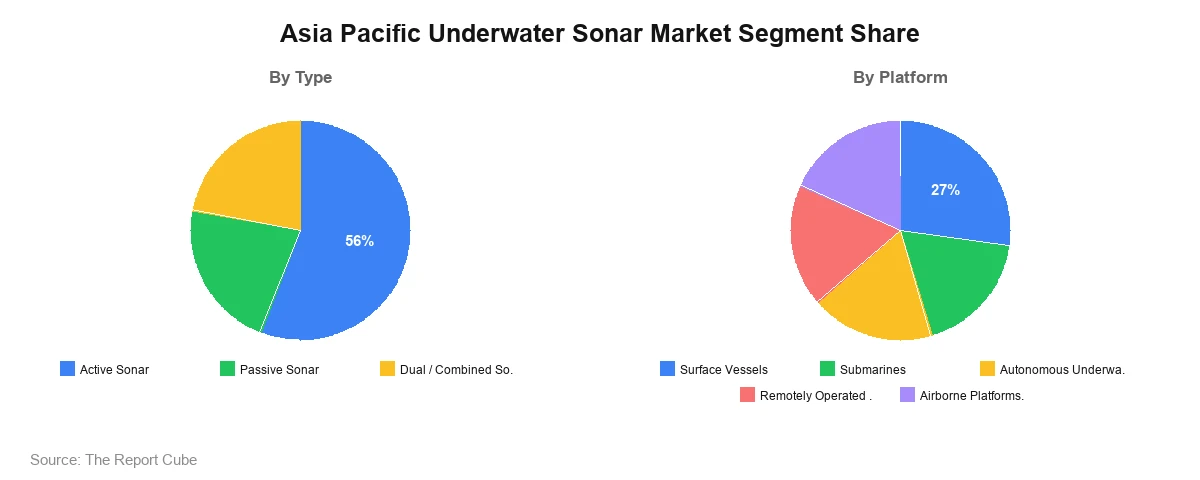
- Active sonar leads the type segment with an estimated 56% share in 2026.
- Surface vessels lead the platform segment with an estimated 27% share in 2026.
- China is the leading country market with an estimated 27% share in 2026.
- Defense and naval forces are the first-listed end use, with end-use shares pending validation.
- RTX, L3Harris, Lockheed Martin, Teledyne, Thales, and Kongsberg are among the supplied key players.
- Indigenous sonar development and sensing for uncrewed platforms are important technology themes.
Market Overview
Underwater sonar systems use sound propagation to detect, locate, classify, and track objects beneath the water surface. Active sonar transmits acoustic pulses and analyzes returning echoes, while passive sonar listens for emitted noise. Applications include anti-submarine warfare, mine countermeasures, navigation, hydrographic survey, underwater surveillance, and marine research across naval, commercial, and scientific platforms.
This Asia Pacific Underwater Sonar Market Analysis covers a regional market valued at USD 1.18 billion in 2026. Demand currently reflects naval modernization, undersea surveillance programs, and indigenous sonar development, including India’s HUMSA-NG, ABHAY, and ALTAS systems, alongside a joint Australia–India research project on submarine detection launched in July 2025.
Naval forces, commercial operators, and research institutions procure sonar for threat detection, seabed mapping, and safe navigation. Autonomous underwater vehicles, signal processing, and environmental noise management are shaping requirements. The Asia Pacific Underwater Sonar Market is projected to grow at a CAGR of 7.60% during 2026–2034, reaching USD 2.12 billion by 2034.
Asia Pacific Underwater Sonar Market Dynamics
Asia Pacific Underwater Sonar Market Growth depends on naval modernization, undersea surveillance requirements, indigenous development programs, and the adoption of uncrewed platforms. Supply conditions are shaped by technical integration demands, while competition involves global defense primes, specialist sonar manufacturers, and regional suppliers. Environmental noise considerations influence design and operating practices.
|
Factor |
Type |
Specific Impact on Market |
Magnitude |
|---|---|---|---|
|
Naval modernization and undersea surveillance |
Driver |
Sustains investment in sonar detection, surveillance, and signal-processing capability |
High |
|
Indigenous sonar development |
Opportunity |
Creates openings for domestic suppliers, component makers, and integration partners |
Medium–High |
|
Technical complexity and integration |
Challenge |
Raises engineering, testing, and platform-integration requirements |
Medium–High |
|
Sensing for uncrewed platforms |
Trend |
Encourages compact sonar and advanced processing for AUVs and UUVs |
Medium–High |
|
Underwater noise management |
Challenge |
Adds environmental considerations to sonar design and operation |
Medium |
Asia Pacific Underwater Sonar Market Growth Drivers
According to India’s Press Information Bureau, the Defence Research and Development Organisation has developed several indigenous naval sonar systems, including HUMSA-NG, ABHAY, and the Advanced Light Towed Array Sonar. These programs indicate continuing investment in undersea detection and surveillance, supporting demand for sonar hardware, processing software, and integration services across naval platforms in the region.
Australia’s Department of Defence reported that Australia and India launched a three-year joint research project in July 2025 to improve early detection and tracking of submarines and autonomous underwater vehicles. The work centers on towed-array target-motion analysis, reflecting demand for stronger acoustic signal processing and underwater surveillance capabilities in the region.
Asia Pacific Underwater Sonar Market Opportunities
According to India’s Press Information Bureau, the Indian Navy and the Defence Research and Development Organisation continue developing and testing indigenous sonar systems and related underwater-warfare technologies. This creates potential openings for domestic suppliers, component manufacturers, acoustic-processing specialists, and integration partners supporting naval sonar programs, subject to program funding and procurement decisions.
Australia’s Department of Defence states that the Australia–India research programme includes improving detection and tracking of autonomous underwater vehicles. This points to a potential opportunity for compact sonar, advanced signal processing, and underwater sensing technologies designed for uncrewed platforms, although commercial demand has not been quantified in the supplied data.
Asia Pacific Underwater Sonar Industry Challenges
Integrating acoustic sensors, processing algorithms, and platform systems requires highly specialized engineering and testing across naval and commercial platforms. The Australia–India towed-array target-motion analysis project illustrates the technical difficulty of improving submarine tracking. This is a qualitative assessment based on the cited program rather than a quantified regional market statistic.
According to the International Maritime Organization, underwater radiated noise from commercial shipping can affect marine life, including marine mammals, fish, and invertebrates, and its revised guidelines promote noise-management planning. Sonar manufacturers and marine operators must therefore consider the acoustic and environmental implications of underwater sensing and vessel operations, particularly in sensitive marine environments.
Need Specific Data, Let’s Customize the Report for You
Request CustomizationAsia Pacific Underwater Sonar Market Trends
Asia Pacific Underwater Sonar Market Trends include a stronger emphasis on indigenous defense technologies. According to India’s Press Information Bureau, indigenous naval sensor development forms part of a wider effort to expand domestic defense manufacturing and reduce reliance on imported critical systems, indicating a policy-driven shift toward locally developed sonar equipment and supply chains.
Underwater acoustic monitoring is receiving greater attention as noise management gains relevance. The International Maritime Organization notes that radiated noise from commercial shipping can harm marine life and promotes mitigation planning through revised guidelines. This broadens the need for marine acoustic measurement and environmental assessment, although it does not establish a commercial sonar forecast.
Asia Pacific Underwater Sonar Market Segment Analysis
Asia Pacific Underwater Sonar Market Share is distributed across sonar type, platform, application, and end use, reflecting different mission requirements and procurement patterns. Estimated 2026 shares are shown only where supplied. Other segments are described qualitatively pending validation.
By Type
- Active Sonar
- Passive Sonar
- Dual / Combined Sonar
Active sonar leads the type segment with an estimated 56% share in 2026, supported by its ability to transmit acoustic pulses and generate range, bearing, and classification data for anti-submarine warfare, mine countermeasures, navigation, and seabed survey tasks. Thales and Kongsberg are among the suppliers of sonar systems for these roles. Passive sonar follows, supporting covert listening and surveillance because it detects emitted noise without transmitting signals. Dual or combined systems complete the segment by integrating transmit and listening functions in one suite, as seen in Thales’ Sonar 2087, which combines active and passive arrays. Demand across all three types is driven by naval modernization, undersea surveillance programs, and growing use of uncrewed platforms, while share data for passive and combined systems has not been supplied.
By Platform
- Surface Vessels
- Submarines
- Autonomous Underwater Vehicles (AUVs)
- Remotely Operated Vehicles (ROVs) / Unmanned Underwater Vehicles (UUVs)
- Airborne Platforms
Surface vessels lead the platform segment with an estimated 27% share in 2026, reflecting the use of hull-mounted, towed-array, and variable-depth sonar on frigates, patrol vessels, and survey ships. Australia’s Hunter-class frigate program, which includes Thales’ Sonar 2087 suite, illustrates surface-platform integration. Submarines follow, relying on bow, flank, and towed sonar for navigation and target detection. AUVs and ROVs/UUVs represent growing platforms for compact sonar and signal processing, consistent with the Australia–India research on tracking autonomous vehicles. Airborne platforms, including helicopters and maritime patrol aircraft, support anti-submarine search through dipping sonar and sonobuoys. Remaining platform shares have not been supplied and require validation.
Country Analysis
|
Country |
Estimated Market Share |
Key Growth Factors |
Industry Trends |
|---|---|---|---|
|
China |
27% |
Scale of naval and maritime activity |
Domestic defense supply chains and uncrewed platforms |
|
Japan |
- |
Naval mine countermeasure programs, including the OZZ-5 UUV |
Cooperation between domestic and international sonar suppliers |
|
India |
- |
Indigenous sonar programs such as HUMSA-NG, ABHAY, and ALTAS |
Policy-driven localization and research cooperation with Australia |
|
South Korea |
- |
Naval and maritime security requirements |
Requires validation |
|
Malaysia |
- |
Maritime security and fleet requirements |
Requires validation |
|
Thailand |
- |
Maritime security and fleet requirements |
Requires validation |
|
Philippines |
- |
Maritime domain awareness requirements |
Requires validation |
|
Indonesia |
- |
Archipelagic maritime surveillance requirements |
Requires validation |
|
Vietnam |
- |
Coastal and naval security requirements |
Requires validation |
|
Rest of Asia-Pacific |
- |
Includes Australia, where Sonar 2087 is being integrated into Hunter-class frigates |
Growing focus on uncrewed underwater surveillance |
China is the leading country market in the supplied framework with an estimated 27% share in 2026. Its position reflects the scale of its naval and maritime activity, though country-specific procurement and supplier data require validation. The Asia Pacific Underwater Sonar Market therefore combines one large national market with many smaller defense and commercial demand centers.
India, Japan, and Australia, within Rest of Asia-Pacific, show verifiable programs that illustrate regional demand. India is developing indigenous sonar systems, Japan has contracted high-frequency synthetic aperture sonar for its OZZ-5 unmanned underwater vehicle, and Australia is integrating Sonar 2087 into Hunter-class frigates. Regional shares beyond China have not been supplied, so these examples are qualitative.
Market Share & Competitive Landscape
The Asia Pacific Underwater Sonar Market includes global defense primes, specialist sonar manufacturers, and marine technology suppliers. The table summarizes the supplied companies by general capability and does not represent numerical market share. Asia Pacific sales and distribution data require validation.
|
Company |
Competitive Strength |
Primary Segment Served |
|---|---|---|
|
RTX Corp |
Defense sensors, combat systems, and airborne and naval electronics |
Naval and airborne platforms |
|
L3Harris Technologies Inc |
Maritime sensors, undersea systems, and unmanned maritime technology |
Naval platforms and unmanned vehicles |
|
Lockheed Martin Corp |
Naval combat system integration and anti-submarine helicopter platforms |
Surface vessels and airborne platforms |
|
Teledyne Technologies Inc |
Marine sonar, imaging, and instrumentation |
Hydrographic survey, ROVs, and AUVs |
|
Thales Group |
Towed-array, hull-mounted, and synthetic aperture sonar |
Anti-submarine warfare and mine countermeasures |
|
Kongsberg Gruppen ASA |
Anti-submarine and diver detection sonar, HUGIN AUVs, and survey systems |
Naval, commercial, and survey platforms |
|
Saab AB |
Submarine, surface combat, and underwater vehicle systems |
Submarines and ROVs |
|
ATLAS ELEKTRONIK |
Naval sonar, unmanned underwater vehicles, and mine countermeasure systems |
Naval and mine countermeasure platforms |
|
Sonardyne International |
Acoustic positioning, navigation, and subsea sensing |
Offshore, ROV, and AUV operations |
|
Norbit |
Wideband multibeam sonar |
Hydrographic survey and seabed mapping |
Key Companies in the Asia Pacific Underwater Sonar Market
Thales Group: Thales is headquartered in Paris, France, and its anti-submarine warfare systems are in service with more than 50 navies. In November 2025, Australia’s Department of Defence reported factory acceptance testing of Sonar 2087 handling systems for Hunter-class frigates, with delivery scheduled for early 2026. Strengths include towed-array and synthetic aperture sonar.
Kongsberg Gruppen ASA: Kongsberg Gruppen is headquartered in Kongsberg, Norway, with roots dating to 1814. In February 2026, Kongsberg Discovery announced an upgraded Kongsberg Listen electromagnetic sensor, already operated on HUGIN autonomous underwater vehicles. Strengths include anti-submarine and diver detection sonar. A November 2025 agreement with Leidos Australia explores uncrewed vessel integration.
Recent Developments
|
Year / Month |
Company |
Development |
|---|---|---|
|
July 2025 |
Australian Department of Defence and Indian partners |
Launched a three-year joint research project to improve early detection and tracking of submarines and autonomous underwater vehicles through towed-array target-motion analysis. |
|
September 2025 |
Thales and BAE Systems |
Signed an MoU at DSEI UK 2025 on the SSN AUKUS sonar suite, with BAE Systems proposing Thales as main sonar design authority and integrator. This is a proposed role, not a completed award. |
|
November 2025 |
Thales |
Completed factory acceptance testing in Brest, France, of towed body and towed array handling systems for the Sonar 2087 suite on Australia’s Hunter-class frigates. |
|
December 2025 |
Thales |
Revealed Sonar 76Nano, a miniaturized AI-enabled sonar for medium, large, and extra-large unmanned underwater vehicles. |
|
February 2026 |
Kongsberg Discovery |
Announced an upgraded Kongsberg Listen passive electromagnetic sensor with enhanced hardware, software, and visualization. |
Market Future Outlook
The Asia Pacific Underwater Sonar Market Forecast indicates expansion from USD 1.18 billion in 2026 to USD 2.12 billion by 2034 at a CAGR of 7.60%, based on supplied estimates. Growth is expected to depend on naval modernization, indigenous sonar programs, submarine detection research, and adoption of sensing technologies for uncrewed platforms. These projections are assumptions rather than guaranteed outcomes.
Technology investment is likely to focus on towed-array processing, synthetic aperture imaging, compact sonar for autonomous vehicles, and passive acoustic sensing. Competition may involve global defense primes, specialist sonar manufacturers, and regional suppliers pursuing local manufacturing partnerships. Risks include integration complexity, environmental noise requirements, program funding decisions, and procurement timelines, and verified regional market evidence beyond the supplied estimates remains limited.
Asia Pacific Underwater Sonar Market Report Coverage
This Asia Pacific Underwater Sonar Market Report summarizes the supplied valuation, forecast assumptions, segmentation, regional framework, and competitive ecosystem.
|
Parameter |
Details |
|---|---|
|
Market Name |
Asia Pacific Underwater Sonar Market |
|
Market Size 2026 |
USD 1.18 billion |
|
Market Size 2034 |
USD 2.12 billion |
|
Forecast Period |
2026–2034 |
|
CAGR |
7.60% |
|
Base Year |
2026 |
|
Historical Years |
2021-2025 |
|
Forecast Years |
2026–2034 |
|
Segments Covered |
By Type; By Platform; By Application; By End Use |
|
Regions Covered |
Japan, Malaysia, India, South Korea, Thailand, China, Philippines, Indonesia, Vietnam, Rest of Asia-Pacific |
|
Key Companies |
RTX Corp, L3Harris Technologies Inc, Lockheed Martin Corp, Teledyne Technologies Inc, Thales Group, Kongsberg Gruppen ASA, Saab AB, ATLAS ELEKTRONIK, Sonardyne International, Norbit |
|
Customization |
Available as per client requirements |
Why Choose This Asia Pacific Underwater Sonar Market Report?
- Covers sonar demand across naval, commercial maritime, offshore, fisheries, and research channels.
- Presents the supplied 2026 valuation, 2034 forecast, and 7.60% CAGR with clear assumptions.
- Segments the market by type, platform, application, and end use for detailed planning.
- Provides a ten-country regional framework, including China’s estimated 27% share in 2026.
- Profiles supplied global defense, sonar, and marine technology companies by capability.
- Highlights indigenous development, uncrewed platform sensing, and underwater noise management trends.
- Supports product planning, partnership evaluation, and market-entry assessment without guaranteeing outcomes.
Table of Contents
- Introduction
- Objective of the Study
- Product Definition
- Market Segmentation
- Study Variables
- Research Methodology
- Secondary Data Points
- Companies Interviewed
- Primary Data Points
- Breakdown of Primary Interviews
- Secondary Data Points
- Executive Summary
- Market Dynamics
- Drivers
- Challenges
- Opportunity Assessment
- Recent Trends and Developments
- Policy and Regulatory Landscape
- Asia Pacific Underwater Sonar Market Overview and Forecast Analysis (2021-2034)
- Market Size, By Value, By Growth Rate (CAGR/USD Billions)
- Demand – Supply Trends
- Market Share, By Type
- Active Sonar
- Passive Sonar
- Dual / Combined Sonar
- Market Share, By Platform
- Surface Vessels
- Submarines
- Autonomous Underwater Vehicles (AUVs)
- Remotely Operated Vehicles (ROVs) / Unmanned Underwater Vehicles (UUVs)
- Airborne Platforms
- Market Share, By Application
- Anti-Submarine Warfare (ASW)
- Mine Countermeasure (MCM)
- Navigation & Collision Avoidance
- Seabed Mapping / Hydrographic Survey
- Underwater Surveillance & Security
- Others
- Market Share, By End Use
- Defense & Naval Forces
- Commercial Maritime & Shipping
- Oil & Gas Industry
- Fisheries & Aquaculture
- Oceanographic & Marine Research Institutes
- Others
- Market Share, By Country
- Japan
- Malaysia
- India
- South Korea
- Thailand
- China
- Philippines
- Indonesia
- Vietnam
- Rest of Asia-Pacific
- Market Share, By Competitors
- Competition Characteristics
- Revenue Shares
- Active Sonar Asia Pacific Underwater Sonar Market Overview, 2021-2034F
- By Value (USD Million)
- By Platform – Market Size & Forecast 2021-2034, USD Million
- Surface Vessels
- Submarines
- Autonomous Underwater Vehicles (AUVs)
- Remotely Operated Vehicles (ROVs) / Unmanned Underwater Vehicles (UUVs)
- Airborne Platforms
- Passive Sonar Asia Pacific Underwater Sonar Market Overview, 2021-2034F
- By Value (USD Million)
- By Platform – Market Size & Forecast 2021-2034, USD Million
- Surface Vessels
- Submarines
- Autonomous Underwater Vehicles (AUVs)
- Remotely Operated Vehicles (ROVs) / Unmanned Underwater Vehicles (UUVs)
- Airborne Platforms
- Dual / Combined Sonar Asia Pacific Underwater Sonar Market Overview, 2021-2034F
- By Value (USD Million)
- By Platform – Market Size & Forecast 2021-2034, USD Million
- Surface Vessels
- Submarines
- Autonomous Underwater Vehicles (AUVs)
- Remotely Operated Vehicles (ROVs) / Unmanned Underwater Vehicles (UUVs)
- Airborne Platforms
- Competitive Outlook (Company Profile – Partial List)
- RTX Corp
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- L3Harris Technologies Inc
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Lockheed Martin Corp
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Teledyne Technologies Inc
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Thales Group
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Kongsberg Gruppen ASA
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Saab AB ADR
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- TLAS ELEKTRONIK
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Sonardyne International
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Norbit
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- RTX Corp
- Contact Us & Disclaimer
Top Key Players & Market Share Outlook
- RTX Corp
- L3Harris Technologies Inc
- Lockheed Martin Corp
- Teledyne Technologies Inc
- Thales Group
- Kongsberg Gruppen ASA
- Saab AB ADR
- TLAS ELEKTRONIK
- Sonardyne International
- Norbit
Frequently Asked Questions