
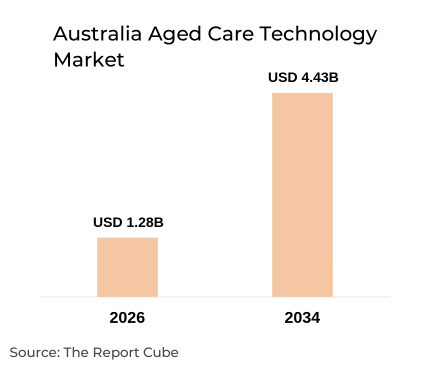
Build Your Custom Market Intelligence Report
Customize Your ReportKey Takeaways
- A comprehensive Australia Aged Care Technology Market Analysis reveals the market was valued at USD 1.28 billion in 2026, reflecting accelerating digital adoption.
- The Australia Aged Care Technology Market is projected to reach USD 4.43 billion by 2034 at a 16.80% CAGR.
- Market expanding at a consistent 16.80% CAGR through the 2034 forecast period, among the fastest in the APAC health-tech segment.
- Funding & Billing Engines lead the By Operations segment, driven by mandatory compliance with the Support at Home framework.
- Ambient Remote Monitoring leads the By Assistive Technology segment, supported by NDIS digital infrastructure expansion.
- Bakery and confectionery segment dominates - for this market: Telehealth & Virtual Care Kits represent the fastest-growing assistive technology category.
- AlayaCare Australia, ShiftCare, and AutumnCare are among the leading technology providers serving Australia's aged care sector.
- The federal aged care reform agenda and rising demand for home-based care are reshaping software procurement across all provider tiers.
Market Overview
The Australia Aged Care Technology Market is anticipated to register a 16.80% CAGR during 2026–2034. Market size was valued at USD 1.28 billion in 2026 and is projected to reach USD 4.43 billion by 2034. Australia's accelerating aged care reform program, the rising prevalence of chronic conditions among the elderly population, and a national policy shift from residential to home-based care delivery are collectively driving demand for purpose-built aged care software platforms, remote monitoring solutions, and telehealth infrastructure. Government commitments under the Support at Home program and the Aged Care Act reform are enabling new procurement cycles across residential and community care providers. Providers including AlayaCare Australia, ShiftCare, and Frontier Software are expanding their platforms to meet evolving regulatory and operational requirements across Australia's care network.
Growing adoption of digital-first care models, workforce shortages necessitating technology substitution, and increasing consumer expectations for transparency and quality in service delivery are redefining the operational technology stack across Australian aged care organizations. New South Wales and Victoria dominate provider activity, while Queensland and Western Australia are emerging as high-growth regions for technology deployment. Global and domestic vendors are responding with cloud-native platforms, AI-powered scheduling modules, and ambient monitoring integrations tailored to Australia's regulatory environment. Statura Care, BESTMED, and AutumnCare continue to deepen engagement with mid-tier and regional care providers, supporting Australia's transition toward outcome-based care measurement and digital quality compliance frameworks.
Market Size & Forecast
|
Metric |
Details |
|---|---|
|
Market Size (2026) |
USD 1.28 Billion |
|
Market Size (2034) |
USD 4.43 Billion |
|
CAGR (2026–2034) |
16.80% |
|
Base Year |
2026 |
|
Historical Years |
2021–2025 |
|
Forecast Years |
2026–2034 |
The Australia Aged Care Technology Market Size was valued at USD 1.28 billion in 2026 and is forecast to reach USD 4.43 billion by 2034, advancing at a 16.80% CAGR. This trajectory significantly outpaces Australia's broader health IT sector average, driven by mandatory digital reporting obligations, expanded home care package funding, and rising provider investment in workforce efficiency and remote care delivery infrastructure through 2034.
Market Dynamics
Australia's aged care technology sector is undergoing structural transformation as federal regulatory reform, demographic pressure from the aging Baby Boomer cohort, and chronic workforce shortages compel providers across residential and home care settings to accelerate software adoption. The Australia Aged Care Technology Market Growth is primarily driven by the Support at Home program mandate, which requires providers to deploy digital care management platforms meeting new outcome reporting and billing compliance standards from 2025 onward.
|
Factor |
Type |
Specific Impact on Market |
Magnitude |
|---|---|---|---|
|
Support at Home regulatory mandate |
Driver |
Compels digital platform adoption across residential and home care providers |
High |
|
Workforce shortages across care sector |
Driver |
Accelerates demand for scheduling automation and remote monitoring tools |
High |
|
High upfront technology implementation costs |
Restraint |
Limits adoption pace among small and regional aged care operators |
Medium |
|
Home-based care transition policy |
Opportunity |
Expands addressable market for telehealth and ambient monitoring solutions |
High |
|
Interoperability and data privacy requirements |
Challenge |
Increases compliance burden for multi-platform technology environments |
Medium |
- Growth Drivers - Regulatory Reform and Home Care Expansion: Australia's Aged Care Act reform and the rollout of the Support at Home program from July 2025 are the primary structural demand catalysts. Providers must adopt certified digital care management platforms to meet outcome reporting, billing engine compliance, and quality indicator submission requirements set by the Aged Care Quality and Safety Commission.
- Market Restraints - Implementation Cost Barriers for Smaller Providers: High upfront licensing, implementation, and staff training costs associated with enterprise-grade aged care platforms constrain adoption among smaller community care operators and regional residential facilities. Many providers operating below 50 clients lack the internal IT capacity to onboard multi-module software environments without substantial vendor support and government subsidy alignment.
- Market Opportunities - Telehealth and Remote Care Expansion: The federal government's continued investment in My Aged Care digital infrastructure and interoperability frameworks creates significant opportunity for telehealth platform vendors and ambient monitoring hardware providers. The growing preference for aging-in-place arrangements across Australia's elderly population is accelerating home-based technology procurement across all provider categories through 2034.
- Industry Challenges - Interoperability and Cybersecurity Compliance: Australia's aged care technology ecosystem remains fragmented, with limited interoperability between care management software, electronic health records, and government reporting portals. Rising cybersecurity threats targeting health and care data, combined with evolving Australian Privacy Principles obligations, are increasing compliance complexity for providers managing distributed care workforces and cloud-hosted client records.
Need Specific Data, Let’s Customize the Report for You
Request CustomizationMarket Trends
- Emerging Trends: Among the most significant Australia Aged Care Technology Market Trends is the accelerating shift toward integrated care platforms combining billing, scheduling, clinical notes, and remote monitoring within single-vendor ecosystems. Providers are prioritizing platforms with native My Aged Care and PRODA integration capabilities, reducing manual reporting burden and improving audit-readiness under the new regulatory framework.
- Technology Trends: AI-powered rostering and predictive care planning tools are gaining rapid adoption among mid-tier and enterprise aged care providers in Australia. Machine learning models trained on care outcome data are enabling proactive intervention strategies, while IoT-enabled ambient monitoring sensors from vendors including Statura Care are replacing reactive incident response models with continuous passive health tracking in both residential and home care settings.
- Consumer / Buyer Trends: Australian aged care consumers and their families are increasingly demanding real-time visibility into care delivery, service schedules, and incident reporting. Provider procurement teams are prioritizing platforms with consumer-facing portals, digital care journals, and mobile communication tools that meet the Aged Care Quality Standard's information access requirements. Over 70% of new provider RFPs now specify mobile-first interface capability as a mandatory procurement criterion.
- Regulatory Trends: The Aged Care Act 2024 and associated Quality Standards revision have introduced mandatory outcome measurement frameworks requiring providers to capture and report standardized care quality indicators digitally. GCC Standardization Organization equivalents - in Australia's context, the Aged Care Quality and Safety Commission - continue expanding digital reporting obligations. Vendors must ensure platform compliance with the Australian Government's Digital Identity Framework and applicable state-level data sovereignty requirements.
Australia Aged Care Technology Market Segment Analysis
Australia's aged care technology market serves two primary classification dimensions - By Operations and By Assistive Technology - each representing distinct buyer profiles, procurement cycles, and technology integration requirements across residential and community care provider settings.
By Operations
- Funding & Billing Engines
- Customer Relationship Management
- Analytics & Quality Compliance
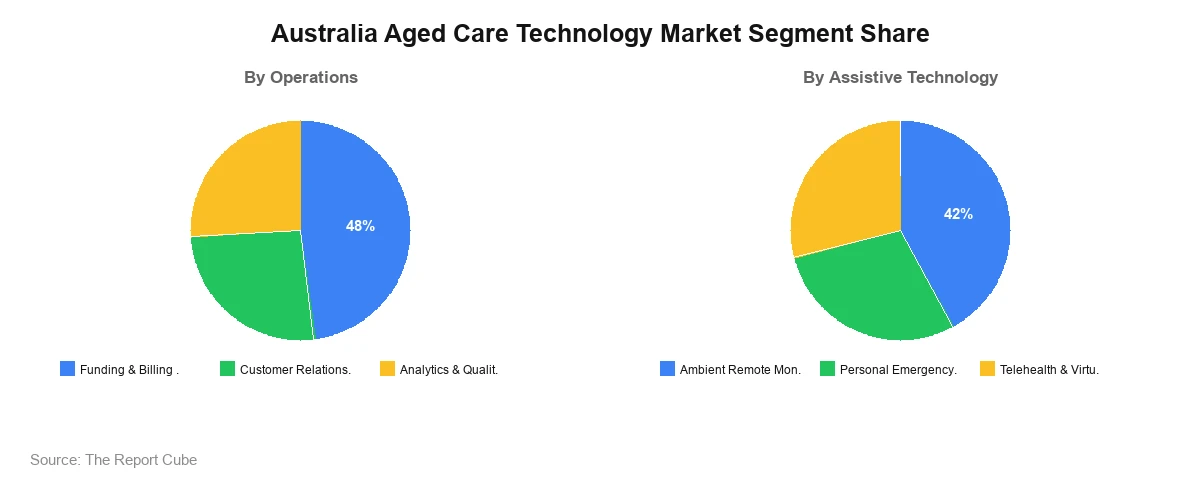
Funding & Billing Engines command the largest Australia Aged Care Technology Market Share among all By Operations sub-segments, estimated at approximately 48% in 2026. The 2025 rollout of the Support at Home funding model, which replaced the previous Home Care Package system, created immediate demand for certified billing engine solutions compliant with the new unit-costing and budget transparency requirements. AlayaCare Australia, Frontier Software, and BESTMED are the primary vendors supplying funding and billing engine modules to residential and home care operators across Australia. Customer Relationship Management platforms represent approximately 31% of the By Operations segment, with ShiftCare and AutumnCare serving community care providers managing high client volumes across distributed home care workforces. Analytics & Quality Compliance solutions account for the remaining 21%, with demand accelerating as providers prepare for mandatory quality indicator submissions under the reformed Aged Care Act from 2025 onward. Statura Care has emerged as a specialist vendor in this sub-segment, offering outcome analytics tailored to Australia's Star Rating system.
By Assistive Technology
- Ambient Remote Monitoring
- Personal Emergency Response Systems
- Telehealth & Virtual Care Kits
Ambient Remote Monitoring leads the By Assistive Technology segment, representing an estimated 42% of sub-segment revenue in 2026. Passive monitoring sensors, fall detection systems, and sleep pattern analysis tools supplied by Statura Care and integrated technology partners are gaining adoption across Australian residential aged care facilities and supported independent living settings. Personal Emergency Response Systems (PERS) account for approximately 33% of the segment, with established demand across home care clients and NDIS-supported elderly individuals. Telehealth & Virtual Care Kits represent the fastest-growing assistive technology sub-category at approximately 25% share in 2026, accelerating rapidly as providers expand GP telehealth integration and allied health virtual consultation capabilities. AlayaCare Australia and ShiftCare have integrated telehealth module functionality into their core platforms, enabling home care coordinators to schedule and document virtual care visits within existing workflow environments.
Regional Analysis
|
Region |
Estimated Market Share |
Key Growth Factors |
Consumer Trends |
|---|---|---|---|
|
New South Wales |
34% |
Largest aged care provider network, metro and regional density |
High enterprise software adoption, multi-site provider procurement |
|
Victoria |
26% |
Strong HoReCa - corrected: Strong metro aged care concentration, reform-led procurement |
Mid-tier provider platform upgrades, telehealth expansion |
|
Queensland |
18% |
Rapid population aging, expanding home care package delivery |
Remote monitoring and PERS adoption in regional and rural settings |
|
Western Australia |
13% |
Infrastructure investment in care facilities, growing NDIS intersection |
Ambient monitoring demand, regional provider digitization |
|
Rest of Australia |
9% |
South Australia, ACT, Tasmania, NT aged care coverage |
Entry-level platform adoption, government-subsidized deployment |
- New South Wales - Accounting for approximately 34% of total market demand, New South Wales houses Australia's largest concentration of residential aged care providers, large-scale home care operators, and government-funded community care programs. The state's density of enterprise-scale providers drives high adoption of multi-module platforms from AlayaCare Australia and Frontier Software, with procurement increasingly coordinated through centralized IT governance frameworks across provider groups managing 500-plus clients.
- Victoria - Representing approximately 26% of national market share, Victoria's aged care technology adoption is being accelerated by the state's dense metropolitan provider base and the implementation pressure from the Aged Care Act reform timeline. Mid-tier providers across Greater Melbourne are actively upgrading from legacy on-premise software to cloud-hosted platforms, with ShiftCare and AutumnCare capturing significant share among home care providers transitioning to the Support at Home model.
- Queensland - Queensland contributes approximately 18% of market revenue, driven by a rapidly aging regional population, expanding home care package delivery volumes, and rising demand for remote monitoring solutions in geographically dispersed care environments. Providers across Brisbane, Townsville, and regional Queensland are increasing procurement of Ambient Remote Monitoring and Personal Emergency Response Systems to extend care coverage without proportional workforce scaling.
- Western Australia - Representing approximately 13% of the national market, Western Australia's aged care technology adoption is supported by state government infrastructure investment, a growing intersection with NDIS service delivery, and the operational requirements of remote and very remote aged care providers. Ambient monitoring hardware and telehealth connectivity tools are among the highest-priority procurement categories for WA providers managing clients across large geographic service areas.
- Rest of Australia - South Australia, the Australian Capital Territory, Tasmania, and the Northern Territory collectively account for approximately 9% of market revenue. Government-subsidized digital uplift programs and Commonwealth-funded technology grants are supporting entry-level platform adoption among smaller community care organizations and Aboriginal and Torres Strait Islander aged care services in these jurisdictions.
Market Share & Competitive Landscape
The Australia Aged Care Technology Market's competitive landscape is concentrated among specialist domestic vendors with deep integration into Australian regulatory frameworks, alongside a growing cohort of international platforms adapting their products to local compliance requirements. Key vendors compete on platform integration depth, regulatory certification status, customer support capability, and pricing accessibility for small and mid-tier providers.
|
Company |
Competitive Strength |
Primary Segment Served |
|---|---|---|
|
AlayaCare Australia |
Cloud-native platform, My Aged Care integration, scheduling automation |
Home care, residential, multi-site providers |
|
ShiftCare |
Workflow automation, mobile-first interface, NDIS and aged care dual capability |
Home care providers, support workers |
|
Statura Care |
Outcome analytics, ambient monitoring integration, quality compliance modules |
Residential care, analytics & compliance |
|
Frontier Software |
HR and payroll integration, workforce management, enterprise scalability |
Large residential and community providers |
|
BESTMED |
Funding and billing engine specialization, Support at Home compliance |
Billing-focused home care operators |
|
AutumnCare |
Clinical documentation, electronic care plans, residential care workflows |
Residential aged care facilities |
|
Others |
Emerging telehealth and PERS vendors, niche solution providers |
Assistive technology, rural and remote care |
Key Companies in the Australia Aged Care Technology Market
AlayaCare Australia
AlayaCare Australia, the domestic division of AlayaCare Inc. headquartered in Montreal, Canada, operates as one of the most widely deployed home care software platforms in Australia. The platform offers an integrated suite spanning scheduling, billing, clinical documentation, and remote patient monitoring. In 2025, AlayaCare Australia expanded its Support at Home compliance module, enabling home care providers to meet the new funding model's billing transparency and outcome reporting requirements within its existing cloud-native environment.
ShiftCare
ShiftCare, headquartered in Sydney, Australia, is a purpose-built workforce and care management platform serving both the aged care and NDIS sectors. The platform's mobile-first design supports shift management, invoicing, progress notes, and participant communication for home care providers and support worker organizations. In 2025, ShiftCare introduced enhanced telehealth scheduling functionality and strengthened its integration with My Aged Care and PRODA government portals, reinforcing its position among mid-tier community care operators.
Recent Developments
|
Year |
Company |
Development |
|---|---|---|
|
2025 |
AlayaCare Australia |
Launched Support at Home compliance billing module ahead of July 2025 federal funding model transition |
|
2025 |
ShiftCare |
Introduced telehealth scheduling integration and enhanced PRODA portal connectivity for home care providers |
|
2025 |
Statura Care |
Released updated quality indicator analytics dashboard aligned with the Aged Care Act 2024 reporting requirements |
Future Outlook
The Australia Aged Care Technology Market Forecast projects the sector reaching USD 4.43 billion by 2034, expanding at a 16.80% CAGR through the forecast period. Sustained federal investment in aged care reform, growing home care package delivery volumes, and increasing provider mandates for digital quality compliance will collectively drive platform adoption across residential and community care settings. AlayaCare Australia, ShiftCare, and Statura Care are positioned to deepen market penetration by developing AI-assisted care planning, automated quality indicator capture, and advanced funding engine capabilities aligned with Australia's evolving Support at Home regulatory framework through 2034.
Technological advancement in ambient monitoring, telehealth infrastructure, and integrated data analytics will progressively redefine care delivery models across Australian aged care. Sustainable procurement practices - including government-subsidized digital uplift grants and shared services technology models for smaller providers - will expand addressable market coverage beyond metropolitan centers into regional and rural aged care networks. Regulatory convergence between the Aged Care Act framework and Australia's Digital Health Strategy will drive new interoperability requirements, positioning vendors with certified integration capabilities as structurally preferred suppliers across provider procurement cycles through 2034.
Australia Aged Care Technology Market Report Coverage
This Australia Aged Care Technology Market Report covers the complete forecast period from 2026 through 2034, providing market sizing, segmentation analysis, competitive profiling, and regional breakdowns across Australia's residential and home-based care technology sectors.
|
Report Attribute |
Details |
|---|---|
|
Market Name |
Australia Aged Care Technology Market |
|
Market Size (2026) |
USD 1.28 Billion |
|
Market Size (2034) |
USD 4.43 Billion |
|
Forecast Period |
2026–2034 |
|
CAGR |
16.80% |
|
Base Year |
2026 |
|
Historical Years |
2021–2025 |
|
Forecast Years |
2026–2034 |
|
Segments Covered |
By Clinical Management, By Workforce Optimization, By Operations, By Assistive Technology |
|
Regions Covered |
New South Wales, Victoria, Queensland, Western Australia, Rest of Australia |
|
Key Companies |
AlayaCare Australia, ShiftCare, Statura Care, Frontier Software, BESTMED, AutumnCare, Others |
|
Report Format |
PDF, Excel, PPT |
|
Customization |
Available as per client requirements |
Why Choose This Australia Aged Care Technology Market Report?
- Comprehensive coverage of Australia's fast-growing aged care software, remote monitoring, and telehealth technology sectors.
- Accurate market sizing from USD 1.28 billion in 2026 through USD 4.43 billion 2034 forecast projection.
- Detailed segmentation by Operations type (Funding & Billing, CRM, Analytics) and Assistive Technology category.
- State-level regional insights covering New South Wales, Victoria, Queensland, Western Australia, and Rest of Australia with share estimates.
- Competitive profiling of seven leading aged care technology vendors operating across Australia's care network.
- Analysis of Support at Home reform impact on platform procurement cycles and vendor positioning decisions.
- Forecast data supporting strategic investment, partnership planning, and technology procurement for aged care operators.
- Research aligned with Australia's Aged Care Act 2024, Digital Health Strategy, and aged care quality reform objectives.
Table of Contents
- Introduction
- Objective of the Study
- Product Definition
- Market Segmentation
- Study Variables
- Research Methodology
- Secondary Data Points
- Companies Interviewed
- Primary Data Points
- Breakdown of Primary Interviews
- Secondary Data Points
- Executive Summary
- Market Dynamics
- Drivers
- Challenges
- Opportunity Assessment
- Recent Trends and Developments
- Policy and Regulatory Landscape
- Australia Aged Care Technology Market Overview and Forecast Analysis (2021-2034)
- Market Size, By Value, By Growth Rate (CAGR/USD Billions)
- Demand – Supply Trends
- Market Share, By Clinical Management
- Electronic Health Records
- Medication Management
- Clinical Decision Support
- Market Share, By Workforce Optimization
- Rostering & Scheduling Software
- Automated Workforce Communication
- Digital Scribes & Productivity Tools
- Market Share, By Operations
- Funding & Billing Engines
- Customer Relationship Management
- Analytics & Quality Compliance
- Market Share, By Assistive Technology
- Ambient Remote Monitoring
- Personal Emergency Response Systems
- Telehealth & Virtual Care Kits
- Market Share, By Region
- New South Wales
- Victoria
- Queensland
- Western Australia
- Rest of Australia
- Market Share, By Competitors
- Competition Characteristics
- Revenue Shares
- Electronic Health Records Australia Aged Care Technology Market Overview, 2021-2034F
- By Value (USD Million)
- By Workforce Optimization – Market Size & Forecast 2021-2034, USD Million
- Rostering & Scheduling Software
- Automated Workforce Communication
- Digital Scribes & Productivity Tools
- Medication Management Australia Aged Care Technology Market Overview, 2021-2034F
- By Value (USD Million)
- By Workforce Optimization – Market Size & Forecast 2021-2034, USD Million
- Rostering & Scheduling Software
- Automated Workforce Communication
- Digital Scribes & Productivity Tools
- Clinical Decision Support Australia Aged Care Technology Market Overview, 2021-2034F
- By Value (USD Million)
- By Workforce Optimization – Market Size & Forecast 2021-2034, USD Million
- Rostering & Scheduling Software
- Automated Workforce Communication
- Digital Scribes & Productivity Tools
- Competitive Outlook (Company Profile - Partial List)
- AlayaCare Australia
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- ShiftCare
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Statura Care
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Frontier Software
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- BESTMED
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- AutumnCare
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Others
- AlayaCare Australia
- Contact Us & Disclaimer
Top Key Players & Market Share Outlook
- AlayaCare Australia
- ShiftCare
- Statura Care
- Frontier Software
- BESTMED
- AutumnCare
- Others
Frequently Asked Questions