
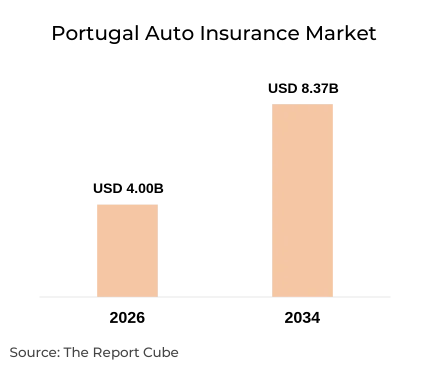
Build Your Custom Market Intelligence Report
Customize Your ReportKey Takeaways
- Portugal auto insurance market valued at USD 4.00 billion in 2026, reflecting robust premium growth.
- Industry projected to reach USD 8.37 billion by 2034 at 9.67% CAGR.
- Market size is expected to more than double between 2026 and 2034.
- New vehicles lead the vehicle age segment, driven by comprehensive coverage adoption.
- Personal applications dominate Portugal's motor insurance demand landscape significantly.
- Commercial fleets remain the fastest-growing end-user segment across logistics and tourism channels.
- Fidelidade, Ageas Portugal, and Generali lead motor insurance underwriting in Portugal.
- Digital claims platforms and telematics-based pricing are reshaping motor insurance distribution.
Market Overview
This Portugal Auto Insurance Market Analysis values the industry at USD 4.00 billion in 2026, advancing at a 9.67% CAGR toward USD 8.37 billion by 2034. Mandatory third-party liability rules, ASF supervision, and rising premiums support demand, while Fidelidade and Ageas Portugal anchor supply.
Tourism-driven rental fleets and growing commercial logistics activity expand policy volumes, while Portugal's position within the European Union single insurance market supports cross-border cover. Generali Tranquilidade, Allianz Portugal, and Zurich Portugal are expanding digital sales channels and mobility-focused product offerings.
Market Size & Forecast
|
Metric |
Details |
|---|---|
|
Market Size (2026) |
USD 4.00 Billion |
|
Market Size (2034) |
USD 8.37 Billion |
|
CAGR (2026–2034) |
9.67% |
|
Base Year |
2026 |
|
Historical Years |
2021–2025 |
|
Forecast Years |
2026–2034 |
The Portugal Auto Insurance Market Size reached USD 4.00 billion in 2026 and is projected to hit USD 8.37 billion by 2034, expanding at a 9.67% CAGR. Compulsory third-party liability cover, rising average premiums, an ageing vehicle fleet, and accelerating digital policy distribution differentiate Portugal's growth from broader European motor insurance averages.
Market Dynamics
The Portugal Auto Insurance Market Growth outlook reflects mandatory liability coverage, rising vehicle registrations, and higher repair and claims costs that lift average premiums. Digital distribution, expanding commercial fleets, and evolving ASF supervision are reinforcing competition among leading insurers, brokers, and bancassurance channels across Portuguese personal and commercial motor portfolios.
|
Factor |
Type |
Specific Impact on Market |
Magnitude |
|---|---|---|---|
|
Mandatory third-party liability requirement |
Driver |
Sustains universal baseline policy volumes across the national vehicle parc |
High |
|
Rising claims and repair costs |
Driver |
Lifts average premiums and comprehensive coverage pricing across insurers |
High |
|
Digital and telematics-based distribution |
Opportunity |
Expands online quotation, direct sales, and usage-based product development |
High |
|
Ageing vehicle fleet |
Restraint |
Keeps many owners on basic third-party policies, limiting coverage upgrades |
Medium |
|
Claims inflation and price competition |
Challenge |
Compresses underwriting margins across personal motor insurance portfolios |
Medium |
|
Mobile-first claims processing |
Trend |
Accelerates remote damage assessment and shortens claim settlement timelines |
Medium |
- Growth Drivers - Mandatory Coverage and Premium Inflation: Compulsory third-party liability makes motor cover a universal purchase, while repair cost inflation and vehicle technology complexity lift average premiums. Fidelidade, Ageas Portugal, and Generali Tranquilidade benefit from large existing portfolios and strong broker, agent, and bancassurance distribution.
- Market Restraints - Ageing Fleet and Price Sensitivity: An ageing vehicle fleet keeps many owners on basic third-party policies, limiting comprehensive coverage uptake. Intense price competition and rising claims frequency pressure combined ratios, while price-sensitive consumers frequently switch insurers at renewal, weakening customer retention across personal motor portfolios.
- Market Opportunities: Telematics-based pricing, embedded insurance at vehicle sale, and direct online channels open new revenue pools. Electric vehicle adoption and expanding commercial fleet programs support specialized product development, giving Allianz Portugal, Zurich Portugal, and Mapfre Seguros Portugal room to differentiate.
- Industry Challenges: Claims inflation from parts, labor, and vehicle electronics costs erodes underwriting margins. Fraud management, evolving ASF conduct requirements, and climate-related weather claims add operating complexity, while insurers must invest continuously in data analytics and digital claims platforms to maintain competitiveness.
Need Specific Data, Let’s Customize the Report for You
Request CustomizationMarket Trends
- Emerging Trends: Among the defining Portugal Auto Insurance Market Trends, usage-based policies, bundled mobility services, and embedded insurance at vehicle sale are gaining traction as insurers pursue younger, digitally native policyholders.
- Technology Trends: Augmented reality damage assessment, mobile claims applications, and machine learning fraud detection are shortening settlement cycles. Fidelidade's mobile application surpassed 1.6 million registered users by mid-2024, underscoring rapid policyholder adoption of digital servicing.
- Consumer / Buyer Trends: Policyholders increasingly compare quotes online, favoring transparent pricing, flexible deductibles, and fast digital claims. Younger drivers and fleet managers seek modular coverage, roadside assistance, and replacement vehicle benefits rather than basic mandatory liability alone.
- Regulatory Trends: The Insurance and Pension Funds Supervisory Authority (ASF) continues strengthening conduct, solvency, and consumer protection oversight under Solvency II. EU motor insurance directive alignment and data privacy rules shape product disclosure, pricing, and claims handling.
Portugal Auto Insurance Market Segment Analysis
The Portugal Auto Insurance Market divides into distinct vehicle age and application categories, each shaped by coverage preferences, premium levels, and distribution channels. New and used vehicle owners, together with personal and commercial policyholders, follow different purchasing patterns across insurers, agents, brokers, and bancassurance networks.
By Vehicle Age
- New Vehicles
- Used Vehicles
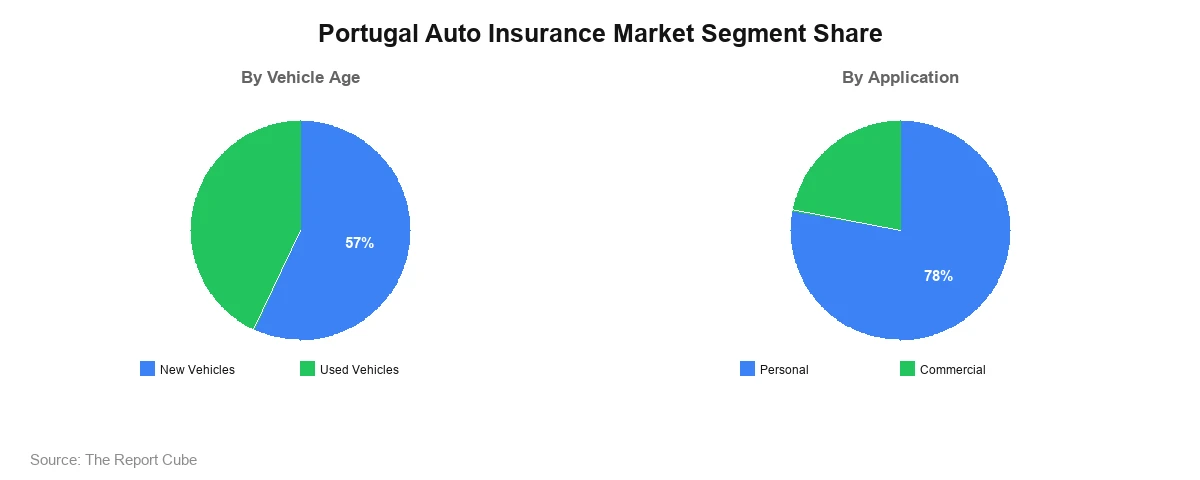
New vehicles lead the By Vehicle Age segment with an estimated 57% share in 2026, supported by comprehensive and zero-deductible policies from Fidelidade, Allianz Portugal, and Zurich Portugal. Used vehicles hold approximately 43%, served by Ageas Portugal, Generali Tranquilidade, and Mapfre Seguros Portugal through third-party and extended cover.
By Application
- Personal
- Commercial
Personal applications command the largest Portugal Auto Insurance Market Share at an estimated 78% in 2026, driven by individual motorists buying policies through Fidelidade, Ageas Portugal, and Generali Tranquilidade. Commercial applications, at roughly 22%, are the fastest-growing category as Allianz Portugal, Zurich Portugal, and Mapfre Seguros Portugal expand fleet programs.
Regional Analysis
|
Region |
Estimated Market Share |
Key Growth Factors |
Consumer Trends |
|---|---|---|---|
|
A. M. Lisboa |
38% |
Dense vehicle ownership, corporate fleets, insurer headquarters concentration |
Digital policy purchase, comprehensive cover, commercial fleet demand |
|
Norte |
27% |
Industrial base, Porto metropolitan vehicle density, export logistics activity |
Price-comparison shopping, strong broker and agent reliance |
|
Centro |
16% |
Manufacturing clusters, inland road network, regional SME fleets |
Third-party extra cover, agent-led policy renewals |
|
Alentejo |
7% |
Agricultural and logistics vehicles, long-distance driving requirements |
Basic liability preference, local agent relationships |
|
Others |
12% |
Tourism rental fleets across the Algarve, Madeira, and the Azores |
Seasonal rental cover, short-term policy demand |
- A. M. Lisboa - Accounting for approximately 38% of total demand, the metropolitan area combines the highest vehicle density, concentrated corporate fleets, and the largest digital policy purchase volumes within the Portugal Auto Insurance Market.
- Norte - Porto's industrial and export base supports roughly 27% of demand, with price-conscious motorists relying heavily on brokers and agents to compare comprehensive and third-party options.
- Centro - Manufacturing clusters and regional SME fleets drive about 16% of demand, with agent-led renewals and third-party extra policies remaining the dominant purchasing pattern.
- Alentejo - Agricultural, logistics, and long-distance vehicles sustain approximately 7% of demand, where basic liability cover and long-standing local agent relationships shape buying decisions.
- Others - The Algarve, Madeira, and the Azores contribute about 12%, supported by tourism-driven rental fleets that generate seasonal and short-term motor insurance demand.
Market Share & Competitive Landscape
The competitive landscape is concentrated at the top, with Fidelidade, Ageas Portugal, and Generali holding the largest positions across Portugal's insurance sector. Insurers compete on pricing, claims service quality, digital capability, and distribution reach across agents, brokers, and bancassurance.
|
Company |
Competitive Strength |
Primary Segment Served |
|---|---|---|
|
Fidelidade Companhia de Seguros SA |
Market leadership, digital claims tools, extensive agent network |
Personal and commercial, new and used vehicles |
|
Ageas Portugal |
Multichannel distribution, bancassurance partnerships, second-largest group by premiums |
Personal motor, used vehicles |
|
Generali Seguros S.A. Portugal |
Generali Tranquilidade brand, expanded scale after Liberty Portugal integration |
Personal and SME motor |
|
Allianz Portugal |
Global brand strength, online purchase, 24/7 assistance |
New vehicles, digital-first buyers |
|
Zurich Portugal |
Comprehensive motor focus, corporate and fleet expertise |
Commercial fleets, new vehicles |
|
Mapfre Seguros Portugal |
Iberian scale, broker and agent network |
Mid-market personal, used vehicles |
Key Companies in the Portugal Auto Insurance Market
Fidelidade Companhia de Seguros SA
Fidelidade Companhia de Seguros SA, headquartered in Lisbon, is Portugal's largest insurer, holding roughly 29% of total premiums. In January 2024, it launched AutoDigital, an augmented reality claims application assessing vehicle damage remotely in under five minutes, reinforcing its digital servicing advantage and extensive agent network.
Generali Seguros S.A. Portugal
Generali Seguros, operating as Generali Tranquilidade, is headquartered in Lisbon and traces its roots to Companhia de Seguros Tranquilidade Portuense, founded in Porto in 1871. On 1 August 2025, it completed the legal integration of Liberty Seguros Portugal, consolidating domestic operations under the Generali Tranquilidade brand.
Recent Developments
|
Year |
Company |
Development |
|---|---|---|
|
Aug 2025 |
Generali Seguros S.A. Portugal |
Completed legal integration of the former Liberty Seguros Portugal branch through a cross-border partial merger |
|
H1 2025 |
Fidelidade Companhia de Seguros SA |
Lifted total insurance market share to 29.3%, retaining leadership ahead of Ageas Portugal and Generali |
Market Future Outlook
The Portugal Auto Insurance Market Forecast points to USD 8.37 billion by 2034, expanding at a 9.67% CAGR. Personal policyholders will remain the core revenue base, while commercial fleets accelerate. Fidelidade, Ageas Portugal, and Generali Tranquilidade are expected to defend share through bundled products, broker partnerships, and faster digital servicing.
Telematics, artificial intelligence-driven claims triage, and remote damage assessment will increasingly become standard across insurers through 2034. Electric vehicle adoption, connected-car data, and Solvency II capital discipline will influence pricing models, while ASF conduct rules and European motor insurance directives steer transparency, data governance, sustainability disclosure, and consumer protection standards.
Portugal Auto Insurance Market Report Coverage
This Portugal Auto Insurance Market Report covers market sizing, segmentation, regional demand, and competitive profiling for the 2026–2034 forecast period.
|
Report Attribute |
Details |
|---|---|
|
Market Name |
Portugal Auto Insurance Market |
|
Market Size (2026) |
USD 4.00 Billion |
|
Market Size (2034) |
USD 8.37 Billion |
|
Forecast Period |
2026–2034 |
|
CAGR |
9.67% |
|
Base Year |
2026 |
|
Historical Years |
2021–2025 |
|
Forecast Years |
2026–2034 |
|
Segments Covered |
By Coverage, By Distribution Channel, By Vehicle Age, By Vehicle Age |
|
Regions Covered |
Norte, Centro, A. M. Lisboa, Alentejo, Others |
|
Key Companies |
Fidelidade Companhia de Seguros SA, Ageas Portugal, Generali Seguros S.A. Portugal, Allianz Portugal, Zurich Portugal, Mapfre Seguros Portugal, Others |
|
Report Format |
PDF, Excel, PPT |
|
Customization |
Available as per client requirements |
Why Choose This Portugal Auto Insurance Market Report?
- Comprehensive coverage of Portugal's personal and commercial motor insurance premium landscape.
- Accurate market sizing from USD 4.00 billion in 2026 through the 2034 forecast.
- Detailed segmentation by vehicle age (New vs. Used) and application (Personal vs. Commercial).
- Regional insights covering Norte, Centro, A. M. Lisboa, Alentejo, and other regions with share estimates.
- Competitive profiling of six leading insurance providers operating across Portugal.
- Analysis of digital claims, telematics, and pricing trends shaping strategic decisions through 2034.
- Research aligned with ASF supervisory priorities and European motor insurance regulatory direction.
Table of Contents
- Introduction
- Objective of the Study
- Product Definition
- Market Segmentation
- Study Variables
- Research Methodology
- Secondary Data Points
- Companies Interviewed
- Primary Data Points
- Breakdown of Primary Interviews
- Secondary Data Points
- Executive Summary
- Market Dynamics
- Drivers
- Challenges
- Opportunity Assessment
- Recent Trends and Developments
- Policy and Regulatory Landscape
- Portugal Auto Insurance Market Overview and Forecast Analysis (2021-2034)
- Market Size, By Value, By Growth Rate (CAGR/USD Billions)
- Demand – Supply Trends
- Market Share, By Coverage
- Third Party Liability Coverage
- Collision/Comprehensive/Other Optional Coverages
- Market Share, By Distribution Channel
- Insurance Agents/Brokers
- Direct Response
- Banks
- Others
- Market Share, By Vehicle Age
- New Vehicles
- Used Vehicles
- Market Share, By Application
- Personal
- Commercial
- Market Share, By Region
- Norte
- Centro
- A. M. Lisboa
- Alentejo
- Others
- Market Share, By Competitors
- Competition Characteristics
- Revenue Shares
- Third Party Liability Coverage Portugal Auto Insurance Market Overview, 2021-2034F
- By Value (USD Million)
- By Distribution Channel – Market Size & Forecast 2021-2034, USD Million
- Insurance Agents/Brokers
- Direct Response
- Banks
- Others
- Collision/Comprehensive/Other Optional Coverages Portugal Auto Insurance Market Overview, 2021-2034F
- By Value (USD Million)
- By Distribution Channel – Market Size & Forecast 2021-2034, USD Million
- Insurance Agents/Brokers
- Direct Response
- Banks
- Others
- Competitive Outlook (Company Profile - Partial List)
- Fidelidade Companhia de Seguros SA
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Ageas Portugal
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Generali Seguros S.A. Portugal
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Allianz Portugal
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Zurich Portugal
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Mapfre Seguros Portugal
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Others
- Fidelidade Companhia de Seguros SA
- Contact Us & Disclaimer
Top Key Players & Market Share Outlook
- Fidelidade Companhia de Seguros SA
- Ageas Portugal
- Generali Seguros S.A. Portugal
- Allianz Portugal
- Zurich Portugal
- Mapfre Seguros Portugal
- Others
Frequently Asked Questions