
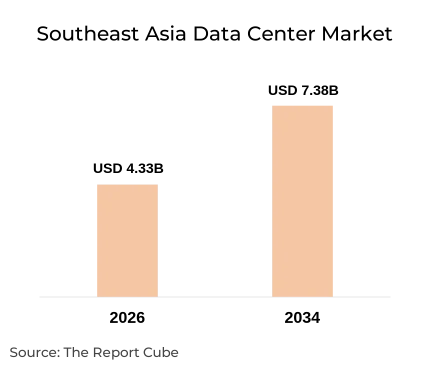
Build Your Custom Market Intelligence Report
Customize Your ReportKey Takeaways
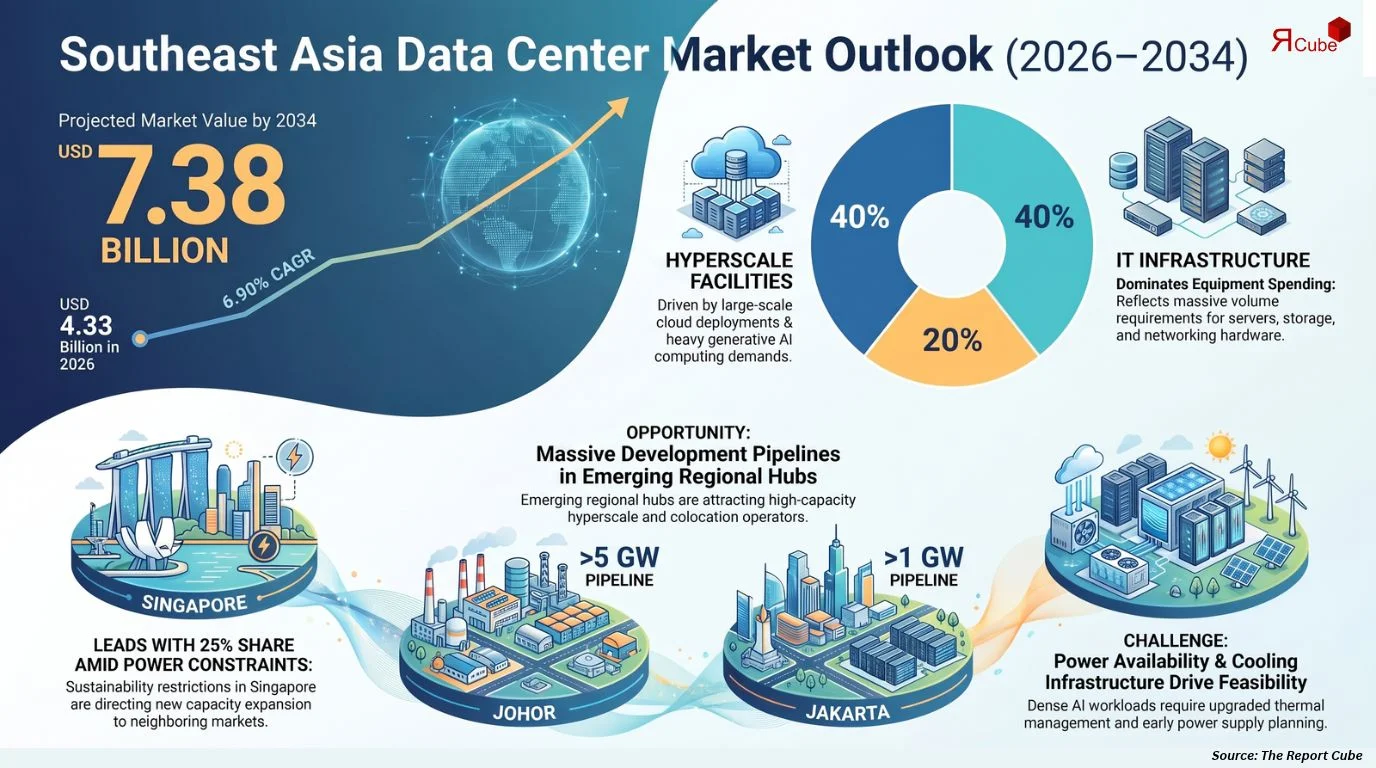
- Southeast Asia Data Center Market is valued at USD 4.33 billion in 2026.
- The market is projected to reach USD 7.38 billion by 2034, expanding at a CAGR of 6.90%.
- Hyperscale data centers lead the facility type segment with an estimated 40% share in 2026.
- IT infrastructure leads the infrastructure segment with an estimated 40% share in 2026.
- Singapore leads the country segment with an estimated 25% share in 2026.
- ABB, Bridge Data Centres, Caterpillar, Cisco, Dell Technologies, Delta Electronics, Digital Realty, EdgeConneX, Equinix and GDS Holdings are the supplied key players.
- Geographic expansion beyond Singapore and AI-ready infrastructure are important themes for the market.
Market Overview
A data centre is a purpose-built facility that houses servers, storage, networking equipment, and the power and cooling systems that keep them running. Enterprises, cloud providers, telecom operators, and public agencies use these facilities to host applications, store information, and exchange traffic, with resilience and uptime determined by design tier and power capacity.
Cloud adoption, generative AI workloads, digital transformation, and demand for local data hosting are raising computing and storage requirements across the region. Malaysia, Indonesia, Singapore, Thailand, Vietnam, and the Philippines are all expanding capacity, while government-backed digitalisation programmes support domestic infrastructure. This Southeast Asia Data Centre Market Analysis reflects an estimated value of USD 4.33 billion in 2026.
Operators and enterprises select facilities for connectivity, power availability, and the ability to support dense AI workloads, which is encouraging investment in efficient cooling and modernised infrastructure. Capacity is now also spreading beyond Singapore into several neighbouring national markets. The market is projected to grow at a CAGR of 6.90% during 2026–2034.
Southeast Asia Data Center Market Dynamics
Demand for capacity, power availability, land access, and cooling efficiency shape supply decisions across Southeast Asia, while cloud and AI workloads influence adoption. Sustainability requirements, construction timelines, and competition among colocation, hyperscale, and enterprise operators affect pricing, site selection, and equipment procurement throughout the forecast period.
|
Factor |
Type |
Specific Impact on Market |
Magnitude |
|---|---|---|---|
|
Cloud adoption and AI workloads |
Driver |
Raises demand for computing, storage, connectivity, and hyperscale capacity |
High |
|
Large project pipelines in Johor and Greater Jakarta |
Opportunity |
Creates openings for colocation providers, infrastructure suppliers, and cloud-focused operators |
Medium–High |
|
Power availability and sustainability requirements |
Challenge |
Limits expansion in Singapore and can affect timelines, operating costs, and project feasibility |
High |
|
AI-ready infrastructure |
Trend |
Increases need for upgraded power, cooling, and facility readiness |
High |
Southeast Asia Data Center Market Growth Drivers
Cloud adoption, generative AI workloads, and demand for local data hosting are increasing the requirement for computing capacity, storage, and connectivity. These factors support hyperscale infrastructure investment across regional economies. The Southeast Asia Data Centre Market Growth outlook therefore depends heavily on how quickly enterprises and public agencies move workloads onto cloud and AI platforms.
According to the ASEAN Guide for Sustainable Data Centre Development, Indonesia, Malaysia, the Philippines, Singapore, Thailand, and Vietnam are experiencing data centre expansion. Government-backed digitalisation initiatives and investment in domestic infrastructure are supporting this ongoing development, giving operators a broader regional base of countries in which to site new data centre capacity.
Southeast Asia Data Center Market Opportunities
Malaysia’s Johor region has more than 5 GW of data centre projects at various stages of development, according to the ASEAN Guide for Sustainable Data Centre Development, while Greater Jakarta has a pipeline exceeding 1 GW. These pipelines point to potential for colocation providers, infrastructure suppliers, and operators supporting large-scale cloud deployments.
CBRE’s Global Data Center Trends 2026 report notes that Singapore faces power availability and sustainability constraints, while energy optimisation and upgrades to existing facilities are creating investment opportunities. This supports demand for efficient cooling, power management systems, and infrastructure modernisation across the region, benefiting equipment suppliers and engineering service providers.
Southeast Asia Data Center Industry Challenges
CBRE’s 2026 report identifies power constraints and sustainability requirements as limiting data centre expansion in Singapore. Similar capacity and infrastructure constraints can affect development timelines, operating costs, and the feasibility of new projects in other regional markets. This makes securing electricity supply early in project planning important, since delays can postpone commissioning.
Sustainable development is a key consideration as the regional data centre pipeline expands, according to the ASEAN Guide for Sustainable Data Centre Development. Operators must account for electricity consumption, cooling requirements, water availability, and environmental performance when planning and operating facilities, which adds design complexity and compliance considerations to project delivery.
Need Specific Data, Let’s Customize the Report for You
Request CustomizationSoutheast Asia Data Center Market Trends
Investment is spreading into Malaysia, Indonesia, Thailand, and Vietnam as operators seek additional land, power capacity, and development opportunities, according to the ASEAN Guide for Sustainable Data Centre Development. Among the Southeast Asia Data Centre Market Trends, this indicates a broader regional distribution of new capacity rather than exclusive concentration in Singapore.
CBRE’s 2026 data centre outlook states that AI workloads are increasing demand for facilities capable of supporting more demanding computing requirements, while legacy data centres may need upgrades for newer workloads. This increases the importance of power capacity, cooling performance, and infrastructure readiness in facility design, procurement, and site selection.
Southeast Asia Data Center Market Segment Analysis
Southeast Asia Data Centre Market Share is distributed across facility types, infrastructure categories, tier standards, end users, and power capacity bands, each shaped by distinct workload and reliability requirements. Estimated 2026 shares are stated only for leading segments where supplied.
By Facility Type
- Colocation Data Centers
- Hyperscale Data Centers
- Enterprise Data Centers
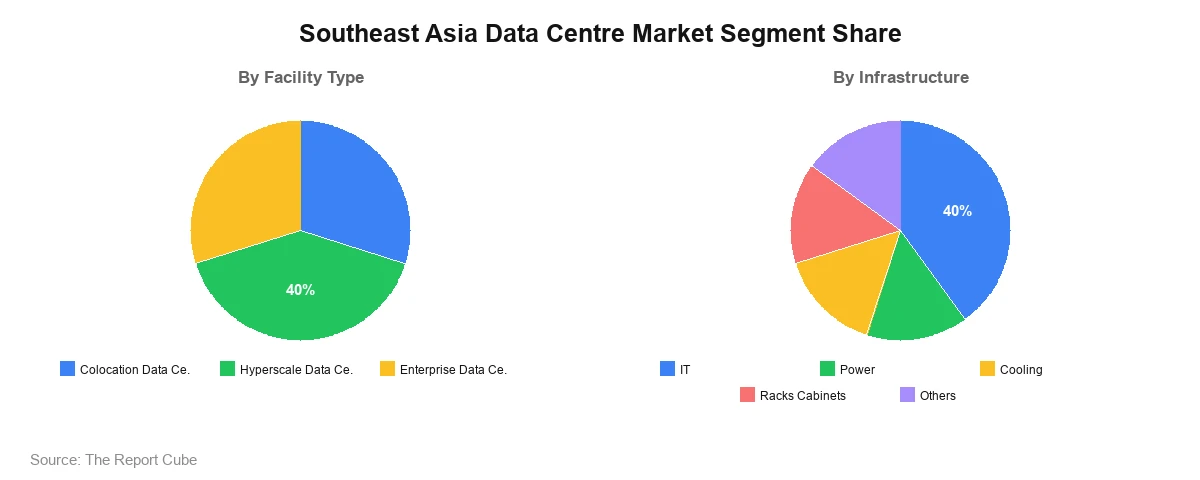
Hyperscale data centers lead the facility type segment with an estimated 40% share in 2026, supported by cloud expansion, generative AI workloads, and large-scale campus development in locations such as Johor and Greater Jakarta, where operators including Bridge Data Centres and GDS Holdings develop large-capacity sites. Colocation data centers follow, driven by multi-tenant demand for connectivity and interconnection from operators such as Equinix, Digital Realty, and EdgeConneX, which serve enterprises and cloud providers preferring shared infrastructure. Enterprise data centers remain relevant for organisations in regulated sectors that retain control over critical systems and data, with Dell Technologies and Cisco Systems supplying servers, storage, and networking equipment for these environments.
By Infrastructure
- IT
- Power
- Cooling
- Racks Cabinets
- Other
IT infrastructure leads the infrastructure segment with an estimated 40% share in 2026, reflecting the volume of servers, storage, and networking equipment required for cloud and AI workloads, with Dell Technologies and Cisco Systems among the relevant suppliers. Power infrastructure follows, supported by electrical distribution, backup generation, and power management requirements, with ABB, Caterpillar, and Delta Electronics supplying related systems. Cooling is gaining importance as higher-density workloads and sustainability requirements increase demand for efficient thermal management, including products from Delta Electronics. Racks and cabinets support equipment housing and cable management, while other infrastructure covers the remaining supporting systems required for facility operation.
Country Analysis
Southeast Asia Data Centre Market is assessed across Malaysia, Indonesia, Singapore, Cambodia, Vietnam, Thailand, the Philippines, and Others.
|
Country |
Estimated Market Share |
Key Growth Factors |
Industry Trends |
|---|---|---|---|
|
Malaysia |
- |
Johor pipeline above 5 GW of projects at various stages |
Cross-border capacity serving Singapore and regional demand |
|
Indonesia |
- |
Greater Jakarta pipeline exceeding 1 GW |
Growth in in-town and hyperscale capacity |
|
Singapore |
25% |
Established regional hub with strong connectivity |
Power and sustainability constraints; energy optimisation and facility upgrades |
|
Cambodia |
- |
Emerging digital infrastructure |
Not separately assessed |
|
Vietnam |
- |
Investment spreading into the market |
Broader regional distribution of new capacity |
|
Thailand |
- |
Investment spreading into the market |
Broader regional distribution of new capacity |
|
Philippines |
- |
Data centre expansion supported by digitalisation initiatives |
Government-backed domestic infrastructure investment |
|
Others |
- |
Remaining markets and specialised local demand |
Not separately assessed |
Singapore leads the country segment with an estimated 25% share in 2026, reflecting its role as an established regional hub for cloud and enterprise workloads. Power availability and sustainability requirements limit new development there, which is directing some expansion towards neighbouring locations while existing facilities pursue energy optimisation and upgrades.
Malaysia and Indonesia are the main emerging locations, with Johor reporting more than 5 GW of projects at various stages and Greater Jakarta exceeding 1 GW. Thailand, Vietnam, and the Philippines are also experiencing expansion, supported by government-backed digitalisation. Regional market shares beyond Singapore have not been supplied and require validation before publication.
Market Share & Competitive Landscape
The Southeast Asia Data Centre Market includes colocation and hyperscale operators, power and cooling suppliers, and IT equipment providers. The table summarises the supplied companies by general capability and relevant segment. It does not represent numerical market share.
|
Company |
Competitive Strength |
Primary Segment Served |
|---|---|---|
|
ABB Ltd. |
Electrical distribution, automation, and power management |
Power infrastructure |
|
Bridge Data Centres |
Hyperscale and colocation campus development in Asia |
Hyperscale data centers |
|
Caterpillar Inc. |
Generator sets and backup power systems |
Power infrastructure |
|
Cisco Systems Inc. |
Networking, switching, and connectivity equipment |
IT infrastructure |
|
Dell Technologies Inc. |
Servers, storage, and enterprise computing |
IT infrastructure and enterprise data centers |
|
Delta Electronics Inc. |
Power electronics and cooling solutions |
Power and cooling infrastructure |
|
Digital Realty Trust Inc. |
Colocation and interconnection across Singapore, Jakarta, and Malaysia |
Colocation data centers |
|
EdgeConneX Inc. |
Data centre development for edge and hyperscale deployments |
Colocation and hyperscale data centers |
|
Equinix Inc. |
Interconnection-focused colocation across Singapore, Johor, and Kuala Lumpur |
Colocation data centers |
|
GDS Holdings Ltd. |
Hyperscale campus operation, including a campus in Johor |
Hyperscale data centers |
|
Others |
Regional operators, telecom carriers, and equipment distributors |
Local capacity and equipment supply |
Key Companies in the Southeast Asia Data Center Market
Equinix Inc.: Equinix is headquartered in Redwood City, California, and operates over 280 data centers across 77 markets in 36 countries. In Malaysia, its US$201 million JH2 facility in Johor topped out in 2025, while Cyberjaya KL1 completed a second phase. Its strength is interconnection-focused colocation across Kuala Lumpur, Johor, and Singapore.
Digital Realty Trust Inc.: Digital Realty is headquartered in Austin, Texas, and operates more than 300 facilities across over 25 countries. In 2025 it formed a joint venture, Digital Realty Bersama, for Jakarta campuses CGK10 and CGK11, and in January 2026 announced Malaysia entry through TelcoHub 1 in Cyberjaya. Its strength is connected colocation.
Recent Developments
|
Year / Month |
Company |
Development |
|---|---|---|
|
March 2025 |
Digital Realty |
Formed a 50/50 joint venture with Bersama Digital Infrastructure Asia, creating Digital Realty Bersama, which owns the CGK10 and CGK11 data centers in Jakarta. |
|
May 2025 |
Equinix |
Completed the second phase of its KL1 data center in Cyberjaya, Malaysia, a US$100 million facility. |
|
November 2025 |
Equinix |
Topped out JH2 in Johor, a US$201 million facility; launch is planned for the third quarter of 2027 (announced plan). |
|
January 2026 |
Digital Realty |
Announced entry into Malaysia through the acquisition of CSF Advisers, owner of the 1.5 MW TelcoHub 1 in Cyberjaya; closing was expected in the first half of 2026. |
|
May 2026 |
Equinix |
Announced plans for a purpose-built data center in Kuala Lumpur (announced plan). |
Southeast Asia Data Center Market Future Outlook
The Southeast Asia Data Centre Market Forecast indicates expansion from USD 4.33 billion in 2026 to USD 7.38 billion by 2034 at a CAGR of 6.90%, based on supplied estimates. Growth is expected to depend on cloud adoption, AI workloads, national digital infrastructure programmes, and the pace at which new capacity in Malaysia, Indonesia, and neighbouring markets is brought into operation.
Technology investment is likely to concentrate on efficient cooling, power management, and upgrades that make existing facilities suitable for AI workloads. Risks include power availability, sustainability requirements, water and electricity consumption, and project timelines. The projected values remain supplied assumptions, and actual outcomes will depend on regulation, operator execution, and the availability of land and energy across regional markets in Southeast Asia.
Southeast Asia Data Center Market Report Coverage
This Southeast Asia Data Centre Market Report summarises the supplied valuation, forecast assumptions, segmentation, and regional framework.
|
Parameter |
Details |
|---|---|
|
Market Name |
Southeast Asia Data Centre Market |
|
Market Size 2026 |
USD 4.33 billion |
|
Market Size 2034 |
USD 7.38 billion |
|
Forecast Period |
2026–2034 |
|
CAGR |
6.90% |
|
Base Year |
2026 |
|
Historical Years |
2021–2025 |
|
Forecast Years |
2026–2034 |
|
Segments Covered |
By Facility Type; By Infrastructure; By Tier Standard; By End User; By Power Capacity |
|
Regions Covered |
Malaysia, Indonesia, Singapore, Cambodia, Vietnam, Thailand, Philippines, Others |
|
Key Companies |
ABB Ltd., Bridge Data Centres, Caterpillar Inc., Cisco Systems Inc., Dell Technologies Inc., Delta Electronics Inc., Digital Realty Trust Inc., EdgeConneX Inc., Equinix Inc., GDS Holdings Ltd. |
|
Customization |
Available as per client requirements |
Why Choose This Southeast Asia Data Center Market Report?
- Market scope covering colocation, hyperscale, and enterprise facilities alongside supporting infrastructure.
- Clear presentation of the supplied 2026 valuation, 2034 forecast, and 6.90% CAGR.
- Segmentation across facility type, infrastructure, tier standard, end user, and power capacity.
- Country-level framework spanning Malaysia, Indonesia, Singapore, Vietnam, Thailand, the Philippines, and other markets.
- Competitive profiling of supplied operators, power and cooling suppliers, and IT equipment providers.
- Trend insights on AI-ready infrastructure, geographic expansion, and sustainability requirements.
- Context on power availability and sustainable development priorities relevant to capacity planning.
Table of Contents
- Introduction
- Objective of the Study
- Product Definition
- Market Segmentation
- Study Variables
- Research Methodology
- Secondary Data Points
- Companies Interviewed
- Primary Data Points
- Breakdown of Primary Interviews
- Secondary Data Points
- Executive Summary
- Market Dynamics
- Drivers
- Challenges
- Opportunity Assessment
- Recent Trends and Developments
- Policy and Regulatory Landscape
- Southeast Asia Data Center Market Overview and Forecast Analysis (2021-2034)
- Market Size, By Value, By Growth Rate (CAGR/USD Billions)
- Demand – Supply Trends
- Market Share, By Facility Type
- Colocation Data Centers
- Hyperscale Data Centers
- Enterprise Data Centers
- Market Share, By Infrastructure
- IT
- Power
- Cooling
- Racks Cabinets
- Other
- Market Share, By Tier Standard
- Tier I II
- Tier III
- Tier IV
- Market Share, By End User
- IT Telecom
- Banking Financial
- Government Public
- Media Entertainment
- Healthcare Other
- Market Share, By Power Capacity
- Below 5 MW
- 5 to 15 MW
- Above 15 MW
- Market Share, By Country
- Malaysia
- Indonesia
- Singapore
- Cambodia
- Vietnam
- Thailand
- Philippines
- Others
- Market Share, By Competitors
- Competition Characteristics
- Revenue Shares
- Colocation Data Centers Southeast Asia Data Center Market Overview, 2021-2034F
- By Value (USD Million)
- By Infrastructure – Market Size & Forecast 2021-2034, USD Million
- IT
- Power
- Cooling
- Racks Cabinets
- Other
- Hyperscale Data Centers Southeast Asia Data Center Market Overview, 2021-2034F
- By Value (USD Million)
- By Infrastructure – Market Size & Forecast 2021-2034, USD Million
- IT
- Power
- Cooling
- Racks Cabinets
- Other
- Enterprise Data Centers Southeast Asia Data Center Market Overview, 2021-2034F
- By Value (USD Million)
- By Infrastructure – Market Size & Forecast 2021-2034, USD Million
- IT
- Power
- Cooling
- Racks Cabinets
- Other
- Competitive Outlook (Company Profile – Partial List)
- ABB Ltd.
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Bridge Data Centres
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Caterpillar Inc.
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Cisco Systems Inc.
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Dell Technologies Inc.
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Delta Electronics Inc.
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Digital Realty Trust Inc.
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- EdgeConneX Inc.
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Equinix Inc.
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- GDS Holdings Ltd.
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- ABB Ltd.
- Contact Us & Disclaimer
Top Key Players & Market Share Outlook
- ABB Ltd.
- Bridge Data Centres
- Caterpillar Inc.
- Cisco Systems Inc.
- Dell Technologies Inc.
- Delta Electronics Inc.
- Digital Realty Trust Inc.
- EdgeConneX Inc.
- Equinix Inc.
- GDS Holdings Ltd.
Frequently Asked Questions