
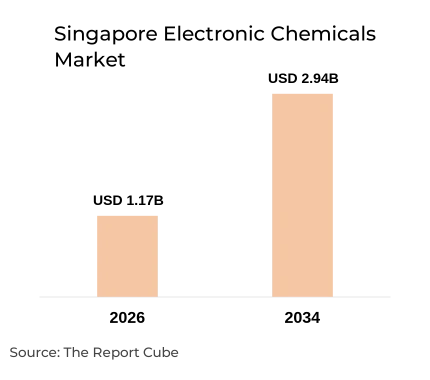
Build Your Custom Market Intelligence Report
Customize Your ReportKey Takeaways
- Singapore Electronic Chemicals Market valued at USD 1.17 billion in 2026, reflecting robust semiconductor-driven demand.
- Industry projected to reach USD 2.94 billion by 2034, expanding at a 12.20% CAGR through the forecast period.
- A comprehensive Singapore Electronic Chemicals Market Analysis reveals accelerating demand across advanced node fabrication and advanced packaging segments.
- Semiconductor fabrication dominates the application segment, underpinned by Singapore's established wafer fab infrastructure.
- Advanced nodes (≤ 7nm) represent the fastest-growing technology node segment as chipmakers pursue next-generation process migration.
- West Region commands the largest regional share, concentrated around Jurong Island's integrated petrochemical and chemical manufacturing cluster.
- BASF SE, The Dow Chemical Company, and Sumitomo Chemical lead electronic chemical supply across Singapore's fabrication ecosystem.
- Sustainability-driven reformulation and ultra-high-purity chemical development are reshaping procurement across Singapore's semiconductor supply chain.
Market Overview
The Singapore Electronic Chemicals Market is anticipated to register a 12.20% CAGR during 2026–2034. The market was valued at USD 1.17 billion in 2026 and is projected to reach USD 2.94 billion by 2034. Singapore's advanced semiconductor manufacturing base, anchored by global foundries and integrated device manufacturers, sustains consistent demand for high-purity process chemicals across etch, deposition, and cleaning applications. Government programs under the Singapore Economic Development Board (EDB) and RIE2025 research framework continue attracting chemical suppliers and semiconductor capital investment, reinforcing upstream chemical procurement growth. BASF SE and The Dow Chemical Company maintain strong regional supply presence servicing multiple wafer fabrication facilities.
Singapore's strategic position as a leading global semiconductor hub and free-trade gateway enhances the distribution efficiency of specialty electronic chemicals across Southeast Asia. Air Products and Chemicals Inc. and Sumitomo Chemical have deepened technical partnerships with local chip manufacturers, while Evonik Industries supplies specialty functional materials for advanced packaging applications. Growing adoption of advanced nodes and chiplet-based architectures is driving chemical innovation requirements, with suppliers investing in application laboratories and formulation centres within Singapore to co-develop ultra-high-purity chemical solutions aligned with evolving sub-7nm process technology demands.
Market Size & Forecast
|
Metric |
Details |
|---|---|
|
Market Size (2026) |
USD 1.17 Billion |
|
Market Size (2034) |
USD 2.94 Billion |
|
CAGR (2026–2034) |
12.20% |
|
Base Year |
2026 |
|
Historical Years |
2021–2025 |
|
Forecast Years |
2026–2034 |
The Singapore Electronic Chemicals Market Size study values the industry at USD 1.17 billion in 2026 and projects growth to USD 2.94 billion by 2034, expanding at a 12.20% CAGR. This trajectory significantly outpaces the broader Asia-Pacific specialty chemicals average, driven by Singapore's accelerating advanced node adoption, chiplet packaging proliferation, and sustained capacity expansion by leading global foundry operators through the forecast period.
Market Dynamics
Singapore's electronic chemicals sector is expanding as semiconductor fabrication complexity intensifies, advanced packaging adoption accelerates, and global chipmakers continue selecting Singapore as a preferred manufacturing and co-development location. The Singapore Electronic Chemicals Market Growth is primarily driven by rising capital expenditure in sub-7nm wafer fabrication, growing demand for ultra-high-purity specialty chemicals, and government-backed cluster development across Jurong Island and Woodlands industrial zones.
|
Factor |
Type |
Specific Impact on Market |
Magnitude |
|---|---|---|---|
|
Advanced node semiconductor investment |
Driver |
Increases demand for high-purity etch, CMP slurries, and deposition chemicals |
High |
|
Government EDB investment facilitation |
Driver |
Attracts global chemical suppliers and strengthens local supply chain infrastructure |
High |
|
Supply chain concentration risk |
Restraint |
Dependence on imported chemical precursors creates vulnerability to geopolitical disruption |
Medium |
|
Advanced packaging technology adoption |
Opportunity |
Drives demand for underfill materials, specialty adhesives, and dielectric chemicals |
High |
|
REACH and TSCA chemical compliance |
Challenge |
Raises formulation cost and regulatory complexity for specialty chemical suppliers |
Medium |
Growth Drivers - Advanced Node Semiconductor Capacity Expansion
Singapore hosts fabrication facilities operated by leading global foundries and integrated device manufacturers investing in sub-7nm technology nodes. This capital expenditure directly drives procurement of ultra-high-purity photoresists, wet etch chemicals, and CMP slurries from BASF SE, The Dow Chemical Company, and Air Products and Chemicals Inc., sustaining high-volume electronic chemical demand.
Market Restraints - Import Dependency and Precursor Supply Vulnerability
Singapore's electronic chemicals ecosystem relies heavily on imported chemical precursors, primarily sourced from Japan, South Korea, and Germany. Geopolitical tensions, export controls on specialty chemical feedstocks, and maritime supply chain disruptions introduce procurement uncertainty. Local chemical manufacturers lack sufficient upstream precursor capacity, increasing exposure to international supply volatility and spot price escalation.
Market Opportunities - Advanced Packaging and Heterogeneous Integration Demand
The global transition toward chiplet architectures, 2.5D/3D IC packaging, and fan-out wafer-level packaging (FOWLP) creates substantial demand for specialty underfill resins, temporary bonding materials, and dielectric planarization chemicals. Singapore's concentration of advanced packaging assembly and test operations positions electronic chemical suppliers to capture incremental specialty material volumes as heterogeneous integration adoption accelerates through 2034.
Industry Challenges - Regulatory Compliance and Chemical Reformulation Costs
Singapore's chemical industry operates under Singapore's Chemical Weapons Convention obligations and international compliance frameworks including REACH and TSCA, which govern formulation, import, and handling of specialty electronic chemicals. Evolving environmental regulations are compelling suppliers to reformulate solvent-based chemistries toward lower-VOC alternatives, increasing development costs and extending product qualification timelines across semiconductor fabrication customers.
Need Specific Data, Let’s Customize the Report for You
Request CustomizationMarket Trends
- Emerging Trends: Singapore Electronic Chemicals Market Trends indicate accelerating adoption of low-global-warming-potential (GWP) etchants and cleaning agents across advanced wafer fabrication operations. Chemical suppliers are introducing fluorine-free and aqueous-based cleaning chemistries as semiconductor manufacturers pursue Scope 3 emissions reduction commitments aligned with international sustainability standards.
- Technology Trends: High-k dielectric deposition precursors, atomic layer deposition (ALD) chemicals, and extreme ultraviolet (EUV) photoresist formulations are gaining procurement priority as Singapore-based fabs transition to sub-5nm technology nodes. Sumitomo Chemical and BASF SE are investing in ALD precursor R&D to serve next-generation gate-all-around transistor process requirements.
- Consumer / Buyer Trends: Semiconductor fabricators and advanced packaging houses in Singapore increasingly demand chemical supply agreements with dual-source qualification, on-site chemical blending capabilities, and certified ultrapure delivery systems. Buyers prioritize suppliers offering application engineering support, in-fab process integration assistance, and rapid qualification capabilities aligned with accelerated technology migration schedules.
- Regulatory Trends: Singapore's National Environment Agency (NEA) continues updating hazardous chemical storage and handling regulations, directly affecting electronic chemical logistics and on-site inventory practices. Alignment with IEC and SEMI international chemical purity standards is becoming a baseline procurement requirement. Suppliers must also comply with Singapore's Chemical Industries (Amendment) Act provisions governing specialty solvent imports and storage.
Singapore Electronic Chemicals Market Segment Analysis
Singapore's electronic chemicals market serves distinct application categories and technology node tiers, each reflecting unique process chemistry requirements, purity specifications, and procurement volumes shaped by Singapore's advanced semiconductor and display manufacturing ecosystem.
By Application
- Semiconductor Fabrication
- Advanced Packaging
- Flat Panel Displays
- Printed Circuit Boards
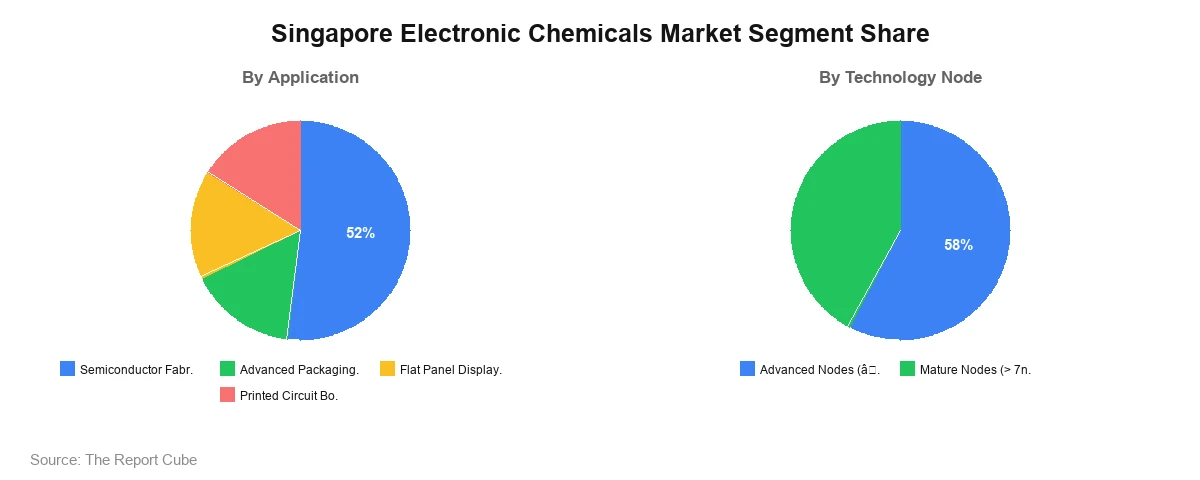
Semiconductor fabrication commands the dominant Singapore Electronic Chemicals Market Share among all application categories, representing an estimated 52% of total market volume in 2026. BASF SE, The Dow Chemical Company, and Air Products and Chemicals Inc. are primary chemical suppliers serving Singapore's wafer fabrication facilities with photoresists, CMP slurries, and wet etch chemistries. Advanced packaging accounts for approximately 26% of application demand, driven by expanding flip-chip, FOWLP, and 2.5D integration activity, with Evonik Industries and Sumitomo Chemical supplying specialty dielectrics and underfill materials. Flat panel displays represent around 14%, while printed circuit boards account for the remaining 8%, served by standard-grade chemical formulations from global suppliers.
By Technology Node
- Advanced Nodes (≤ 7nm)
- Mature Nodes (> 7nm)
Advanced nodes (≤ 7nm) account for an estimated 58% of technology node demand in 2026, reflecting Singapore's concentration of leading-edge foundry capacity requiring ultra-high-purity ALD precursors, EUV photoresists, and low-defectivity cleaning agents. BASF SE and Sumitomo Chemical supply the majority of advanced node chemical volumes across Singapore's sub-7nm fabs. Mature nodes (> 7nm) represent approximately 42% of demand, serving analog, power semiconductor, and automotive chip fabrication with established chemical formulations sourced from The Dow Chemical Company and Air Products and Chemicals Inc. Advanced nodes are the faster-growing technology segment as leading foundries accelerate process migration timelines toward 3nm and beyond.
Regional Analysis
|
Region |
Estimated Market Share |
Key Growth Factors |
Consumer Trends |
|---|---|---|---|
|
West Region |
44% |
Jurong Island chemical cluster, major fab concentration, EDB investment zones |
Ultra-high-purity chemical procurement, advanced node process chemistry |
|
Central Region |
22% |
R&D institutes, semiconductor design centers, EDB headquarters proximity |
Application engineering partnerships, specialty material qualification |
|
North Region |
16% |
Woodlands industrial estate, wafer backend manufacturing, logistics hubs |
Mature node chemicals, PCB process chemistry, supply chain consolidation |
|
North-East Region |
11% |
Seletar aerospace and electronics zone, substrate manufacturing activity |
Advanced packaging materials, dielectric and underfill chemical demand |
|
East Region |
7% |
Changi export gateway, chemical distribution and logistics operations |
Import/export facilitation, distribution chemicals, bonded storage activity |
- West Region - Accounting for approximately 44% of total Singapore Electronic Chemicals Market demand, the West Region encompasses Jurong Island's integrated chemical manufacturing cluster and hosts the highest concentration of wafer fabrication facilities sourcing advanced-node process chemicals from BASF SE, Air Products and Chemicals Inc., and Sumitomo Chemical. EDB-designated investment zones continue attracting capacity expansion and chemical supplier co-location.
- Central Region - Contributing approximately 22% of market demand, the Central Region houses Singapore's semiconductor research institutes, EDB-linked innovation centers, and regional headquarters of major chemical suppliers. Technical application laboratories established by Evonik Industries and The Dow Chemical Company support process chemical development and customer qualification activities for advanced packaging applications.
- North Region - Representing around 16% of market share, the North Region's Woodlands industrial estate supports semiconductor backend operations and printed circuit board manufacturers. Procurement activity centers on mature-node process chemicals, board-level cleaning agents, and copper interconnect chemistries from The Dow Chemical Company and Air Products and Chemicals Inc.
- North-East Region - Accounting for approximately 11% of demand, this region hosts substrate manufacturing and advanced packaging assembly operations driving procurement of dielectric planarization chemicals, temporary bonding materials, and specialty underfill resins. Evonik Industries and Sumitomo Chemical are key chemical suppliers serving this geography.
- East Region - Contributing around 7% of market share, the East Region functions primarily as a chemical import gateway and bonded logistics hub. Changi Airport Free Trade Zone and Pasir Ris industrial estates support chemical distribution, sampling, and re-export activities serving the broader Southeast Asian electronics manufacturing ecosystem.
Market Share & Competitive Landscape
Singapore's electronic chemicals competitive landscape is dominated by global specialty chemical corporations with dedicated semiconductor divisions, competing on chemical purity specifications, application engineering depth, regulatory compliance capability, and supply chain reliability across advanced and mature node fabrication accounts.
|
Company |
Competitive Strength |
Primary Segment Served |
|---|---|---|
|
BASF SE |
Broad advanced-node chemistry portfolio, global EHS compliance infrastructure |
Semiconductor Fabrication, Advanced Packaging |
|
The Dow Chemical Company |
Integrated photoresist and CMP slurry capabilities, long-term foundry partnerships |
Semiconductor Fabrication, PCBs |
|
Air Products and Chemicals Inc. |
Specialty gas and wet chemical integration, ultra-high-purity delivery systems |
Semiconductor Fabrication, Advanced Nodes |
|
Sumitomo Chemical |
Advanced photoresist and ALD precursor leadership, strong Japan-Singapore supply chain |
Semiconductor Fabrication, Advanced Nodes |
|
Evonik Industries |
Specialty functional materials, underfill resins, dielectric expertise |
Advanced Packaging, Flat Panel Displays |
|
Others |
Niche chemical supply, regional distribution, mature-node process chemistry |
PCBs, Mature Node Fabrication |
Key Companies in the Singapore Electronic Chemicals Market
BASF SE
BASF SE, headquartered in Ludwigshafen, Germany, is one of the world's largest specialty chemical corporations, operating electronic materials divisions serving semiconductor manufacturers across Asia, Europe, and the Americas. In 2025, BASF strengthened its Singapore supply chain by expanding its electronic chemicals distribution and technical support infrastructure, enhancing service capability for advanced-node wafer fabrication customers. Its broad portfolio spanning photoresists, CMP formulations, and ALD precursors positions it as a structurally critical supplier across Singapore's leading-edge semiconductor ecosystem.
The Dow Chemical Company
The Dow Chemical Company, headquartered in Midland, Michigan, USA, maintains a substantial electronic materials division supplying photoresists, dielectric films, and copper interconnect chemistries to global semiconductor manufacturers. In 2025, Dow reinforced its Singapore market presence by introducing new low-k dielectric formulations targeting advanced packaging and sub-7nm back-end-of-line process applications. Its long-standing foundry partnerships and integrated application engineering capability across Singapore's fabrication landscape underpin its competitive position in the Singapore Electronic Chemicals Market.
Recent Developments
|
Year |
Company |
Development |
|---|---|---|
|
2025 |
BASF SE |
Expanded electronic chemicals distribution and technical support infrastructure in Singapore to serve advanced-node wafer fabrication customers |
|
2025 |
The Dow Chemical Company |
Introduced new low-k dielectric formulations for advanced packaging and sub-7nm process applications in Singapore |
|
2025 |
Air Products and Chemicals Inc. |
Announced investment in ultra-high-purity chemical delivery system upgrades for Singapore-based semiconductor fabrication clients |
Future Outlook
The Singapore Electronic Chemicals Market Forecast projects the industry to reach USD 2.94 billion by 2034, expanding at a 12.20% CAGR through the forecast period. Sustained capital investment in advanced-node wafer fabrication, accelerating adoption of chiplet and 2.5D/3D IC packaging architectures, and Singapore's reinforced role as Southeast Asia's premier semiconductor manufacturing hub will collectively sustain electronic chemical demand. BASF SE, Sumitomo Chemical, and Air Products and Chemicals Inc. are expected to deepen Singapore market penetration through co-development agreements, on-site blending facilities, and expanded ultra-high-purity delivery infrastructure aligned with sub-5nm and next-generation gate-all-around transistor process requirements.
Advanced chemical manufacturing capabilities, including atomic layer deposition precursor production, EUV photoresist synthesis, and sustainable solvent reformulation, will increasingly differentiate leading suppliers as Singapore's semiconductor industry pursues both performance advancement and environmental compliance. Regulatory convergence with SEMI international chemical purity standards, combined with growing procurement preference for dual-qualified supply sources, will accelerate consolidation among established global suppliers. Singapore's Research, Innovation and Enterprise (RIE) programs are expected to fund further chemical innovation co-investment, embedding specialty chemical suppliers more deeply within Singapore's semiconductor technology ecosystem through 2034.
Singapore Electronic Chemicals Market Report Coverage
This Singapore Electronic Chemicals Market Report covers the complete forecast period from 2026 to 2034, providing market sizing, segmentation analysis, regional breakdown, competitive profiling, and strategic outlook across the full electronic chemicals value chain in Singapore.
|
Report Attribute |
Details |
|---|---|
|
Market Name |
Singapore Electronic Chemicals Market |
|
Market Size (2026) |
USD 1.17 Billion |
|
Market Size (2034) |
USD 2.94 Billion |
|
Forecast Period |
2026–2034 |
|
CAGR |
12.20% |
|
Base Year |
2026 |
|
Historical Years |
2021–2025 |
|
Forecast Years |
2026–2034 |
|
Segments Covered |
By Product, By Application, By Technology Node |
|
Regions Covered |
West Region, Central Region, North Region, North-East Region, East Region |
|
Key Companies |
BASF SE, The Dow Chemical Company, Air Products and Chemicals Inc., Sumitomo Chemical, Evonik Industries, Others |
|
Report Format |
PDF, Excel, PPT |
|
Customization |
Available as per client requirements |
Why Choose This Singapore Electronic Chemicals Market Report?
- Comprehensive coverage of Singapore's advanced semiconductor and packaging-driven electronic chemicals ecosystem.
- Accurate market sizing from USD 1.17 billion in 2026 through USD 2.94 billion forecast for 2034.
- Detailed segmentation by application type and technology node with share percentages.
- Regional breakdown across all five Singapore planning regions with demand share estimates and growth drivers.
- Competitive profiling of five leading global electronic chemical suppliers operating in Singapore.
- In-depth analysis of advanced node chemical innovation trends reshaping procurement and supplier qualification.
- Forecast data supporting supplier investment planning, market entry strategy, and partnership prioritization through 2034.
- Research aligned with Singapore's EDB semiconductor investment initiatives and RIE2025 national research framework.
Table of Contents
- Introduction
- Objective of the Study
- Product Definition
- Market Segmentation
- Study Variables
- Research Methodology
- Secondary Data Points
- Companies Interviewed
- Primary Data Points
- Breakdown of Primary Interviews
- Secondary Data Points
- Executive Summary
- Market Dynamics
- Drivers
- Challenges
- Opportunity Assessment
- Recent Trends and Developments
- Policy and Regulatory Landscape
- Singapore Electronic Chemicals Market Overview and Forecast Analysis (2021-2034)
- Market Size, By Value, By Growth Rate (CAGR/USD Billions)
- Demand – Supply Trends
- Market Share, By Product
- Electronic Wet Chemicals
- Specialty Gases
- Photoresist & Ancillary Chemicals
- Chemical Mechanical Planarization
- Silicon Wafers & Substrates
- Market Share, By Application
- Semiconductor Fabrication
- Advanced Packaging
- Flat Panel Displays
- Printed Circuit Boards
- Market Share, By Technology Node
- Advanced Nodes (≤ 7nm)
- Mature Nodes (> 7nm)
- Market Share, By Region
- Central Region
- East Region
- North Region
- North-East Region
- West Region
- Market Share, By Competitors
- Competition Characteristics
- Revenue Shares
- Electronic Wet Chemicals Singapore Electronic Chemicals Market Overview, 2021-2034F
- By Value (USD Million)
- By Application – Market Size & Forecast 2021-2034, USD Million
- Semiconductor Fabrication
- Advanced Packaging
- Flat Panel Displays
- Printed Circuit Boards
- Specialty Gases Singapore Electronic Chemicals Market Overview, 2021-2034F
- By Value (USD Million)
- By Application – Market Size & Forecast 2021-2034, USD Million
- Semiconductor Fabrication
- Advanced Packaging
- Flat Panel Displays
- Printed Circuit Boards
- Photoresist & Ancillary Chemicals Singapore Electronic Chemicals Market Overview, 2021-2034F
- By Value (USD Million)
- By Application – Market Size & Forecast 2021-2034, USD Million
- Semiconductor Fabrication
- Advanced Packaging
- Flat Panel Displays
- Printed Circuit Boards
- Chemical Mechanical Planarization Singapore Electronic Chemicals Market Overview, 2021-2034F
- By Value (USD Million)
- By Application – Market Size & Forecast 2021-2034, USD Million
- Semiconductor Fabrication
- Advanced Packaging
- Flat Panel Displays
- Printed Circuit Boards
- Silicon Wafers & Substrates Singapore Electronic Chemicals Market Overview, 2021-2034F
- By Value (USD Million)
- By Application – Market Size & Forecast 2021-2034, USD Million
- Semiconductor Fabrication
- Advanced Packaging
- Flat Panel Displays
- Printed Circuit Boards
- Competitive Outlook (Company Profile - Partial List)
- BASF SE
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- The Dow Chemical Company
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Air Products and Chemicals Inc.
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Sumitomo Chemical
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Evonik Industries
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Others
- BASF SE
- Contact Us & Disclaimer
Top Key Players & Market Share Outlook
- BASF SE
- The Dow Chemical Company
- Air Products and Chemicals Inc.
- Sumitomo Chemical
- Evonik Industries
- Others
Frequently Asked Questions