
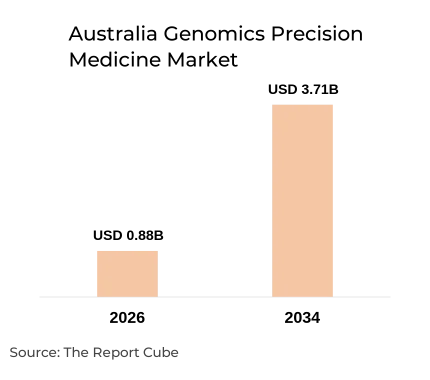
Build Your Custom Market Intelligence Report
Customize Your ReportKey Takeaways
- Australia Genomics Precision Medicine Market valued at USD 0.88 billion in 2026, reflecting robust clinical and research demand.
- Market projected to reach USD 3.71 billion by 2034, expanding at a 19.70% CAGR through the forecast period.
- A comprehensive Australia Genomics Precision Medicine Market Analysis reveals oncology and cancer diagnostics as the leading clinical application segment.
- Oncology and cancer diagnostics commands the highest clinical application share, driven by national cancer genomics initiatives.
- Hospitals and clinical diagnostic labs dominate end-user procurement, supported by expanding public genomics infrastructure.
- Academic and research institutes are the fastest-growing end-user segment, accelerating translational genomics research programs.
- Illumina Inc, Thermo Fisher Scientific Inc, and F. Hoffmann-La Roche Ltd are among the leading market participants.
- Pharmacogenomics and polygenic risk scoring are reshaping clinical decision-making across Australian healthcare institutions.
Market Overview
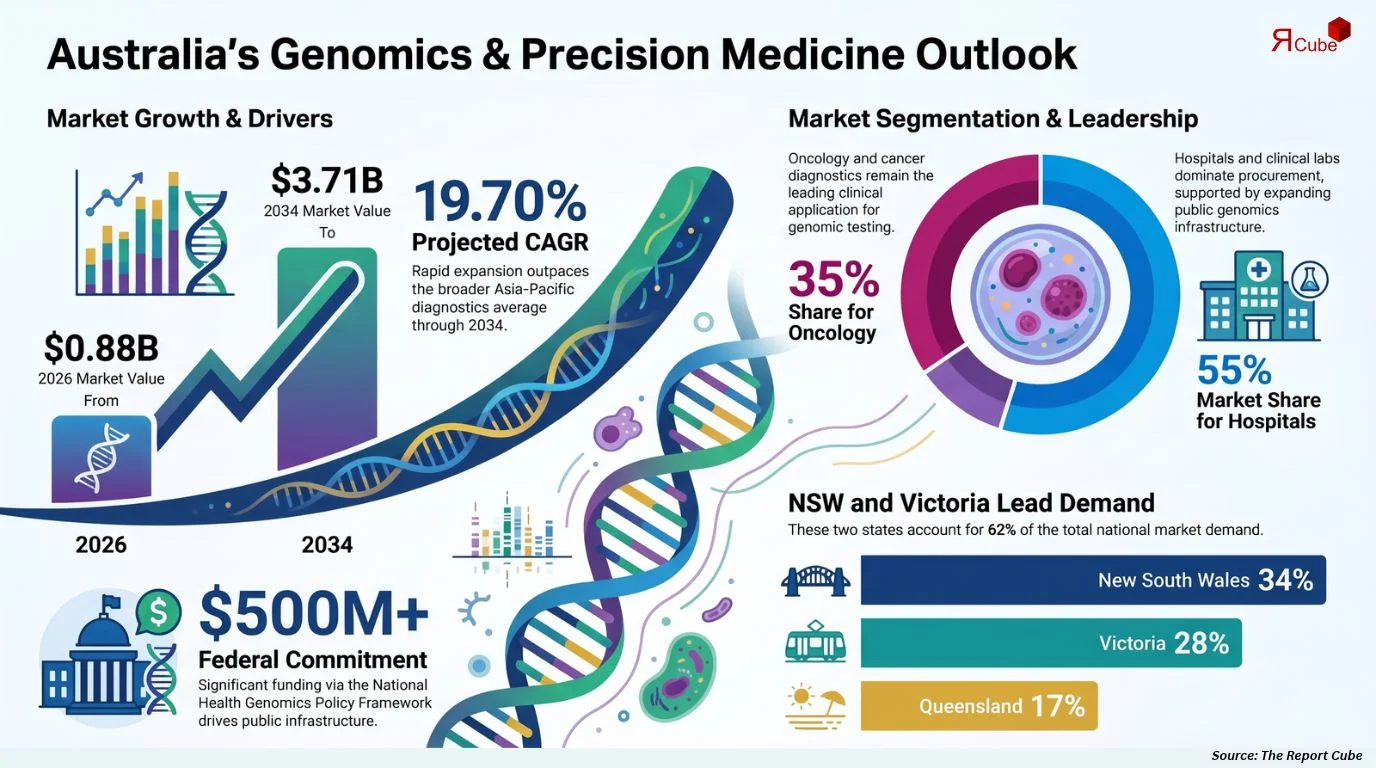
The Australia Genomics Precision Medicine Market is anticipated to register a 19.70% CAGR during 2026–2034. The market was valued at USD 0.88 billion in 2026 and is projected to reach USD 3.71 billion by 2034. Rising prevalence of cancer and rare genetic diseases, rapid adoption of next-generation sequencing platforms, and expanded public investment in national genomics programs are collectively driving demand across clinical diagnostic laboratories and hospital networks. Federal government-backed initiatives including the Australian Genomics Health Alliance and the National Health Genomics Policy Framework are accelerating infrastructure deployment across tier-one public health systems. Illumina Inc and Thermo Fisher Scientific Inc maintain strong distribution networks serving hospitals, research institutes, and biopharmaceutical developers across the country.
Increasing patient awareness of personalized treatment pathways, combined with declining sequencing costs, is expanding genomics access beyond specialist centers. Australia's strong research university infrastructure and national biobanks, including the Australian Genomics research cohort, are generating high-value datasets supporting drug discovery and pharmacogenomics applications. F. Hoffmann-La Roche Ltd and QIAGEN N.V. have intensified engagement with Australian academic institutions and biopharmaceutical companies through dedicated genomic workflow solutions and co-development support programs targeting precision oncology, reproductive health, and rare disease diagnosis applications.
Market Size & Forecast
|
Metric |
Details |
|---|---|
|
Market Size (2026) |
USD 0.88 Billion |
|
Market Size (2034) |
USD 3.71 Billion |
|
CAGR (2026–2034) |
19.70% |
|
Base Year |
2026 |
|
Historical Years |
2021–2025 |
|
Forecast Years |
2026–2034 |
The Australia Genomics Precision Medicine Market Size study values the industry at USD 0.88 billion in 2026, with the market projected to reach USD 3.71 billion by 2034 at a 19.70% CAGR. This trajectory significantly outpaces the broader Asia-Pacific diagnostics average, underpinned by aggressive government genomics funding, national cancer genomics programs, and accelerating biopharmaceutical adoption of precision diagnostics across oncology clinical trials.
Market Dynamics
Australia's genomics and precision medicine ecosystem is expanding at an exceptional rate as clinical adoption deepens across oncology, rare disease, and pharmacogenomics disciplines. National investment frameworks, declining sequencing costs, growing biopharmaceutical R&D activity, and increasing clinical validation of genomic biomarkers are collectively reinforcing the Australia Genomics Precision Medicine Market Growth across both public and private healthcare delivery channels.
|
Factor |
Type |
Specific Impact on Market |
Magnitude |
|---|---|---|---|
|
National Genomics Policy Framework investment |
Driver |
Expands clinical genomics infrastructure and sequencing capacity in public hospitals |
High |
|
Rising cancer incidence and precision oncology demand |
Driver |
Accelerates NGS adoption for tumor profiling and companion diagnostic testing |
High |
|
High cost of advanced sequencing platforms and reagents |
Restraint |
Limits adoption to well-funded metropolitan hospitals and research centers |
Medium |
|
Pharmacogenomics integration in drug development pipelines |
Opportunity |
Expands biopharmaceutical procurement of genotyping and sequencing solutions |
High |
|
Complex data governance and patient consent frameworks |
Challenge |
Slows genomic data sharing and cross-institutional research collaboration timelines |
Medium |
- Growth Drivers - National Investment and Oncology Expansion: Australia's Federal Government has committed sustained funding to the National Health Genomics Policy Framework and Genomics Health Futures Mission, directing over AUD 500 million toward clinical genomics integration. Major hospitals including Peter MacCallum Cancer Centre and Royal Melbourne Hospital are deploying Illumina and Roche sequencing platforms to support tumor genomic profiling, liquid biopsy, and companion diagnostic programs across oncology departments.
- Market Restraints - Cost Barriers and Workforce Gaps: High capital costs associated with next-generation sequencing instruments, bioinformatics infrastructure, and skilled genomics workforce recruitment remain significant barriers for mid-tier regional hospitals and smaller diagnostic laboratories. Reimbursement frameworks under the Medicare Benefits Schedule have not yet comprehensively incorporated many advanced genomic testing modalities, constraining broader clinical uptake beyond specialized academic medical centers.
- Market Opportunities - Pharmacogenomics and Biopharmaceutical R&D: Pharmacogenomics integration into Australian clinical trials and precision drug development pipelines presents a high-growth opportunity. Biopharmaceutical companies operating in Australia, including international sponsors running oncology trials, increasingly require companion diagnostic development and patient stratification services, driving procurement of QIAGEN and Thermo Fisher Scientific genomic workflow platforms.
- Industry Challenges - Data Governance and Interoperability: Complex patient consent requirements, jurisdictional data sovereignty regulations, and fragmented electronic health record systems across states and territories impede large-scale genomic data aggregation. Harmonizing data governance frameworks across New South Wales, Victoria, and Queensland health systems remains a critical prerequisite for maximizing clinical and research value from Australia's growing national genomic datasets.
Need Specific Data, Let’s Customize the Report for You
Request CustomizationMarket Trends
- Emerging Trends: Among the most significant Australia Genomics Precision Medicine Market Trends is the accelerating deployment of polygenic risk scoring tools for cardiovascular disease, type 2 diabetes, and hereditary cancer syndromes across population health screening programs. Australian state health departments are piloting population genomics screening cohorts targeting newborn and reproductive health applications through 2034.
- Technology Trends: Long-read sequencing platforms from Oxford Nanopore Technologies and continued improvements in Illumina's short-read throughput are expanding structural variant detection capabilities for rare disease and complex oncology applications. AI-driven clinical decision support tools integrating genomic, proteomic, and clinical phenotype data are entering deployment across Australia's leading academic medical centers and cancer specialist hospitals.
- Consumer / Buyer Trends: Clinical procurement teams at Australian hospitals increasingly demand end-to-end genomic workflow solutions encompassing sample preparation, sequencing, bioinformatics, and clinical reporting. Over 70% of Australia's major oncology centers now prioritize supplier technical support and turnaround time guarantees alongside reagent pricing when evaluating genomic platform contracts, reflecting growing reliance on integrated service delivery models.
- Regulatory Trends: The Therapeutic Goods Administration is progressively refining regulatory frameworks for in vitro diagnostic genomic tests, companion diagnostics, and direct-to-consumer genetic testing services. The Office of the Australian Information Commissioner's genomic privacy guidelines are shaping institutional data handling requirements, while MBS review processes are progressively broadening reimbursement eligibility for validated clinical genomic tests including BRCA1/2, tumor mutational burden, and NIPT applications.
Australia Genomics Precision Medicine Market Segment Analysis
Australia's genomics precision medicine market serves a diverse range of clinical applications and end-user institution types, each shaped by distinct procurement drivers, reimbursement dynamics, and genomic testing volume requirements. The Australia Genomics Precision Medicine Market Share is distributed across clinical application and end-user dimensions, with oncology and hospital segments commanding the largest portions.
By Clinical Application
- Genetic & Rare Diseases
- Oncology & Cancer Diagnostics
- Reproductive Health & NIPT
- Infectious Diseases
- Pharmacogenomics
- Complex Chronic Diseases
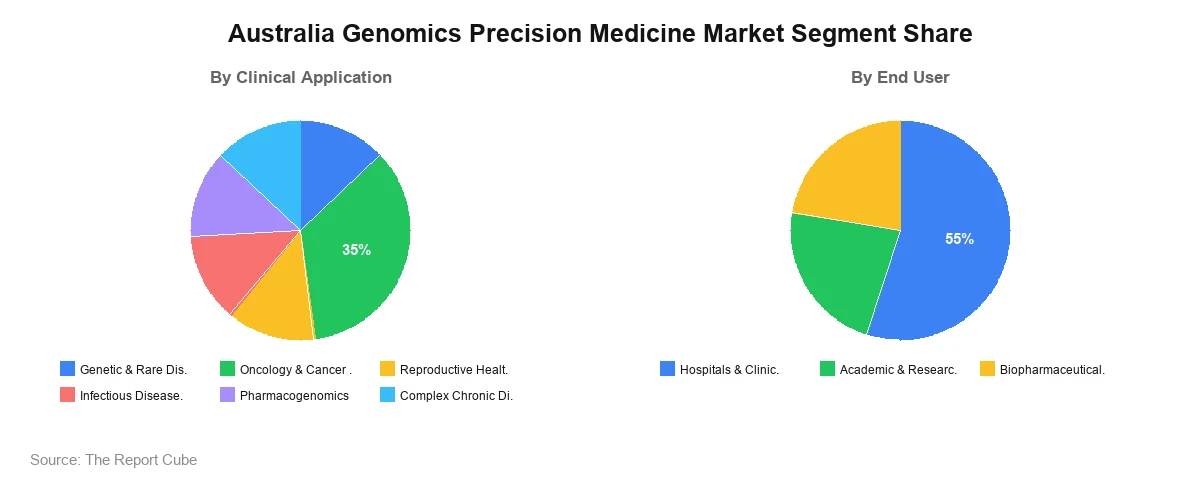
Oncology and cancer diagnostics leads the By Clinical Application segment, commanding an estimated 35% share in 2026. Illumina Inc and F. Hoffmann-La Roche Ltd supply the majority of NGS platforms and companion diagnostic solutions consumed across Australia's major cancer centers including Peter MacCallum, Chris O'Brien Lifehouse, and Princess Alexandra Hospital. Genetic and rare diseases represent approximately 22% of clinical application demand, served by Agilent Technologies and QIAGEN N.V. through panel-based sequencing and chromosomal microarray platforms. Reproductive health and NIPT collectively account for approximately 18%, with Roche and Illumina dominant in prenatal sequencing. Pharmacogenomics at 12%, infectious diseases at 8%, and complex chronic diseases at 5% complete the segment distribution, with pharmacogenomics exhibiting the fastest in-segment growth trajectory as biopharmaceutical drug development expands.
By End User
- Hospitals & Clinical Diagnostic Labs
- Academic & Research Institutes
- Biopharmaceutical
Hospitals and clinical diagnostic labs represent the dominant end-user segment at an estimated 55% market share in 2026. Major public hospital networks and private pathology groups including Sonic Healthcare and Australian Clinical Labs procure sequencing platforms primarily from Illumina Inc and Thermo Fisher Scientific Inc to support oncology, rare disease, and reproductive health testing pipelines. Academic and research institutes hold approximately 30% of end-user demand, representing the fastest-growing category as funding from NHMRC and the Medical Research Future Fund expands genomics research infrastructure at institutions including the University of Melbourne, Garvan Institute, and the ACRF International Cancer Genome Consortium. Biopharmaceutical companies account for approximately 15% of end-user procurement, sourcing genotyping, sequencing, and biomarker analysis services from Danaher Corporation and QIAGEN N.V. to support clinical trial stratification and companion diagnostic co-development activities.
Regional Analysis
|
Region |
Estimated Market Share |
Key Growth Factors |
Consumer Trends |
|---|---|---|---|
|
New South Wales |
34% |
Largest hospital network, Sydney Cancer Centre cluster, genomics research funding |
Premium NGS platform adoption, clinical trial genomics demand |
|
Victoria |
28% |
Peter MacCallum Cancer Centre, Garvan Institute, Walter and Eliza Hall Institute |
Precision oncology, rare disease genomics, biopharmaceutical R&D |
|
Queensland |
17% |
Queensland Genomics, expanding tropical disease and chronic disease genomics programs |
Infectious disease sequencing, population health genomics growth |
|
Western Australia |
13% |
Harry Perkins Institute, Telethon Kids Institute, rare disease research focus |
Rare genetic disease diagnostics, paediatric genomics demand |
|
Rest of Australia |
8% |
ACT genomics hubs, South Australian Health and Medical Research Institute |
Mixed clinical and research genomics activity |
- New South Wales - Accounting for approximately 34% of total market demand, New South Wales houses Australia's most extensive hospital genomics infrastructure. NSW Health Pathology's clinical genomics service, the Kinghorn Cancer Centre, and Sydney Genome Diagnostics drive high-volume NGS procurement from Illumina and Roche, while the NSW Genomics Collaborative Government Initiative is embedding genomic testing across oncology and rare disease clinical pathways statewide.
- Victoria - Victoria's 28% share reflects its exceptional concentration of precision oncology and medical research institutions. Peter MacCallum Cancer Centre, the Garvan Institute of Medical Research, and the Walter and Eliza Hall Institute of Medical Research generate significant bioinformatics and sequencing demand, with QIAGEN N.V. and Thermo Fisher Scientific particularly active across research and diagnostic procurement channels.
- Queensland - Queensland's 17% share is underpinned by the Queensland Genomics initiative and a growing focus on infectious disease and tropical medicine genomics. The Queensland Institute of Medical Research Berghofer and Gold Coast University Hospital are expanding clinical genomics programs, with Agilent Technologies and Danaher Corporation providing targeted sequencing and molecular diagnostic solutions.
- Western Australia - The Harry Perkins Institute of Medical Research and Telethon Kids Institute drive Western Australia's 13% share, with particularly strong focus on paediatric rare disease and population genomics. Illumina's long-standing partnerships with Perth-based research institutions support ongoing clinical genomic sequencing and newborn screening program expansion.
- Rest of Australia - ACT, South Australia, Tasmania, and the Northern Territory collectively account for 8% of market demand. The South Australian Health and Medical Research Institute (SAHMRI) and Australian National University genomics programs contribute research-driven procurement, with growth expected as telegenomics and decentralized testing models extend precision medicine access to regional populations through 2034.
Market Share & Competitive Landscape
The Australia Genomics Precision Medicine Market's competitive landscape is characterized by a small number of global instrument and reagent manufacturers supplying the full spectrum of clinical and research genomics workflows. Key players compete primarily on platform throughput, assay portfolio breadth, bioinformatics integration capabilities, and regulatory compliance credentials.
|
Company |
Competitive Strength |
Primary Segment Served |
|---|---|---|
|
Illumina Inc |
Market-leading NGS platform portfolio, dominant short-read sequencing installed base |
Oncology, rare disease, reproductive health, research |
|
Thermo Fisher Scientific Inc |
Broad genomics workflow integration, Ion Torrent platform, clinical IVD portfolio |
Hospitals, clinical labs, biopharmaceutical |
|
F. Hoffmann-La Roche Ltd |
Companion diagnostics, PCR/ddPCR, clinical oncology genomics leadership |
Oncology diagnostics, clinical pathology |
|
Agilent Technologies Inc |
Targeted capture panels, microarray platforms, liquid biopsy solutions |
Rare disease, academic research, oncology |
|
QIAGEN N.V. |
Sample preparation, molecular diagnostic assays, bioinformatics platforms |
Clinical labs, pharmacogenomics, infectious disease |
|
Danaher Corporation |
Integrated life sciences tools, Beckman Coulter diagnostics, cytogenetics |
Hospitals, research institutes, biopharmaceutical |
|
Others |
Emerging NGS players, specialized assay providers |
Research and niche clinical applications |
Key Companies in the Australia Genomics Precision Medicine Market
Illumina Inc
Illumina Inc, headquartered in San Diego, California, USA, is the world's leading provider of next-generation sequencing instruments, reagents, and bioinformatics solutions. In 2025, Illumina strengthened its Australian market presence by expanding certified service partnerships with NSW Health Pathology and Peter MacCallum Cancer Centre, supporting clinical oncology sequencing program scale-up. Its NovaSeq X Series and clinical IVD portfolio provide competitive depth across Australia's hospital, research, and reproductive health genomics segments.
F. Hoffmann-La Roche Ltd
F. Hoffmann-La Roche Ltd, headquartered in Basel, Switzerland, operates a global diagnostics division that leads companion diagnostic development and oncology genomics. In 2025, Roche expanded its VENTANA and cobas genomics portfolio within Australian oncology networks, supporting tumor mutational burden, MSI, and BRCA biomarker testing at major cancer specialist hospitals. Its integrated molecular pathology platform positions Roche as a structurally critical supplier across hospital clinical diagnostic laboratories and precision oncology programs nationally.
Recent Developments
|
Year |
Company |
Development |
|---|---|---|
|
2025 |
Illumina Inc |
Announced expanded partnership with NSW Health Pathology to scale NovaSeq X clinical sequencing capacity for oncology and rare disease programs |
|
2025 |
F. Hoffmann-La Roche Ltd |
Extended cobas genomics platform deployment across Australian oncology centers supporting MSI, TMB, and BRCA companion diagnostic testing |
|
2025 |
Thermo Fisher Scientific Inc |
Launched Ion Torrent Genexus System upgrades targeting clinical diagnostic labs in Victoria and Queensland with streamlined oncology panel workflows |
Future Outlook
The Australia Genomics Precision Medicine Market Forecast projects the market reaching USD 3.71 billion by 2034, expanding at a 19.70% CAGR through the forecast period. Sustained growth in clinical genomics adoption across hospital oncology services, the scaling of national rare disease and newborn genomic screening programs, and expanding biopharmaceutical investment in Australian clinical trials will collectively drive ingredient and platform demand. Illumina Inc, Roche, and Thermo Fisher Scientific are expected to deepen market penetration through localized clinical support programs, expanded MBS-reimbursed test portfolios, and integrated bioinformatics service offerings aligned with Australia's genomics policy priorities through 2034.
Technological advancement in long-read sequencing, AI-assisted variant interpretation, and decentralized genomic testing will progressively expand the addressable market beyond metropolitan specialist centers. Sustainable clinical adoption will increasingly require regulatory harmonization of genomic IVD frameworks under the TGA's evolving medical devices pathway, stronger national genomic data governance standards, and ongoing NHMRC and Medical Research Future Fund investment in translational genomics infrastructure. These regulatory and technological factors will collectively shape the competitive and commercial landscape of the Australia Genomics Precision Medicine Market through 2034.
Australia Genomics Precision Medicine Market Report Coverage
This Australia Genomics Precision Medicine Market Report covers all critical dimensions of the market from 2026 through 2034, providing stakeholders with a complete intelligence framework for strategic planning, investment evaluation, and competitive positioning.
|
Report Attribute |
Details |
|---|---|
|
Market Name |
Australia Genomics Precision Medicine Market |
|
Market Size (2026) |
USD 0.88 Billion |
|
Market Size (2034) |
USD 3.71 Billion |
|
Forecast Period |
2026–2034 |
|
CAGR |
19.70% |
|
Base Year |
2026 |
|
Historical Years |
2021–2025 |
|
Forecast Years |
2026–2034 |
|
Segments Covered |
By Product, By Technology, By Clinical Application, By End-User |
|
Regions Covered |
New South Wales, Victoria, Queensland, Western Australia, Rest of Australia |
|
Key Companies |
Illumina Inc, Thermo Fisher Scientific Inc, F. Hoffmann-La Roche Ltd, Agilent Technologies Inc, QIAGEN N.V., Danaher Corporation, Others |
|
Report Format |
PDF, Excel, PPT |
|
Customization |
Available as per client requirements |
Why Choose This Australia Genomics Precision Medicine Market Report?
- Comprehensive coverage of Australia's rapidly expanding genomics and precision medicine sector across all clinical and research segments.
- Accurate market sizing from USD 0.88 billion in 2026 through the 2034 forecast at 19.70% CAGR.
- Detailed segmentation by six clinical application categories and three end-user institution types.
- State-level regional insights covering New South Wales, Victoria, Queensland, Western Australia, and Rest of Australia with share estimates.
- Competitive profiling of six leading global genomics platform and diagnostics suppliers operating in Australia.
- Analysis of pharmacogenomics, long-read sequencing, and AI-assisted diagnostics trends reshaping clinical procurement decisions.
- Forecast data supporting capital planning, partnership strategy, and market entry decision-making through 2034.
- Research aligned with Australia's National Health Genomics Policy Framework and Genomics Health Futures Mission objectives.
Table of Contents
- Introduction
- Objective of the Study
- Product Definition
- Market Segmentation
- Study Variables
- Research Methodology
- Secondary Data Points
- Companies Interviewed
- Primary Data Points
- Breakdown of Primary Interviews
- Secondary Data Points
- Executive Summary
- Market Dynamics
- Drivers
- Challenges
- Opportunity Assessment
- Recent Trends and Developments
- Policy and Regulatory Landscape
- Australia Genomics Precision Medicine Market Overview and Forecast Analysis (2021-2034)
- Market Size, By Value, By Growth Rate (CAGR/USD Billions)
- Demand – Supply Trends
- Market Share, By Product
- Consumables & Reagents
- Instruments & Equipment
- Services
- Software
- Market Share, By Technology
- Next-Generation Sequencing
- Polymerase Chain Reaction
- Microarrays
- Sanger Sequencing
- Other Multiomics
- Market Share, By Clinical Application
- Genetic & Rare Diseases
- Oncology & Cancer Diagnostics
- Reproductive Health & NIPT
- Infectious Diseases
- Pharmacogenomics
- Complex Chronic Diseases
- Market Share, By End-User
- Hospitals & Clinical Diagnostic Labs
- Academic & Research Institutes
- Biopharmaceutical
- Market Share, By Region
- New South Wales
- Victoria
- Queensland
- Western Australia
- Rest of Australia
- Market Share, By Competitors
- Competition Characteristics
- Revenue Shares
- Consumables & Reagents Australia Genomics Precision Medicine Market Overview, 2021-2034F
- By Value (USD Million)
- By Technology – Market Size & Forecast 2021-2034, USD Million
- Next-Generation Sequencing
- Polymerase Chain Reaction
- Microarrays
- Sanger Sequencing
- Other Multiomics
- Instruments & Equipment Australia Genomics Precision Medicine Market Overview, 2021-2034F
- By Value (USD Million)
- By Technology – Market Size & Forecast 2021-2034, USD Million
- Next-Generation Sequencing
- Polymerase Chain Reaction
- Microarrays
- Sanger Sequencing
- Other Multiomics
- Services Australia Genomics Precision Medicine Market Overview, 2021-2034F
- By Value (USD Million)
- By Technology – Market Size & Forecast 2021-2034, USD Million
- Next-Generation Sequencing
- Polymerase Chain Reaction
- Microarrays
- Sanger Sequencing
- Other Multiomics
- Software Australia Genomics Precision Medicine Market Overview, 2021-2034F
- By Value (USD Million)
- By Technology – Market Size & Forecast 2021-2034, USD Million
- Next-Generation Sequencing
- Polymerase Chain Reaction
- Microarrays
- Sanger Sequencing
- Other Multiomics
- Competitive Outlook (Company Profile - Partial List)
- Illumina Inc
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Thermo Fisher Scientific Inc
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- F. Hoffmann-La Roche Ltd
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Agilent Technologies Inc
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- QIAGEN N.V.
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Danaher Corporation
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Others
- Illumina Inc
- Contact Us & Disclaimer
Top Key Players & Market Share Outlook
- Illumina Inc
- Thermo Fisher Scientific Inc
- F. Hoffmann-La Roche Ltd
- Agilent Technologies Inc
- QIAGEN N.V.
- Danaher Corporation
- Others
Frequently Asked Questions