
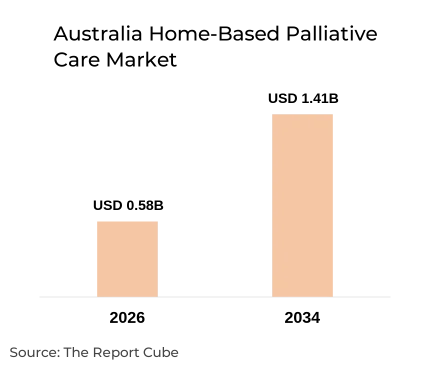
Build Your Custom Market Intelligence Report
Customize Your ReportKey Takeaways
- Australia Home-Based Palliative Care Market valued at USD 0.58 billion in 2026, reflecting strong structural demand.
- Market projected to reach USD 1.41 billion by 2034, expanding at an 11.70% CAGR through the forecast period.
- A comprehensive Australia Home-Based Palliative Care Market Analysis identifies ageing demographics and chronic disease burden as primary growth catalysts.
- Geriatric palliative care (65+) leads the By Age Group segment, driven by Australia's rapidly ageing population base.
- Oncology remains the dominant disease profile segment, commanding the largest patient volume share across home care settings.
- Non-oncology palliative care is the fastest-growing disease profile segment, driven by rising chronic and cardiac disease prevalence.
- Silver Chain Group, Banksia Palliative Care Service, Home Instead Australia, and Australian Unity lead service delivery nationally.
- Telehealth integration and federal aged care funding reforms are reshaping care delivery models across the sector.
Market Overview
The Australia Home-Based Palliative Care Market is anticipated to register an 11.70% CAGR during 2026–2034, expanding from USD 0.58 billion in 2026 to USD 1.41 billion by 2034. Rising prevalence of life-limiting illnesses, accelerating aged care sector reforms, and sustained federal investment in community-based care infrastructure collectively underpin this growth trajectory. Government-supported programs including the National Palliative Care Strategy 2018 and Aged Care at Home packages have established foundational frameworks enabling service providers such as Silver Chain Group and Australian Unity to scale home-based palliative delivery efficiently.
Patient and family preference for home-based end-of-life care continues shifting care volumes away from hospital and residential settings. Australia's strategic investment in integrated care coordination, combined with growing telehealth adoption and nurse practitioner-led models, positions the domestic market as one of Asia-Pacific's most advanced home palliative ecosystems. Banksia Palliative Care Service and Home Instead Australia have deepened engagement with Commonwealth-funded care programs, while technology-enabled triage systems and multidisciplinary care teams are enhancing patient outcomes across metropolitan and regional geographies.
Market Size & Forecast
|
Metric |
Details |
|---|---|
|
Market Size (2026) |
USD 0.58 Billion |
|
Market Size (2034) |
USD 1.41 Billion |
|
CAGR (2026–2034) |
11.70% |
|
Base Year |
2026 |
|
Historical Years |
2021–2025 |
|
Forecast Years |
2026–2034 |
The Australia Home-Based Palliative Care Market Size study values the industry at USD 0.58 billion in 2026, with projections reaching USD 1.41 billion by 2034 at an 11.70% CAGR. This trajectory significantly outpaces the global home palliative care average, driven by federal aged care funding reform, accelerating geriatric population growth, and expanding telehealth-enabled care delivery models reducing hospital dependency across all Australian states.
Market Dynamics
Australia's home-based palliative care sector is experiencing structural expansion as demographic pressure from ageing populations, rising chronic disease burden, and systemic health policy reform converge. The Australia Home-Based Palliative Care Market Growth is primarily driven by government-mandated aged care reforms, patient-centered care preferences, and the increasing integration of telehealth into palliative service delivery models across metropolitan and regional communities.
|
Factor |
Type |
Specific Impact on Market |
Magnitude |
|---|---|---|---|
|
Ageing population growth |
Driver |
Directly expands geriatric palliative care demand across home settings |
High |
|
Aged Care Act reform and funding expansion |
Driver |
Increases Commonwealth-funded service delivery capacity for home-based providers |
High |
|
Hospital avoidance policy incentives |
Opportunity |
Redirects end-of-life care volumes toward community and home settings |
High |
|
Regional and rural care workforce shortages |
Challenge |
Limits service reach in non-metropolitan areas and restricts care hours |
Medium |
|
Telehealth integration in palliative delivery |
Trend |
Expands care access and reduces clinician travel burden in remote communities |
Medium |
- Growth Drivers - Aged Care Reform and Demographic Pressure: Australia's population aged 65 and above is projected to exceed 22% of total population by 2034. The Aged Care Act 2024 reforms, combined with increased Home Care Package allocations, are enabling Silver Chain Group and Australian Unity to expand multidisciplinary home palliative teams servicing end-of-life patients across all major states.
- Market Restraints - Palliative Workforce Capacity Constraints: Specialist palliative care nursing and physician shortages remain a persistent structural barrier. Rural and regional communities face particular access inequity, with provider coverage gaps limiting the ability of organizations including Banksia Palliative Care Service to meet rising referral volumes outside metropolitan catchment zones.
- Market Opportunities - Hospital Avoidance and Care Coordination Funding: Federal investment in hospital avoidance programs and integrated care coordination is creating direct funding pathways for home palliative providers. Home Instead Australia and Australian Unity stand to capture growing care hours as health authorities redirect chronic disease and end-of-life management toward community-based delivery models.
- Industry Challenges - Carer Burden and Informal Support Dependency: Home-based palliative models rely substantially on family and informal carer availability. High carer burden, carer mental health deterioration, and demographic shifts reducing household care availability are collectively constraining sustainable service delivery without increased formal clinical support hours from providers.
Need Specific Data, Let’s Customize the Report for You
Request CustomizationMarket Trends
- Emerging Trends: Among the most significant Australia Home-Based Palliative Care Market Trends is the rapid expansion of nurse practitioner-led home palliative models. Specialist nurses are increasingly authorized to prescribe palliative medications independently, extending care reach into underserviced communities and evening hours without requiring on-call physician attendance.
- Technology Trends: Remote patient monitoring platforms, AI-assisted symptom triage tools, and digital care coordination software are entering mainstream adoption among Australian home palliative providers. Silver Chain Group has piloted predictive analytics platforms enabling proactive pain management and anticipatory prescribing, reducing emergency presentations among end-of-life home care patients.
- Consumer / Buyer Trends: Patient and family preference for death at home continues strengthening, with surveys consistently indicating over 70% of Australians prefer home as their preferred place of death. Care purchasers - including Commonwealth Home Support Program coordinators and aged care case managers - increasingly specify palliative-competent providers in procurement frameworks and care plan referrals.
- Regulatory Trends: The Aged Care Act 2024 introduces new quality standards mandating documented palliative care planning for all aged care recipients. Voluntary Assisted Dying legislation, now enacted across all six Australian states, is expanding the regulatory and clinical interface between palliative care providers and end-of-life medical decision frameworks, reshaping care protocols for organizations operating home palliative services.
Australia Home-Based Palliative Care Market Segment Analysis
The Australia Home-Based Palliative Care Market serves distinct patient cohorts and disease profiles, each characterized by specific care intensity requirements, funding pathways, and clinical staffing models. Segmentation by age group and disease profile reveals diverging growth trajectories and service design priorities across the national market.
By Age Group
- Geriatric Palliative Care (65+)
- Adult Palliative Care (18–64)
- Pediatric & Adolescent Palliative Care (0–17)
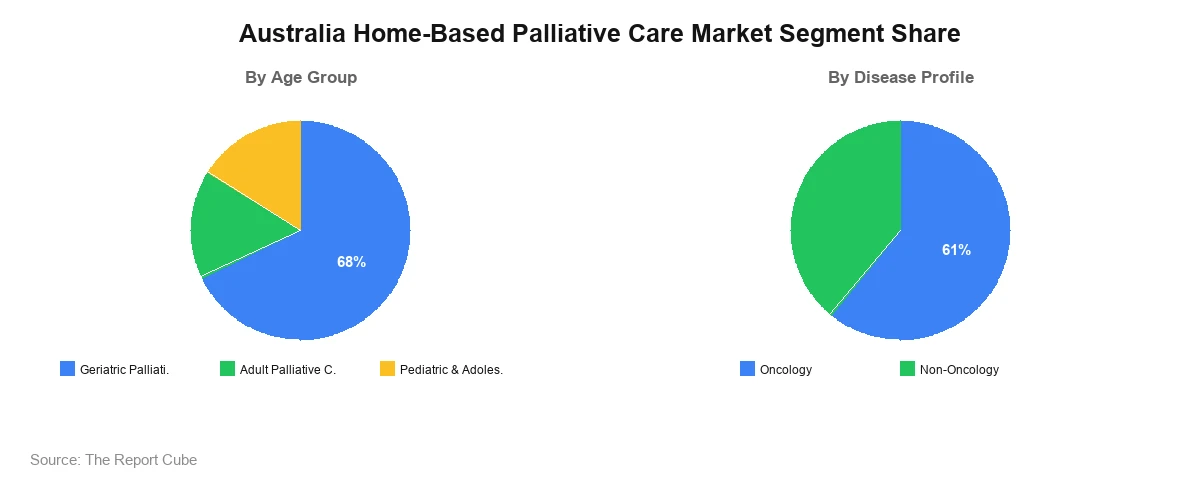
Geriatric palliative care (65+) dominates the By Age Group segment, commanding an estimated Australia Home-Based Palliative Care Market Share of 68% in 2026. Silver Chain Group and Australian Unity are primary service providers in this cohort, delivering Commonwealth Home Care Package-funded nursing, allied health, and personal care to aged patients with life-limiting diagnoses. Adult palliative care (18–64) accounts for approximately 24% of segment demand, serviced through state-funded programs and condition-specific pathways. Banksia Palliative Care Service provides specialized support to adult patients with cancer and non-oncology conditions across its Western Australian service area. Pediatric and adolescent palliative care (0–17) represents approximately 8% of volume, delivered through highly specialized paediatric palliative teams associated with children's hospital networks and home nursing organizations operating under state government contracts.
By Disease Profile
- Oncology
- Non-Oncology
Oncology palliative care retains the dominant disease profile position, accounting for an estimated 61% of home-based palliative care demand in 2026. Cancer diagnoses remain the leading driver of palliative referrals, with Silver Chain Group, Banksia Palliative Care Service, and Australian Unity providing integrated oncology palliative nursing and symptom management across major metropolitan areas. Non-oncology palliative care - encompassing cardiac failure, chronic obstructive pulmonary disease, dementia, and neurological conditions - holds approximately 39% of the disease profile segment and is expanding at a faster rate as chronic disease incidence rises. Home Instead Australia has expanded its non-oncology care model to address this growing cohort through trained companion care and nursing coordination services.
Regional Analysis
|
Region |
Estimated Market Share |
Key Growth Factors |
Consumer Trends |
|---|---|---|---|
|
New South Wales |
32% |
Largest aged population base, dense metro provider network, Commonwealth funding concentration |
High geriatric oncology demand, preference for home death settings |
|
Victoria |
27% |
Advanced palliative care policy framework, Voluntary Assisted Dying uptake |
Growing non-oncology and dementia care demand |
|
Queensland |
18% |
Regional expansion programs, ageing coastal retiree population |
Rising adult palliative and aged care-at-home demand |
|
Western Australia |
14% |
Banksia service network strength, state-funded palliative program investment |
Regional access priority, cancer and chronic disease care |
|
Rest of Australia |
9% |
South Australia, Tasmania, ACT, NT programs; rural telehealth expansion |
Remote palliative access demand, Indigenous community palliative care |
- New South Wales - Accounting for approximately 32% of total national market demand, New South Wales hosts the largest concentration of aged care recipients and palliative care referral volumes. Sydney-based multidisciplinary palliative teams and Commonwealth-funded Home Care Package providers service dense metropolitan demand, with Australian Unity and Home Instead Australia maintaining substantial service footprints across the greater Sydney metropolitan and Hunter regions.
- Victoria - Victoria's advanced policy environment, including its pioneering Voluntary Assisted Dying legislation enacted in 2019 and subsequent program expansion, has elevated integration between palliative and end-of-life medical services. The state's 27% market share is supported by strong public-private palliative collaboration and expanding non-oncology care demand across Melbourne's ageing suburban population catchments.
- Queensland - Holding approximately 18% market share, Queensland's growth is driven by a rapidly ageing coastal retiree demographic across Gold Coast, Sunshine Coast, and regional centers. State-funded community palliative programs and expanding regional telehealth platforms are enabling providers to extend care reach into geographically dispersed patient populations.
- Western Australia - Contributing approximately 14% of national demand, Western Australia benefits from Banksia Palliative Care Service's established regional presence and state government-funded palliative programs. The Perth metropolitan area anchors service volumes, while regional cancer and chronic disease prevalence drives demand for remote home palliative support across the state's extensive geographic footprint.
- Rest of Australia - Comprising South Australia, Tasmania, the Australian Capital Territory, and the Northern Territory, this segment accounts for approximately 9% of market demand. Indigenous community palliative care programs, telehealth-enabled remote delivery, and state government-funded specialist nursing teams are gradually expanding coverage across underserviced rural and remote communities.
Market Share & Competitive Landscape
The Australia Home-Based Palliative Care Market's competitive structure is shaped by a combination of large not-for-profit service organizations, Commonwealth-funded aged care providers, and specialist palliative care networks. Providers compete across care quality, geographic coverage, funding model alignment, clinical staffing capability, and telehealth integration depth.
|
Company |
Competitive Strength |
Primary Segment Served |
|---|---|---|
|
Silver Chain Group |
National scale, integrated home nursing and palliative coordination, telehealth capability |
Geriatric, oncology, and adult palliative care |
|
Banksia Palliative Care Service |
Specialist palliative expertise, Western Australia regional network, state program alignment |
Oncology and non-oncology adult and geriatric palliative |
|
Home Instead Australia |
Companion and personal care model, non-oncology and dementia focus, national franchise network |
Non-oncology, geriatric, and adult palliative care |
|
Australian Unity |
Integrated health and aged care model, Commonwealth Home Care Package delivery |
Geriatric oncology and chronic disease palliative care |
|
Others |
Regional and community organizations, hospital-affiliated palliative teams, faith-based providers |
All segments across state-funded programs |
Key Companies in the Australia Home-Based Palliative Care Market
Silver Chain Group
Silver Chain Group, headquartered in Perth, Western Australia, is one of Australia's largest not-for-profit home care and health service organizations, supporting over 100,000 clients annually. In 2025, Silver Chain expanded its palliative care telehealth program, enabling remote symptom monitoring and after-hours nursing support for home-based patients across Western Australia and South Australia. Its integrated palliative model combining clinical nursing, allied health, and digital care coordination positions it as the sector's leading full-service provider.
Banksia Palliative Care Service
Banksia Palliative Care Service, based in Western Australia, operates as a specialist not-for-profit provider delivering home and community-based palliative care to adults with life-limiting illnesses. In 2024, Banksia strengthened its community outreach programs and expanded its trained volunteer workforce supporting patients and families across Perth's metropolitan area. Its clinical specialization, multidisciplinary team structure, and focus on patient dignity and family support distinguish it as a trusted regional palliative care provider.
Recent Developments
|
Year |
Company |
Development |
|---|---|---|
|
2025 |
Silver Chain Group |
Expanded palliative care telehealth program enabling remote symptom monitoring and after-hours nursing support across Western Australia and South Australia |
Future Outlook
The Australia Home-Based Palliative Care Market Forecast projects sustained expansion to USD 1.41 billion by 2034, at an 11.70% CAGR through the forecast period. Growing geriatric oncology and non-oncology care volumes, increasing Commonwealth Home Care Package allocations, and the progressive hospital avoidance policy direction will sustain demand. Silver Chain Group, Australian Unity, and Home Instead Australia are expected to scale capacity through workforce investment, telehealth deployment, and expanded care coordination service models aligned with federal aged care reform priorities.
Technological advancement in remote monitoring, AI-assisted symptom triage, and digital care planning platforms will increasingly differentiate providers serving the Australia Home-Based Palliative Care Market through 2034. Regulatory alignment with the Aged Care Act 2024 quality standards, Voluntary Assisted Dying frameworks, and evolving palliative competency requirements for care workers will raise service delivery benchmarks nationally. Providers investing in clinical workforce development, Indigenous community care outreach, and telehealth-enabled regional access will capture the highest growth opportunities across the forecast period.
Australia Home-Based Palliative Care Market Report Coverage
This Australia Home-Based Palliative Care Market Report covers the full forecast period 2026–2034, providing market sizing, segmentation, regional breakdown, competitive profiling, and strategic analysis for professional buyers, investors, and healthcare planners.
|
Report Attribute |
Details |
|---|---|
|
Market Name |
Australia Home-Based Palliative Care Market |
|
Market Size (2026) |
USD 0.58 Billion |
|
Market Size (2034) |
USD 1.41 Billion |
|
Forecast Period |
2026–2034 |
|
CAGR |
11.70% |
|
Base Year |
2026 |
|
Historical Years |
2021–2025 |
|
Forecast Years |
2026–2034 |
|
Segments Covered |
By Service, By Age Group, By Disease Profile |
|
Regions Covered |
New South Wales, Victoria, Queensland, Western Australia, Rest of Australia |
|
Key Companies |
Silver Chain Group, Banksia Palliative Care Service, Home Instead Australia, Australian Unity, Others |
|
Report Format |
PDF, Excel, PPT |
|
Customization |
Available as per client requirements |
Why Choose This Australia Home-Based Palliative Care Market Report?
- Comprehensive coverage of Australia's rapidly expanding home-based palliative care service market through 2034.
- Accurate market sizing from USD 0.58 billion in 2026 to USD 1.41 billion at 11.70% CAGR.
- Detailed segmentation by age group and disease profile with share percentages and growth analysis.
- State-level regional insights covering New South Wales, Victoria, Queensland, Western Australia, and Rest of Australia.
- Competitive profiling of leading national palliative care providers including Silver Chain Group and Australian Unity.
- Analysis of telehealth adoption, nurse practitioner-led care models, and digital palliative care delivery trends.
- Forecast data supporting healthcare investment, service planning, and government program alignment decisions.
- Research aligned with Australia's Aged Care Act 2024 reforms and National Palliative Care Strategy objectives.
Table of Contents
- Introduction
- Objective of the Study
- Product Definition
- Market Segmentation
- Study Variables
- Research Methodology
- Secondary Data Points
- Companies Interviewed
- Primary Data Points
- Breakdown of Primary Interviews
- Secondary Data Points
- Executive Summary
- Market Dynamics
- Drivers
- Challenges
- Opportunity Assessment
- Recent Trends and Developments
- Policy and Regulatory Landscape
- Australia Home-Based Palliative Care Market Overview and Forecast Analysis (2021-2034)
- Market Size, By Value, By Growth Rate (CAGR/USD Billions)
- Demand – Supply Trends
- Market Share, By Service
- Specialist Medical & Nursing Care
- Allied Health Services
- Psychosocial & Spiritual Support
- Personal Care & Domestic Assistance
- Respite Care
- Market Share, By Age Group
- Geriatric Palliative Care (65+)
- Adult Palliative Care (18-64)
- Pediatric & Adolescent Palliative Care (0-17)
- Market Share, By Disease Profile
- Oncology
- Non-Oncology
- Market Share, By Region
- New South Wales
- Victoria
- Queensland
- Western Australia
- Rest of Australia
- Market Share, By Competitors
- Competition Characteristics
- Revenue Shares
- Specialist Medical & Nursing Care Australia Home-Based Palliative Care Market Overview, 2021-2034F
- By Value (USD Million)
- By Age Group – Market Size & Forecast 2021-2034, USD Million
- Geriatric Palliative Care (65+)
- Adult Palliative Care (18-64)
- Pediatric & Adolescent Palliative Care (0-17)
- Allied Health Services Australia Home-Based Palliative Care Market Overview, 2021-2034F
- By Value (USD Million)
- By Age Group – Market Size & Forecast 2021-2034, USD Million
- Geriatric Palliative Care (65+)
- Adult Palliative Care (18-64)
- Pediatric & Adolescent Palliative Care (0-17)
- Psychosocial & Spiritual Support Australia Home-Based Palliative Care Market Overview, 2021-2034F
- By Value (USD Million)
- By Age Group – Market Size & Forecast 2021-2034, USD Million
- Geriatric Palliative Care (65+)
- Adult Palliative Care (18-64)
- Pediatric & Adolescent Palliative Care (0-17)
- Personal Care & Domestic Assistance Australia Home-Based Palliative Care Market Overview, 2021-2034F
- By Value (USD Million)
- By Age Group – Market Size & Forecast 2021-2034, USD Million
- Geriatric Palliative Care (65+)
- Adult Palliative Care (18-64)
- Pediatric & Adolescent Palliative Care (0-17)
- Respite Care Australia Home-Based Palliative Care Market Overview, 2021-2034F
- By Value (USD Million)
- By Age Group – Market Size & Forecast 2021-2034, USD Million
- Geriatric Palliative Care (65+)
- Adult Palliative Care (18-64)
- Pediatric & Adolescent Palliative Care (0-17)
- Competitive Outlook (Company Profile - Partial List)
- Silver Chain Group
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Banksia Palliative Care Service
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Home Instead Australia
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Australian Unity
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Others
- Silver Chain Group
- Contact Us & Disclaimer
Top Key Players & Market Share Outlook
- Silver Chain Group
- Banksia Palliative Care Service
- Home Instead Australia
- Australian Unity
- Others
Frequently Asked Questions