
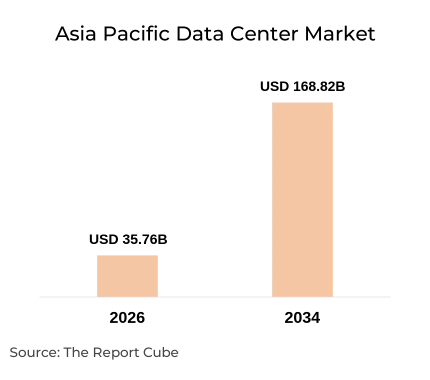
Build Your Custom Market Intelligence Report
Customize Your ReportKey Takeaways
- Asia Pacific Data Center Market is valued at USD 35.76 billion in 2026.
- The market is projected to reach USD 168.82 billion by 2034, expanding at a CAGR of 21.41%.
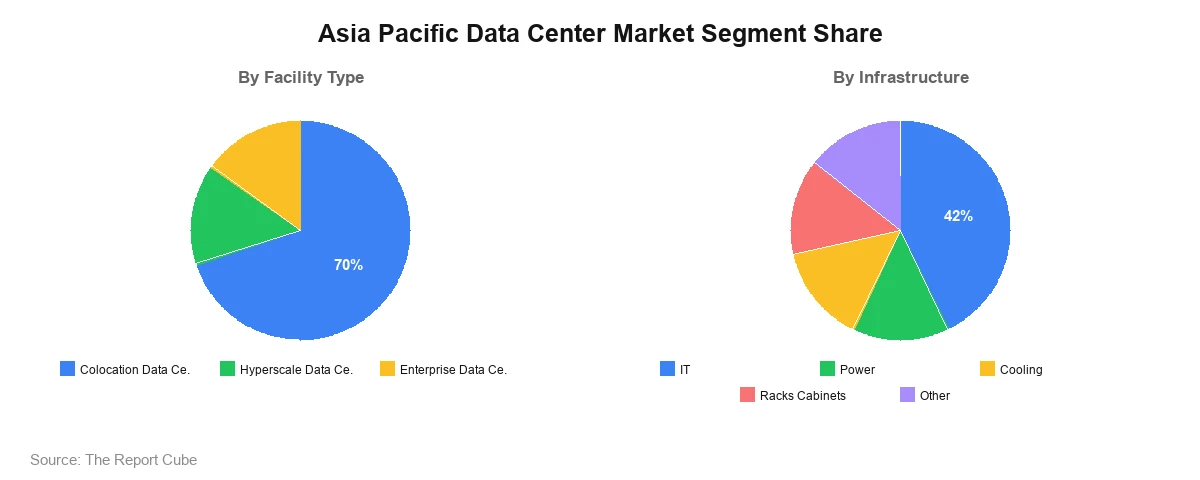
- Colocation data centers lead the facility type segment with a 70% share in 2026.
- IT infrastructure leads the infrastructure segment with a 42% share in 2026.
- China leads the country-level market with a 34% share in 2026.
- Amazon Web Services, Equinix, Alibaba Cloud, AirTrunk, NTT and Google are among the key players.
- Higher-density AI infrastructure and sustainable data centre design are important market trends.
Market Overview
A data center is a purpose-built facility that houses servers, storage, networking equipment and the power, cooling and security systems needed to run them. Operators deliver capacity through colocation, hyperscale and enterprise models, supporting cloud computing, artificial intelligence workloads, digital payments, streaming and government systems across commercial and public sector organizations.
The Asia Pacific Data Center Market is valued at USD 35.76 billion in 2026, and this Asia Pacific Data Center Market Analysis identifies cloud, AI and digital services as central demand sources. According to the ASEAN Guide for Sustainable Data Centre Development, Southeast Asia’s digital economy is projected to exceed USD 1 trillion by 2030.
Organizations adopt data center capacity to secure reliable computing, data residency compliance and low-latency connectivity. Higher-density AI infrastructure and sustainable design are reshaping facility planning across the region. Operators increasingly weigh power availability, cooling efficiency and grid access when selecting sites. The market is projected to grow at a CAGR of 21.41% during 2026–2034.
Asia Pacific Data Center Market Dynamics
Demand for Asia Pacific data center capacity depends on AI workload expansion, cloud adoption, data localisation requirements and enterprise digitalisation. Supply is shaped by electricity access, grid connection timelines, equipment availability and cooling technology, while pricing and competition reflect site availability, power costs and the pace of hyperscale commissioning.
|
Factor |
Type |
Specific Impact on Market |
Magnitude |
|---|---|---|---|
|
AI and cloud workload expansion |
Driver |
Raises requirements for high-density computing, storage and networking capacity |
High |
|
Data localisation and digitalisation |
Driver |
Strengthens demand for locally hosted computing and storage |
Medium–High |
|
Hyperscale campuses and AI-ready infrastructure |
Opportunity |
Creates openings for operators and suppliers of high-density IT and electrical systems |
High |
|
Energy-efficient power and cooling |
Opportunity |
Supports demand for efficient power distribution, liquid cooling and energy monitoring |
Medium–High |
|
Grid connection and equipment delays |
Challenge |
Postpones commissioning and raises project costs |
High |
|
Cooling and water pressures |
Challenge |
Adds operating complexity as rack density rises |
Medium–High |
|
Higher-density AI and sustainable design |
Trend |
Drives redesign of power, cooling and rack infrastructure |
High |
Asia Pacific Data Center Market Growth Drivers
Asia Pacific Data Center Market Growth is closely linked to AI and cloud workloads. According to the IEA’s 2026 report, global data centre electricity consumption rose 17% in 2025, while AI-focused data centres recorded a 50% increase. These trends raise requirements for high-density computing, storage and networking capacity across the region.
Data localisation and regional digitalisation form a second driver. The ASEAN Guide for Sustainable Data Centre Development notes that expanding AI, e-commerce and financial technology increase digital infrastructure needs, while data-sovereignty requirements can strengthen demand for locally hosted computing and storage, which can support colocation and hyperscale requirements across several economies.
Asia Pacific Data Center Market Opportunities
Hyperscale campuses and AI-ready infrastructure present a clear opportunity. CBRE’s 2026 Asia-Pacific Data Centre Trends and Outlook states that AI demand is driving new development, with technology companies planning substantial increases in AI capital expenditure, which creates openings for hyperscale operators, colocation providers and suppliers of high-density IT equipment and electrical systems.
Energy-efficient power and cooling technologies offer a second opening. The ASEAN guide links rising rack power density to pressure on electricity grids and cooling systems and recommends efficiency measurement, renewable-energy integration, water management and cooling innovation, creating opportunities for suppliers of efficient power distribution, liquid cooling, heat management and energy-monitoring systems.
Asia Pacific Data Center Industry Challenges
Electricity availability and grid connection delays constrain expansion. According to the IEA’s 2026 analysis, grid-connection queues, shortages of electrical equipment and planning delays are limiting new data centre capacity, which can postpone commissioning, raise project costs and slow the pace at which operators bring new facilities online across the region.
Rising cooling requirements and environmental pressures add operating complexity. The ASEAN guide states that higher rack power density strains electricity grids, cooling systems and water resources, so operators must balance energy efficiency, cooling performance and local water availability while maintaining reliability and meeting sustainability targets across facilities in the region.
Need Specific Data, Let’s Customize the Report for You
Request CustomizationAsia Pacific Data Center Market Trends
Among the most visible Asia Pacific Data Center Market Trends is the shift toward higher-density AI facilities. According to the IEA’s 2026 report, AI server power density rose roughly elevenfold between 2020 and 2025, with a further fourfold increase projected by 2027, prompting operators to redesign power distribution, cooling and rack infrastructure.
Sustainable data centre design is receiving greater emphasis across the region. The ASEAN guide stresses the need to balance digital expansion, environmental sustainability and resource security, which is increasing attention to power usage effectiveness, renewable electricity procurement, water usage effectiveness and lifecycle emissions in site selection, design and operating decisions.
Asia Pacific Data Center Market Segment Analysis
Asia Pacific Data Center Market Share is distributed across facility types, infrastructure categories, tier standards, end users and power capacity bands, each shaped by workload requirements, power availability and capital intensity. Estimated 2026 shares below reflect the leading segment in each category where supplied.
By Facility Type
- Colocation Data Centers
- Hyperscale Data Centers
- Enterprise Data Centers
Colocation data centers lead the facility type segment with an estimated 70% share in 2026, driven by enterprises, cloud providers and network operators that lease space, power and connectivity rather than build proprietary sites. Equinix and NTT Global Data Centers operate carrier-neutral colocation platforms across Asia Pacific, while Chindata and GDS operate in China’s data centre market. Hyperscale data centers follow, supported by campus-scale development from AirTrunk and the cloud platforms of Amazon Web Services, Google and Alibaba Cloud, which require high power capacity for AI and cloud workloads. Enterprise data centers are facilities owned and operated by individual organizations, typically for latency-sensitive, regulated or legacy applications, with demand shaped by the migration of workloads to colocation and cloud environments.
By Infrastructure
- IT
- Power
- Cooling
- Racks Cabinets
- Other
IT infrastructure leads the infrastructure segment with an estimated 42% share in 2026, reflecting the volume of servers, storage and networking equipment required to support cloud, AI and enterprise workloads. Power infrastructure follows, covering uninterruptible power supplies, switchgear, generators and distribution systems, where rising rack density increases requirements, as noted in the IEA’s 2026 report. Cooling is another important category, with higher-density AI deployments encouraging adoption of efficient and liquid cooling approaches highlighted in the ASEAN Guide for Sustainable Data Centre Development. Racks and cabinets provide the physical housing for equipment, while other infrastructure includes monitoring, security and fire protection systems used to maintain uptime and operational control.
Regional Analysis
The Asia Pacific Data Center Market is assessed across China, India, Japan, South Korea, Australia, Indonesia, Malaysia, Singapore and Vietnam. Only the China share is supplied; other country shares are not disclosed.
|
Region |
Estimated Market Share |
Key Growth Factors |
Industry Trends |
|---|---|---|---|
|
China |
34% |
Domestic cloud platforms and operators including Alibaba Cloud, Huawei Cloud, Chindata and GDS |
Large-scale AI and cloud capacity planning |
|
India |
- |
Cloud adoption, digital services and data localisation |
Rising colocation and hyperscale requirements |
|
Japan |
- |
Tokyo and Osaka-Kansai hubs, AirTrunk TOK1 and TOK2, NTT OSK11 |
Expansion beyond Tokyo; AI-ready, high-efficiency cooling designs |
|
South Korea |
- |
Hyperscale and colocation development around Seoul |
Demand for AI-ready, efficient capacity |
|
Australia |
- |
Sydney and Melbourne hyperscale campuses |
Campus-scale hyperscale expansion |
|
Indonesia |
- |
Digital economy growth and cloud adoption |
Demand for locally hosted capacity |
|
Malaysia |
- |
Johor Bahru campus development, including AirTrunk JHB2 |
Large-scale hyperscale funding |
|
Singapore |
- |
Regional hub; AirTrunk’s three data centres; Green Data Centre Roadmap |
Efficiency and sustainability-led growth |
|
Vietnam |
- |
Digital services expansion; NTT Global Data Centers operations |
Growing colocation presence |
China leads the regional market with an estimated 34% share in 2026, supported by domestic cloud platforms and data center operators including Alibaba Cloud, Huawei Cloud, Chindata and GDS. Large-scale cloud and AI deployment requires sustained power, cooling and network capacity, which keeps China central to regional capacity planning and supplier strategies.
Japan, Singapore, Australia and Malaysia host hyperscale and colocation development. AirTrunk operates campuses in Tokyo, Singapore and Australia and has secured funding for a Johor Bahru campus, while NTT opened OSK11 in Japan’s Kansai region. India, South Korea, Indonesia and Vietnam are shaped by cloud adoption, data localisation and expanding digital services, with grid access and cooling influencing site selection.
Market Share & Competitive Landscape
The Asia Pacific Data Center Market includes global cloud platforms, colocation specialists, hyperscale developers and regional operators. The table summarizes the supplied companies by general capability and relevant segment. It does not represent numerical market share.
|
Company |
Competitive Strength |
Primary Segment Served |
|---|---|---|
|
Amazon Web Services Inc. |
Global cloud infrastructure and services |
Hyperscale cloud and enterprise workloads |
|
Equinix Inc. |
Carrier-neutral colocation and interconnection platform |
Colocation and hyperscale (xScale) |
|
Alibaba Cloud |
Cloud computing platform and infrastructure |
Cloud and enterprise workloads |
|
Chindata Group Holdings Ltd |
Data center development and operation in China |
Hyperscale and cloud customers |
|
AirTrunk Operating Pty Ltd |
Hyperscale campus development across Asia Pacific |
Hyperscale data centers |
|
Space DC Pte Ltd |
Data center operations in Southeast Asia |
Colocation and hyperscale |
|
NTT Ltd |
Global data center platform of more than 160 facilities |
Colocation, hyperscale and enterprise |
|
Huawei Cloud Computing Technologies Co. Ltd |
Cloud services and ICT infrastructure |
Cloud and enterprise workloads |
|
Global Data Solutions Co. Ltd. (GDS) |
Data center operations in China |
Colocation and hyperscale |
|
Google Inc |
Global cloud and hyperscale infrastructure |
Hyperscale cloud |
Key Companies in the Asia Pacific Data Center Market
AirTrunk Operating Pty Ltd: AirTrunk is a Sydney-based hyperscale data centre specialist with Singapore as its Asia headquarters. Its announced TOK2 campus lifts platform capacity to 1.2 GW across Asia Pacific and Japan, and in August 2025 it issued a S$2.25 billion green loan for SGP2. Hyperscale campus delivery is its core strength.
NTT Ltd (NTT Global Data Centers): NTT Global Data Centers, part of Tokyo-headquartered NTT DATA, operates about 160 data centers across 20 markets with over 2 GW of capacity. It acquired land in Tochigi and Osaka in 2025 and opened the 30 MW Keihanna OSK11 facility in Kyoto in 2026. Strengths include AI-ready capacity.
Recent Developments
|
Year / Month |
Company |
Development |
|---|---|---|
|
August 2025 |
AirTrunk |
Issued a S$2.25 billion green loan to finance SGP2, its second Singapore hyperscale data centre. |
|
2026 |
AirTrunk |
Announced TOK2, a 110 MW hyperscale facility in western Tokyo, raising capacity to 410 MW in Japan and 1.2 GW across Asia Pacific and Japan. |
|
April 2026 |
NTT DATA |
Announced the opening of the 30 MW Keihanna OSK11 Data Center in Kyoto, its fourteenth data center in Japan. |
|
July 2026 |
AirTrunk |
Reported to have secured USD 2.3 billion in funding for its JHB2 campus in Johor Bahru, Malaysia. |
Asia Pacific Data Center Market Future Outlook
The Asia Pacific Data Center Market Forecast indicates expansion from USD 35.76 billion in 2026 to USD 168.82 billion by 2034 at a CAGR of 21.41%, based on supplied estimates. Growth is expected to depend on AI and cloud workloads, hyperscale campus development, data localisation requirements and the pace at which operators secure power, equipment and planning approvals across major country markets.
Technology investment is likely to concentrate on higher-density rack design, liquid and other efficient cooling methods, renewable electricity procurement and energy monitoring, in line with the IEA’s 2026 findings on AI server power density. Risks include grid-connection queues, electrical equipment shortages, water and cooling constraints and permitting delays. Projections remain assumptions, and actual outcomes depend on regulation, capital availability and operator execution.
Asia Pacific Data Center Market Report Coverage
This Asia Pacific Data Center Market Report summarizes the supplied valuation, forecast assumptions, segmentation, country framework and competitive ecosystem.
|
Parameter |
Details |
|---|---|
|
Market Name |
Asia Pacific Data Center Market |
|
Market Size 2026 |
USD 35.76 billion |
|
Market Size 2034 |
USD 168.82 billion |
|
Forecast Period |
2026–2034 |
|
CAGR |
21.41% |
|
Base Year |
2026 |
|
Historical Years |
2021–2025 |
|
Forecast Years |
2026–2034 |
|
Segments Covered |
By Facility Type; By Infrastructure; By Tier Standard; By End User; By Power Capacity |
|
Regions Covered |
China, India, Japan, South Korea, Australia, Indonesia, Malaysia, Singapore, Vietnam |
|
Key Companies |
Amazon Web Services Inc., Equinix Inc., Alibaba Cloud, Chindata Group Holdings Ltd, AirTrunk Operating Pty Ltd, Space DC Pte Ltd, NTT Ltd, Huawei Cloud Computing Technologies Co. Ltd, Global Data Solutions Co. Ltd. (GDS), Google Inc |
|
Report Format |
Market research report |
|
Customization |
Available as per client requirements |
Why Choose This Asia Pacific Data Center Market Report?
- Coverage of colocation, hyperscale and enterprise data center capacity across nine Asia Pacific countries.
- Clear presentation of the 2026 valuation, 2034 forecast and 21.41% CAGR.
- Segmentation across facility type, infrastructure, tier standard, end user and power capacity.
- Country-level framework covering China, India, Japan, South Korea, Australia, Indonesia, Malaysia, Singapore and Vietnam.
- Competitive profiling of global cloud platforms, colocation specialists and hyperscale developers.
- Trend insights on AI-driven rack density, power constraints and sustainable data centre design.
- Forecast context to support capacity planning, supplier strategy and market-entry evaluation.
Table of Contents
- Introduction
- Objective of the Study
- Product Definition
- Market Segmentation
- Study Variables
- Research Methodology
- Secondary Data Points
- Companies Interviewed
- Primary Data Points
- Breakdown of Primary Interviews
- Secondary Data Points
- Executive Summary
- Market Dynamics
- Drivers
- Challenges
- Opportunity Assessment
- Recent Trends and Developments
- Policy and Regulatory Landscape
- Asia Pacific Data Center Market Overview and Forecast Analysis (2021-2034)
- Market Size, By Value, By Growth Rate (CAGR/USD Billions)
- Demand – Supply Trends
- Market Share, By Facility Type
- Colocation Data Centers
- Hyperscale Data Centers
- Enterprise Data Centers
- Market Share, By Infrastructure
- IT
- Power
- Cooling
- Racks Cabinets
- Other
- Market Share, By Tier Standard
- Tier I II
- Tier III
- Tier IV
- Market Share, By End User
- IT Telecom
- Banking Financial
- Government Public
- Media Entertainment
- Healthcare Other
- Market Share, By Power Capacity
- Below 5 MW
- 5 to 15 MW
- Above 15 MW
- Market Share, By Country
- Chin
- India
- Japan
- South Korea
- Australia
- Indonesia
- Malaysia
- Singapore
- Vietnam
- Market Share, By Competitors
- Competition Characteristics
- Revenue Shares
- Colocation Data Centers Asia Pacific Data Center Market Overview, 2021-2034F
- By Value (USD Million)
- By Infrastructure – Market Size & Forecast 2021-2034, USD Million
- IT
- Power
- Cooling
- Racks Cabinets
- Other
- Hyperscale Data Centers Asia Pacific Data Center Market Overview, 2021-2034F
- By Value (USD Million)
- By Infrastructure – Market Size & Forecast 2021-2034, USD Million
- IT
- Power
- Cooling
- Racks Cabinets
- Other
- Enterprise Data Centers Asia Pacific Data Center Market Overview, 2021-2034F
- By Value (USD Million)
- By Infrastructure – Market Size & Forecast 2021-2034, USD Million
- IT
- Power
- Cooling
- Racks Cabinets
- Other
- Competitive Outlook (Company Profile – Partial List)
- Amazon Web Services Inc
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Equinix Inc.
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Alibaba Cloud
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Chindata Group Holdings Ltd
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- AirTrunk Operating Pty Ltd
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Space DC Pte Ltd
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- NTT Ltd
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Huawei Cloud Computing Technologies Co. Ltd
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Global Data Solutions Co. Ltd. (GDS)
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Google Inc
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Amazon Web Services Inc
- Contact Us & Disclaimer
Top Key Players & Market Share Outlook
- Amazon Web Services Inc
- Equinix Inc.
- Alibaba Cloud
- Chindata Group Holdings Ltd
- AirTrunk Operating Pty Ltd
- Space DC Pte Ltd
- NTT Ltd
- Huawei Cloud Computing Technologies Co. Ltd
- Global Data Solutions Co. Ltd. (GDS)
- Google Inc
Frequently Asked Questions