
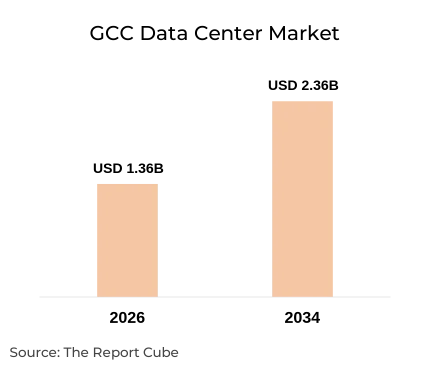
Build Your Custom Market Intelligence Report
Customize Your ReportKey Takeaways
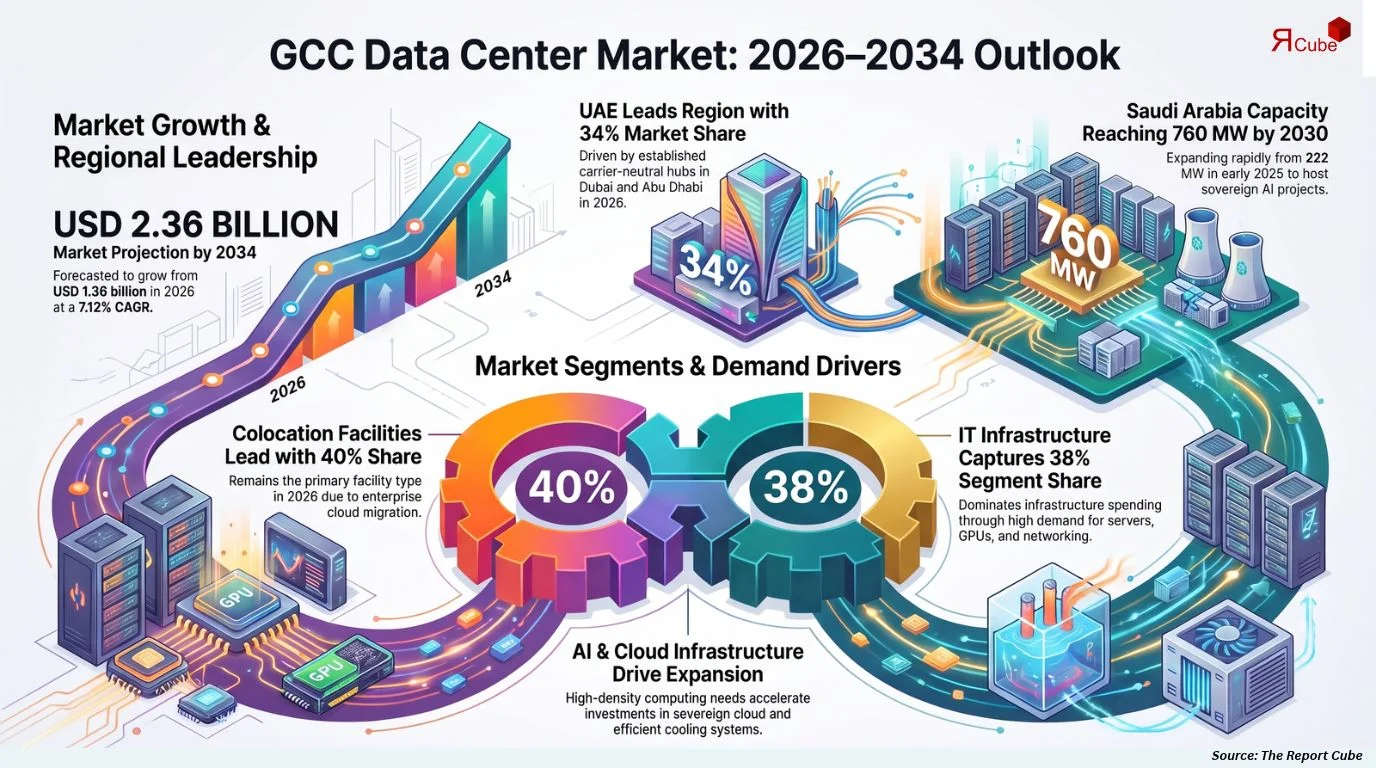
- GCC Data Center Market is valued at USD 1.36 billion in 2026.
- The market is projected to reach USD 2.36 billion by 2034, expanding at a CAGR of 7.12%.
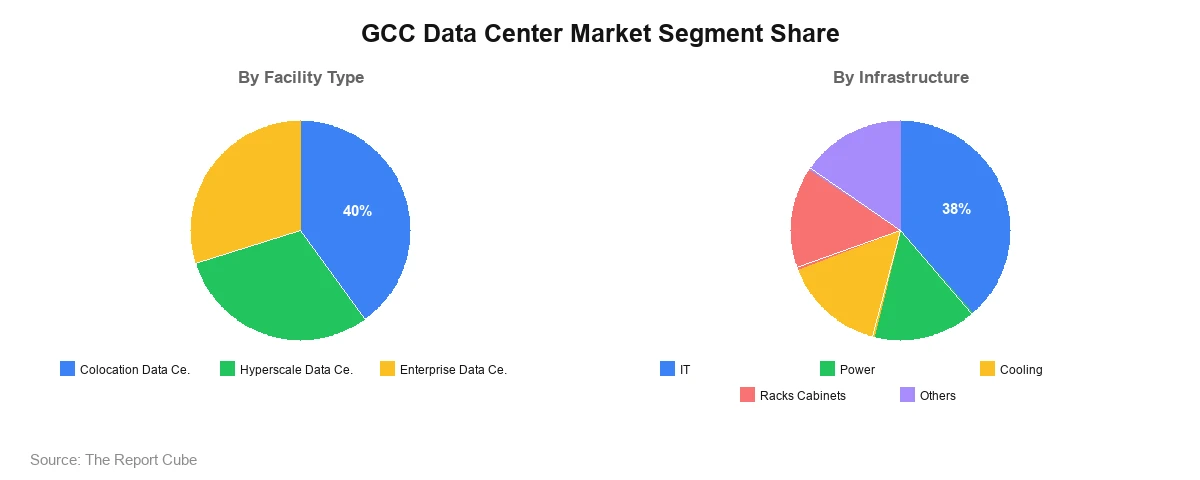
- Colocation data centers lead the facility type segment with an estimated 40% share in 2026.
- IT infrastructure leads the infrastructure segment with an estimated 38% share in 2026.
- United Arab Emirates leads the country segment with an estimated 34% share in 2026.
- Equinix, Digital Realty, NVIDIA, Gulf Data Hub, Ooredoo, STC, Mubadala and Etisalat are the supplied key players.
- AI-ready capacity and sovereign cloud infrastructure are important technology themes for the market.
Market Overview
A data center is a purpose-built facility that houses servers, storage systems, networking equipment, and the power and cooling infrastructure needed to operate them continuously. These facilities support cloud computing, enterprise applications, telecommunications, digital payments, content delivery, and artificial intelligence workloads, and they are operated as colocation, hyperscale, or enterprise sites.
This GCC Data Center Market Analysis covers Saudi Arabia, the United Arab Emirates, Kuwait, Oman, Qatar, and Bahrain, where demand is supported by cloud adoption, artificial intelligence workloads, smart-city programs, and government-led digital transformation. Industry assessments indicate that Saudi Arabia and the United Arab Emirates are expected to account for more than 80% of new Middle East capacity through 2030.
Enterprises, telecom operators, financial institutions, and public agencies are adopting data center capacity to meet data residency expectations, support cloud migration, and run high-density computing. Key developments include sovereign AI infrastructure, hyperscale campuses, and energy-efficient cooling. The GCC Data Center Market is projected to grow at a CAGR of 7.12% during 2026–2034.
GCC Data Center Market Dynamics
GCC Data Center Market Growth depends on AI workloads, cloud investment, government digital programs, power availability, cooling requirements, and construction capacity, while operators, equipment suppliers, and telecom groups compete on delivery speed, connectivity, energy efficiency, and sovereign hosting capabilities across six Gulf countries.
|
Factor |
Type |
Specific Impact on Market |
Magnitude |
|---|---|---|---|
|
AI and cloud infrastructure investment |
Driver |
Raises demand for computing capacity, storage, connectivity, and high-performance facilities, mainly in Saudi Arabia and the UAE |
High |
|
Government-led digital transformation |
Driver |
Creates demand for domestic computing capacity and in-country data hosting through national programs and sovereign AI initiatives |
High |
|
Hyperscale campuses and sovereign AI infrastructure |
Opportunity |
Opens demand for hyperscale operators, colocation providers, server suppliers, and power-system manufacturers |
High |
|
Energy-efficient cooling and power infrastructure |
Opportunity |
Supports demand for cooling, uninterruptible power supplies, and electrical distribution as computing density rises |
Medium–High |
|
Power availability and delivery constraints |
Challenge |
Supply-chain constraints and expertise shortages delay commissioning and raise project costs |
Medium–High |
|
Water availability and cooling requirements |
Challenge |
Hot climate and water scarcity complicate water-intensive cooling systems |
Medium |
|
AI-ready capacity expansion |
Trend |
Saudi Arabia’s planned 760 MW by 2030 and UAE-Saudi dominance of new capacity point to a large development pipeline |
High |
GCC Data Center Market Growth Drivers
Regional data center investment is increasingly driven by artificial intelligence workloads, cloud adoption, smart-city programs, and wider digital infrastructure expansion. These developments raise requirements for computing capacity, storage, connectivity, and high-performance facilities, particularly in Saudi Arabia and the United Arab Emirates, where operators and technology providers are directing capital toward new and expanded sites.
Government-led digital transformation is the second major driver. Industry assessments expect Saudi Arabia and the United Arab Emirates to lead Middle East capacity expansion through 2030, supported by public initiatives and digital infrastructure investment. National programs and sovereign AI initiatives are creating demand for domestic computing capacity and in-country data hosting.
GCC Data Center Market Opportunities
Hyperscale campuses and sovereign AI infrastructure create a clear supply opportunity. Industry assessments indicate that planned data center projects linked to HUMAIN in Saudi Arabia could reach up to 1.9 GW by 2030, with further expansion planned in the UAE. Hyperscale operators, colocation providers, server suppliers, and power-system manufacturers stand to benefit.
Rising AI workloads and cloud adoption are increasing demand for supporting infrastructure across the GCC, creating opportunities in advanced cooling, uninterruptible power supplies, electrical distribution, and energy monitoring. Infrastructure modernization is particularly relevant where high-density computing raises electricity and cooling requirements, giving equipment suppliers and engineering firms scope to address efficiency gaps.
GCC Data Center Industry Challenges
Power availability and infrastructure delivery remain constraints. Data center operators in Saudi Arabia face rapid infrastructure development, supply-chain constraints, and shortages of construction and operating expertise. These factors can delay commissioning, increase project costs, and limit how quickly new capacity becomes operational across the large pipeline of projects currently under development in the kingdom.
Water scarcity and cooling requirements add further pressure. Saudi Arabia’s hot climate and limited water availability complicate expansion where cooling depends on water-intensive systems. Operators must balance cooling performance, electricity consumption, water availability, and operating costs while maintaining the reliability levels that enterprise, cloud, and government customers expect from critical facilities.
Need Specific Data, Let’s Customize the Report for You
Request CustomizationGCC Data Center Market Trends
Among the most visible GCC Data Center Market Trends is Saudi Arabia’s expansion relative to established hubs. Industry assessments estimated the country’s data center IT power capacity at 222 MW in the first quarter of 2025, with an additional 760 MW planned by 2030, indicating a substantial development pipeline tied to its domestic digital economy.
Investment in AI-ready data centers is the second trend. An October 2026 industry outlook expects the United Arab Emirates and Saudi Arabia to account for more than 80% of new Middle East data center capacity through 2030, reflecting demand for AI computing, hyperscale infrastructure, and cloud services across the region.
GCC Data Center Market Segment Analysis
GCC Data Center Market Share is distributed across facility types, infrastructure categories, tier standards, end users, and power capacity bands, each shaped by workload requirements, resilience expectations, and capital intensity. Estimated 2026 shares are shown only where supplied, and country-level distribution is covered under Regional Analysis.
By Facility Type
- Colocation Data Centers
- Hyperscale Data Centers
- Enterprise Data Centers
Colocation data centers lead the facility type segment with an estimated 40% share in 2026, supported by carrier-neutral interconnection, shared power and cooling infrastructure, and the ability of enterprises and cloud providers to add capacity without building facilities. Equinix and Ooredoo are among the operators supplying colocation capacity in the region. Hyperscale data centers are tied to cloud adoption, AI training and inference workloads, and sovereign campuses such as the HUMAIN sites planned in Riyadh and Dammam. Enterprise data centers remain relevant for banks, government agencies, and large organizations that keep sensitive workloads under direct control, although many are also using colocation and cloud hosting.
By Infrastructure
- IT
- Power
- Cooling
- Racks Cabinets
- Other
IT infrastructure leads the infrastructure segment with an estimated 38% share in 2026, reflecting spending on servers, storage, and networking equipment as cloud and AI workloads expand. NVIDIA is a key supplier of accelerated computing hardware, including GPUs procured by operators such as HUMAIN and Ooredoo. Power systems, including uninterruptible power supplies and electrical distribution, are gaining importance as high-density computing raises load requirements. Cooling is closely linked, with operators weighing efficiency against water availability in a hot climate. Racks and cabinets support deployment density and cable management across new halls, while other infrastructure covers monitoring, fire suppression, and security systems used across facility types.
Country Analysis
|
Country |
Estimated Market Share |
Key Growth Factors |
Industry Trends |
|---|---|---|---|
|
Saudi Arabia |
- |
HUMAIN-linked projects of up to 1.9 GW by 2030; 222 MW IT capacity in Q1 2025 with 760 MW planned; government digital programs |
Sovereign AI and hyperscale campus development |
|
United Arab Emirates |
34% |
Established carrier-neutral facilities in Dubai and Abu Dhabi; government initiatives; planned AI-focused expansion |
AI-ready capacity and interconnection-led colocation |
|
Kuwait |
- |
Ooredoo Kuwait’s sovereign AI-enabled data centre with NVIDIA H200 GPUs |
Sovereign AI and GPU-based services |
|
Oman |
- |
Equinix facilities in Muscat and Salalah; Ooredoo network participation |
Carrier-neutral colocation and regional connectivity |
|
Qatar |
- |
Ooredoo’s expansion financing and NVIDIA partnership |
Telecom-led capacity and GPU-as-a-service |
|
Bahrain |
- |
Cloud and enterprise hosting demand; country-specific evidence not supplied |
Requires country-specific validation |
The United Arab Emirates is the leading country with an estimated 34% share in 2026, supported by established carrier-neutral facilities in Dubai and Abu Dhabi, telecom-operator participation, sovereign investment, and planned AI-focused expansion. Interconnection density sustains demand for colocation and hyperscale capacity. Equinix operated facilities in both emirates as of early 2025.
Saudi Arabia is a major expansion market, with an estimated 222 MW of IT power capacity in early 2025 and 760 MW planned by 2030, including HUMAIN’s Riyadh and Dammam sites. Qatar, Kuwait, and Oman are supported by Ooredoo’s regional data center network and AI infrastructure initiatives, while Bahrain’s contribution requires country-specific validation.
Market Share & Competitive Landscape
GCC Data Center Market includes global colocation operators, GPU and infrastructure suppliers, telecom groups, and sovereign investors. The table summarizes the supplied companies by general capability and relevant segment. It does not represent numerical market share, and country-level capacity and sales should be validated.
|
Company |
Competitive Strength |
Primary Segment Served |
|---|---|---|
|
Equinix |
Carrier-neutral colocation and interconnection, with Middle East facilities in Abu Dhabi, Dubai, Muscat, and Salalah |
Colocation and hyperscale |
|
Digital Realty |
Global data center and colocation platform |
Colocation, enterprise, and hyperscale |
|
NVIDIA |
Accelerated computing and AI platforms, including GPUs |
IT infrastructure |
|
Gulf Data Hub |
Regional data center operator |
Colocation |
|
Ooredoo |
Telecom-led data center network across Qatar, Kuwait, Oman, Iraq, and Tunisia; NVIDIA cloud partnership |
IT telecom, colocation, and GPU services |
|
STC |
Saudi telecom group with digital infrastructure operations |
IT telecom and government |
|
Mubadala |
Abu Dhabi sovereign investor with technology and infrastructure interests |
Investment in data center and AI infrastructure |
|
Etisalat |
UAE telecom group with enterprise connectivity and cloud services |
IT telecom, government, and enterprise |
Key Companies in the GCC Data Center Market
Equinix: Equinix is headquartered in Redwood City, California, and operates a global data center platform. In February 2025, it announced a USD 1 billion investment in carrier-neutral facilities in Saudi Arabia, adding to Middle East sites in Abu Dhabi, Dubai, Muscat, and Salalah. Its strength lies in interconnection.
Ooredoo: Ooredoo is headquartered in Doha, Qatar, and operates 26 data centers across Qatar, Kuwait, Oman, Iraq, and Tunisia. It signed an NVIDIA cloud partnership in 2024 and secured about USD 546 million in financing in September 2024 to expand its data center network. Its strength is telecom-led infrastructure.
Recent Developments
|
Year / Month |
Company |
Development |
|---|---|---|
|
February 2025 |
Equinix |
Announced a USD 1 billion investment in carrier-neutral data centers in Saudi Arabia at LEAP 2025 in Riyadh. |
|
August 2025 |
HUMAIN |
Reported construction of data centers in Riyadh and Dammam, each with initial capacity of up to 100 MW; launch was targeted for the second quarter of 2026. |
Market Future Outlook
The GCC Data Center Market Forecast indicates steady expansion from USD 1.36 billion in 2026 to USD 2.36 billion by 2034 at a CAGR of 7.12%, based on supplied estimates. Growth is expected to depend on AI workload deployment, cloud adoption, government digital programs, and the commissioning of colocation and hyperscale capacity across Saudi Arabia, the United Arab Emirates, and neighboring Gulf markets.
Investment is likely to concentrate on high-density power, energy-efficient cooling, sovereign AI infrastructure, and GPU-based services. Risks include power availability, supply-chain constraints, shortages of construction and operating expertise, water scarcity, and chip-export approvals. The projected values remain supplied assumptions, and actual outcomes depend on project delivery, regulation, technology access, capital availability, and customer demand across the six Gulf countries covered.
GCC Data Center Market Report Coverage
This GCC Data Center Market Report summarizes the supplied valuation, forecast assumptions, segmentation, regional framework, and competitive ecosystem.
|
Parameter |
Details |
|---|---|
|
Market Name |
GCC Data Center Market |
|
Market Size 2026 |
USD 1.36 billion |
|
Market Size 2034 |
USD 2.36 billion |
|
Forecast Period |
2026–2034 |
|
CAGR |
7.12% |
|
Base Year |
2026 |
|
Historical Years |
2021–2025 |
|
Forecast Years |
2026–2034 |
|
Segments Covered |
By Facility Type; By Infrastructure; By Tier Standard; By End User; By Power Capacity |
|
Regions Covered |
Saudi Arabia, United Arab Emirates, Kuwait, Oman, Qatar, Bahrain |
|
Key Companies |
Equinix, Digital Realty, NVIDIA, Gulf Data Hub, Ooredoo, STC, Mubadala, Etisalat |
|
Customization |
Available as per client requirements |
Why Choose This GCC Data Center Market Report?
- Market coverage of colocation, hyperscale, and enterprise data center capacity across six Gulf countries.
- Clear presentation of the supplied 2026 valuation, 2034 forecast, and 7.12% CAGR.
- Segmentation depth across facility type, infrastructure, tier standard, end user, and power capacity.
- Country-level framework covering Saudi Arabia, the UAE, Kuwait, Oman, Qatar, and Bahrain.
- Competitive profiling of supplied operators, telecom groups, investors, and technology suppliers.
- Trend and forecast insights to support capacity planning, supplier evaluation, and market-entry assessment.
- Context on national digital transformation and sovereign AI priorities relevant to infrastructure investment.
Table of Contents
- Introduction
- Objective of the Study
- Product Definition
- Market Segmentation
- Study Variables
- Research Methodology
- Secondary Data Points
- Companies Interviewed
- Primary Data Points
- Breakdown of Primary Interviews
- Secondary Data Points
- Executive Summary
- Market Dynamics
- Drivers
- Challenges
- Opportunity Assessment
- Recent Trends and Developments
- Policy and Regulatory Landscape
- GCC Data Center Market Overview and Forecast Analysis (2021-2034)
- Market Size, By Value, By Growth Rate (CAGR/USD Billions)
- Demand – Supply Trends
- Market Share, By Facility Type
- Colocation Data Centers
- Hyperscale Data Centers
- Enterprise Data Centers
- Market Share, By Infrastructure
- IT
- Power
- Cooling
- Racks Cabinets
- Other
- Market Share, By Tier Standard
- Tier I II
- Tier III
- Tier IV
- Market Share, By End User
- IT Telecom
- Banking Financial
- Government Public
- Media Entertainment
- Healthcare Other
- Market Share, By Power Capacity
- Below 5 MW
- 5 to 15 MW
- Above 15 MW
- Market Share, By Country
- Saudi Arabia
- United Arab Emirates
- Kuwait
- Oman
- Qatar
- Bahrain
- Market Share, By Competitors
- Competition Characteristics
- Revenue Shares
- Colocation Data Centers GCC Data Center Market Overview, 2021-2034F
- By Value (USD Million)
- By Infrastructure – Market Size & Forecast 2021-2034, USD Million
- IT
- Power
- Cooling
- Racks Cabinets
- Other
- Hyperscale Data Centers GCC Data Center Market Overview, 2021-2034F
- By Value (USD Million)
- By Infrastructure – Market Size & Forecast 2021-2034, USD Million
- IT
- Power
- Cooling
- Racks Cabinets
- Other
- Enterprise Data Centers GCC Data Center Market Overview, 2021-2034F
- By Value (USD Million)
- By Infrastructure – Market Size & Forecast 2021-2034, USD Million
- IT
- Power
- Cooling
- Racks Cabinets
- Other
- Competitive Outlook (Company Profile – Partial List)
- Equinix
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Digital Realty
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- NVIDIA
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Gulf Data Hub
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Ooredoo
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- STC
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Mubadala
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Etisalat
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Saudi Telecom Company
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Equinix
- Contact Us & Disclaimer
Top Key Players & Market Share Outlook
- Equinix
- Digital Realty
- NVIDIA
- Gulf Data Hub
- Ooredoo
- STC
- Mubadala
- Etisalat
- Saudi Telecom Company
Frequently Asked Questions