
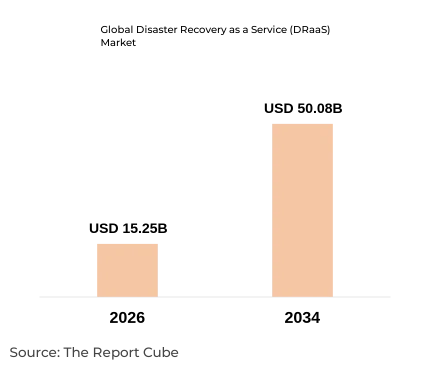
Build Your Custom Market Intelligence Report
Customize Your ReportKey Highlights
- The Global DRaaS Market was valued at USD 15.25 billion in 2026 (USD 13.17 billion in 2025).
- Market size is projected to reach USD 50.08 billion by 2034.
- The market is expected to grow at a CAGR of approximately 16.2% during 2026–2034.
- North America led regional demand with a 38% share in 2025, while Asia-Pacific is expected to be the fastest-growing region.
- Ransomware recovery and hybrid and multi-cloud adoption are the major growth drivers.
- Hyperscale cloud providers, data protection vendors and managed service providers compete, with Commvault’s Recovery Studio announcement (November 2026) and CBTS’s acquisition of Recovery Point Systems (September 2026) among recent developments.
Global DRaaS Market Outlook
Disaster Recovery as a Service (DRaaS) refers to cloud-based services that replicate, protect and restore IT infrastructure, applications and data after disruptions. Organizations gain access to recovery infrastructure without building and maintaining secondary data centres, which makes DRaaS relevant to business continuity, cyber resilience and operational risk management across industries.
Demand comes from financial services, healthcare, telecommunications, government and manufacturing, where outages affect revenue, compliance and customer trust. Core applications include data centre recovery, application recovery, virtual machine and database recovery, and cyber recovery. Subscription and consumption-based pricing is widening adoption among small and medium-sized enterprises that lack dedicated recovery personnel.
The Global DRaaS Market is projected to expand from USD 15.25 billion in 2026 to USD 50.08 billion in 2034, a CAGR of about 16.2%. Growth is supported by hybrid and multi-cloud infrastructure, ransomware recovery demand and automated orchestration. Competition is shifting from conventional backup toward integrated cyber resilience platforms combining immutable storage, replication, failover and recovery validation.
Government Regulations
Regulatory frameworks increasingly shape DRaaS adoption. The EU Digital Operational Resilience Act (Regulation (EU) 2022/2554) became applicable on 17 January 2025 and sets ICT risk management, business continuity, incident response and resilience testing requirements for covered financial entities, including oversight of ICT third-party providers. In the United States, NIST Special Publication 800-34 Rev. 1 provides information system contingency planning guidance, while CISA recommends maintaining offline, encrypted backups and regularly testing restoration. International standards such as ISO 22301 and ISO/IEC 27001 are widely used for continuity and security management. These requirements raise supplier qualification standards, favour providers with documented testing, encryption and data residency controls, and increase compliance costs for regulated buyers.
Global DRaaS Market Dynamics
Market dynamics reflect rising dependence on digital infrastructure, escalating cyber threats and the move toward hybrid IT. Regulatory resilience requirements and cost pressures shape service design and purchasing decisions, creating growth opportunities for providers while adding security and compliance obligations.
|
Factor |
Type |
Specific Impact on Market |
Magnitude |
|---|---|---|---|
|
Ransomware and cyber threats |
Driver |
Increases demand for immutable backup, isolated recovery and validated restoration |
High |
|
Cloud and hybrid IT adoption |
Driver |
Expands need for cross-environment replication and failover |
High |
|
SME adoption |
Opportunity |
Subscription models lower entry barriers for smaller firms |
Medium–High |
|
Data security, privacy and compliance |
Challenge |
Data sovereignty and retention rules add complexity and cost |
Medium–High |
|
Implementation and operating costs |
Challenge |
Replication bandwidth and cloud capacity limit budget-constrained buyers |
Medium |
|
Hybrid, multi-cloud and AI orchestration |
Trend |
Drives demand for automated, cross-platform recovery |
High |
Growth Drivers: Increasing Ransomware Attacks and Cybersecurity Threats
Ransomware increasingly targets enterprise databases, applications and backup infrastructure, threatening data availability and operational continuity. Organizations are investing in immutable backups, isolated recovery environments, continuous replication and recovery validation. CISA guidance recommends offline, encrypted backups and regular restoration testing, reinforcing these practices. The need to restore business-critical applications after attacks is expected to support managed DRaaS and ransomware recovery services across financial services, healthcare, retail and technology.
Market Opportunities: Increasing Demand for DRaaS Among SME
Small and medium-sized enterprises often lack the capital and technical expertise to maintain dedicated recovery infrastructure. Cloud-based services provide scalable backup, replication and restoration through subscription or usage-based models. Managed service providers can address this segment with standardized recovery packages, monitoring, testing and technical support. Affordable cloud recovery offerings are expected to broaden adoption among smaller organizations, creating a sizeable addressable base for managed DRaaS providers during the forecast period.
Industry Challenges: Data Security, Privacy and Regulatory Compliance
DRaaS providers handle sensitive enterprise information across geographically distributed recovery environments, so replicated data must be protected against unauthorized access, breaches and accidental modification. Data sovereignty, encryption, access management and retention requirements add implementation complexity, particularly for financial services, healthcare and government customers. These obligations can raise compliance costs and lengthen provider evaluation cycles, which may slow contract conversion for vendors without recognised certifications.
Need Specific Data, Let’s Customize the Report for You
Request CustomizationMarket Trends: Growing Adoption of Hybrid and Multi-Cloud Disaster Recovery
Organizations increasingly run workloads across public cloud, private cloud and on-premises environments, creating demand for recovery platforms that avoid dependence on a single provider. Hybrid and multi-cloud recovery lets enterprises replicate critical workloads across environments while addressing data residency and application compatibility needs. Rising IT complexity is expected to support demand for cross-platform replication, centralized recovery management and automated orchestration that restores complete applications and dependencies rather than individual files.
Global DRaaS Market Segment Analysis
The market is segmented by service type, deployment model, organization size, application, industry vertical, recovery model, end user, distribution channel and region. Only leading-segment shares supported by supplied data are displayed.
By Service Type
- Backup & Recovery Services
- Real-Time Replication Services
- Data Protection Services
- Cloud-Based Disaster Recovery
- Managed Disaster Recovery Services
- Ransomware Recovery Services
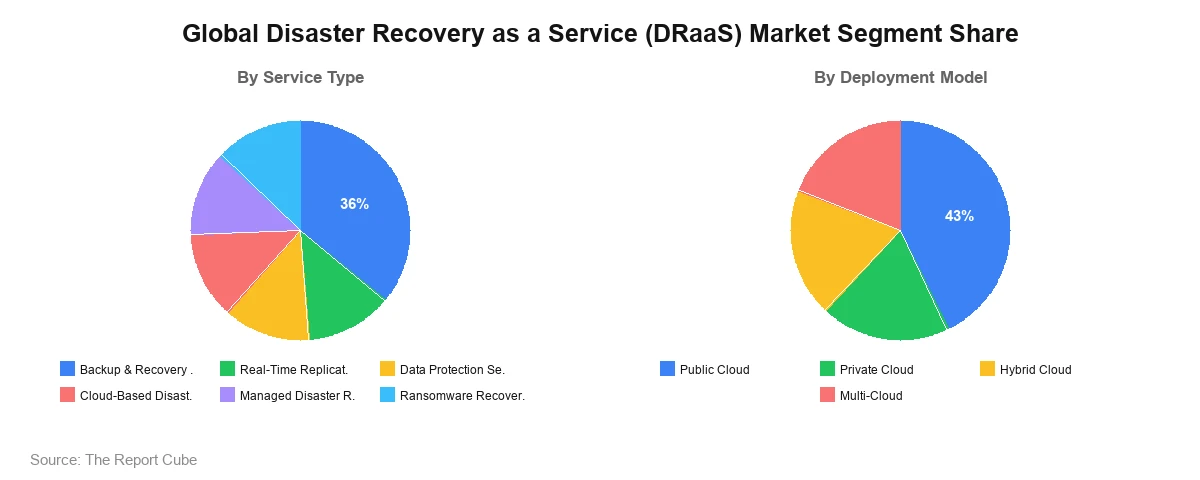
Backup & Recovery Services lead this category with a 36% share in 2025. They form the foundation of DRaaS, preserving copies of databases, applications and virtual machines for restoration after disruption, supported by growing data volumes and demand for automated scheduling and recovery testing. Managed Disaster Recovery Services rank among the other significant segments, as providers handle replication, monitoring, testing and failover for organizations without dedicated personnel. Real-time replication, data protection, cloud-based recovery and ransomware recovery serve specialized continuity and security needs.
By Deployment Model
- Public Cloud
- Private Cloud
- Hybrid Cloud
- Multi-Cloud
Public Cloud leads with a 43% share in 2025, offering scalable storage and compute with consumption-based pricing and no dedicated recovery facilities. Hybrid Cloud is the second segment analysed, suited to organizations with legacy systems that keep critical workloads on existing infrastructure while using cloud resources for replication and recovery. Private Cloud serves regulated industries needing tighter control over security and governance, and Multi-Cloud reduces single-provider dependence and supports geographic redundancy.
Global DRaaS Market Regional Analysis
Regional demand reflects cloud infrastructure availability, cybersecurity investment, regulatory requirements, enterprise IT spending and adoption of managed recovery services. Only the leading region’s share is supported by supplied data.
|
Region |
Estimated Market Share |
Key Growth Factors |
Industry Trends |
|---|---|---|---|
|
North America |
38% |
Established cloud infrastructure, enterprise technology adoption, cybersecurity investment |
Ransomware recovery and managed services demand |
|
Europe |
- |
Operational resilience regulation, data protection requirements |
Hybrid and multi-cloud adoption |
|
Asia-Pacific |
- |
Cloud migration, digital banking, e-commerce growth |
Fastest-growing region; SME managed DRaaS |
|
Latin America |
- |
Legacy IT modernization, digital financial services |
Emerging adoption of cloud recovery |
|
Middle East & Africa |
- |
Digital government, data centre investment |
Growth of managed cloud services |
North America is the largest regional market, supported by mature cloud infrastructure, extensive enterprise technology adoption and strong cybersecurity spending. The United States accounts for much of regional demand across financial services, healthcare, telecommunications and technology. A strong hyperscale and data protection vendor ecosystem, together with growing attention to ransomware protection, governance and managed infrastructure services, sustains regional leadership. Shares for other regions were not verified and are not estimated.
Competitive Landscape
The market includes hyperscale cloud providers, enterprise data protection vendors, infrastructure suppliers and managed service providers. They compete on recovery speed, data protection, cloud compatibility, automation, service-level agreements and enterprise support. The table reflects capability and does not represent verified market share or ranking.
|
Company |
Competitive Strength |
Primary Segment Served |
|---|---|---|
|
Amazon Web Services |
Elastic Disaster Recovery with continuous replication and failover |
Public cloud; enterprises |
|
Microsoft Corporation |
Azure Site Recovery for workload replication and recovery plans |
Hybrid and public cloud; enterprises |
|
Google Cloud |
Backup and DR with immutable backup vaults |
Public cloud; enterprises |
|
Oracle Corporation |
OCI Full Stack Disaster Recovery orchestration |
Enterprise applications and databases |
|
Hewlett Packard Enterprise (Zerto) |
Continuous data protection |
Hybrid cloud; large enterprises |
|
Veeam Software |
Backup and service-provider-delivered DR |
Enterprises; MSPs |
|
Commvault |
Recovery orchestration and data protection |
Large enterprises |
|
Cohesity |
Data protection and cyber resilience |
Enterprises |
|
Rubrik |
Cyber recovery and data security |
Enterprises; cyber recovery |
|
Acronis |
Integrated backup and cybersecurity |
SMEs; MSPs |
|
TierPoint |
Managed cloud and recovery services |
Mid-market; managed DRaaS |
Amazon Web Services: AWS is a leading hyperscale cloud provider whose Elastic Disaster Recovery service offers continuous block-level replication and orchestrated failover for on-premises and cloud workloads. It operates global regions and availability zones, supports consumption-based pricing, and integrates recovery with its broader storage, networking and security services, giving it strong reach among enterprises and SMEs.
Veeam Software: Veeam is a data protection vendor known for backup, replication and recovery software, including Cloud Connect, which lets service providers deliver backup and DR to customers. Its channel-led model through MSPs and resellers, and compatibility with virtual, physical and multi-cloud environments, underpin its position in the managed recovery ecosystem.
Recent Developments and Updates
- November 2026: Commvault announced Recovery Studio, a recovery orchestration approach that restores complete business services by integrating applications, identities, configurations, infrastructure dependencies and datasets, reflecting the shift toward service-level recovery.
- September 2026: CBTS announced its acquisition of Recovery Point Systems, expanding its disaster recovery and cyber resilience capabilities and signalling consolidation among managed recovery providers.
- February 2026: Kyndryl announced Intelligent Recovery Service, focusing on hybrid and multi-cloud recovery, automation and enterprise resilience.
Global DRaaS Market Future Outlook
The Global DRaaS Market is expected to grow from USD 15.25 billion in 2026 to USD 50.08 billion by 2034 at a CAGR of about 16.0%. Expansion will be supported by cloud migration, ransomware recovery, AI-enabled orchestration and automated testing. Hybrid and multi-cloud recovery, SME-focused managed services and integrated cyber resilience platforms represent the main opportunities, with growth moderating as the base expands and adoption matures in established regions.
Competition is expected to centre on recovery orchestration, immutable storage, cloud compatibility and managed support, with consolidation and acquisitions reshaping the provider landscape. Challenges include data sovereignty, compliance costs, cloud provider outages and the cost of continuous replication for budget-constrained buyers. Regulation such as DORA will continue to reinforce testing and resilience requirements, favouring providers with proven, certified recovery capabilities.
Global DRaaS Market Report Coverage
This report covers market size, forecast, segmentation, regional context and competitive landscape for the Global DRaaS Market using supplied estimates and verified regulatory sources.
|
Parameter |
Details |
|---|---|
|
Market Name |
Global Disaster Recovery as a Service (DRaaS) Market |
|
Market Size (Base Year) |
USD 15.25 billion (2026) |
|
Market Size (Forecast Year) |
USD 50.08 billion (2034) |
|
CAGR |
16.0% (2026–2034) |
|
Base Year |
2026 |
|
Historical Period |
2021–2025 |
|
Forecast Period |
2026–2034 |
|
Geographic Scope |
Global |
|
Segmentation |
Service Type; Deployment Model; Organization Size; Application; Industry Vertical; Recovery Model; End User; Distribution Channel |
|
Regions Covered |
North America; Europe; Asia-Pacific; Latin America; Middle East & Africa |
|
Key Companies |
AWS; Microsoft; Google Cloud; Oracle; HPE (Zerto); Veeam; Commvault; Cohesity; Rubrik; Acronis; TierPoint; and Others |
|
Customization |
Available as per requirement |
Why Choose This Global DRaaS Market Report?
- Presents the 2026 base value, 2034 forecast and CAGR with consistent assumptions.
- Segments the market across eight categories, covering service, deployment, industry and channel.
- Analyses drivers, opportunities, challenges and trends shaping DRaaS adoption.
- Provides regional assessment across five regions, with unverified shares disclosed.
- Profiles hyperscalers, data protection vendors and managed providers by capability.
- Highlights hybrid and multi-cloud, ransomware recovery and SME opportunities.
- Supports investment, product and go-to-market decisions with regulatory context.
Table of Contents
- Introduction
- Objective of the Study
- Product Definition
- Market Segmentation
- Study Variables
- Research Methodology
- Secondary Data Points
- Companies Interviewed
- Primary Data Points
- Breakdown of Primary Interviews
- Secondary Data Points
- Executive Summary
- Market Dynamics
- Drivers
- Challenges
- Opportunity Assessment
- Recent Trends and Developments
- Policy and Regulatory Landscape
- Global Disaster Recovery as a Service Market Overview and Forecast Analysis (2021-2034)
- Market Size, By Value, By Growth Rate (CAGR/USD Billions)
- Demand – Supply Trends
- Market Share, By Service Type
- Backup & Recovery Services
- Real-Time Replication Services
- Data Protection Services
- Cloud-Based Disaster Recovery
- Managed Disaster Recovery Services
- Ransomware Recovery Services
- Market Share, By Deployment Model
- Public Cloud
- Private Cloud
- Hybrid Cloud
- Multi-Cloud
- Market Share, By Organization Size
- Large Enterprises
- Small & Medium-Sized Enterprises (SMEs)
- Market Share, By Application
- Data Center Recovery
- Application Recovery
- Virtual Machine Recovery
- Database Recovery
- Endpoint & Device Recovery
- Cyber Recovery & Ransomware Protection
- Market Share, By Industry Vertical
- Banking, Financial Services & Insurance (BFSI)
- Healthcare & Life Sciences
- Government & Public Sector
- IT & Telecommunications
- Retail & E-commerce
- Manufacturing
- Energy & Utilities
- Media & Entertainment
- Education
- Others
- Market Share, By Recovery Model
- Disaster Recovery Planning
- Backup-as-a-Service (BaaS)
- Recovery-as-a-Service (RaaS)
- Business Continuity Services
- Managed Recovery Services
- Market Share, By End User
- Enterprises
- Government Organizations
- Cloud Service Providers
- Managed Service Providers (MSPs)
- Colocation Providers
- Market Share, By Distribution Channel
- Direct Sales
- Managed Service Providers (MSPs)
- Cloud Marketplace Platforms
- System Integrators
- Value-Added Resellers (VARs)
- Market Share, By Region
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Market Share, By Competitors
- Competition Characteristics
- Revenue Shares
- Backup & Recovery Services Global Disaster Recovery as a Service Market Overview, 2021-2034F
- By Value (USD Million)
- By Deployment Model – Market Size & Forecast 2021-2034, USD Million
- Public Cloud
- Private Cloud
- Hybrid Cloud
- Multi-Cloud
- Real-Time Replication Services Global Disaster Recovery as a Service Market Overview, 2021-2034F
- By Value (USD Million)
- By Deployment Model – Market Size & Forecast 2021-2034, USD Million
- Public Cloud
- Private Cloud
- Hybrid Cloud
- Multi-Cloud
- Data Protection Services Global Disaster Recovery as a Service Market Overview, 2021-2034F
- By Value (USD Million)
- By Deployment Model – Market Size & Forecast 2021-2034, USD Million
- Public Cloud
- Private Cloud
- Hybrid Cloud
- Multi-Cloud
- Cloud-Based Disaster Recovery Global Disaster Recovery as a Service Market Overview, 2021-2034F
- By Value (USD Million)
- By Deployment Model – Market Size & Forecast 2021-2034, USD Million
- Public Cloud
- Private Cloud
- Hybrid Cloud
- Multi-Cloud
- Managed Disaster Recovery Services Global Disaster Recovery as a Service Market Overview, 2021-2034F
- By Value (USD Million)
- By Deployment Model – Market Size & Forecast 2021-2034, USD Million
- Public Cloud
- Private Cloud
- Hybrid Cloud
- Multi-Cloud
- Ransomware Recovery Services Global Disaster Recovery as a Service Market Overview, 2021-2034F
- By Value (USD Million)
- By Deployment Model – Market Size & Forecast 2021-2034, USD Million
- Public Cloud
- Private Cloud
- Hybrid Cloud
- Multi-Cloud
- Competitive Outlook (Company Profile – Partial List)
- Amazon Web Services (AWS)
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Microsoft
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- IBM
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Google Cloud
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Broadcom (VMware)
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Oracle
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Hewlett Packard Enterprise (HPE)
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Dell Technologies
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Cisco
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Zerto (HPE)
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Veeam Software
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Acronis
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Cohesity
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Commvault
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Others
- Amazon Web Services (AWS)
- Contact Us & Disclaimer
Top Key Players & Market Share Outlook
- Amazon Web Services (AWS)
- Microsoft
- IBM
- Google Cloud
- Broadcom (VMware)
- Oracle
- Hewlett Packard Enterprise (HPE)
- Dell Technologies
- Cisco
- Zerto (HPE)
- Veeam Software
- Acronis
- Cohesity
- Commvault
- Others
Frequently Asked Questions