
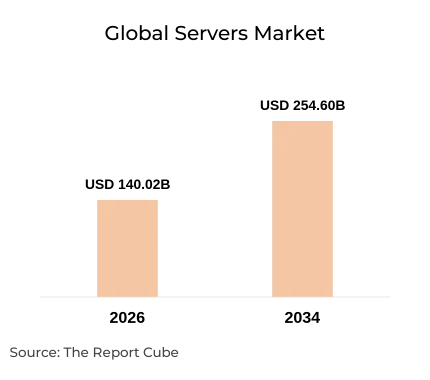
Build Your Custom Market Intelligence Report
Customize Your ReportGlobal Servers Market Key Takeaways
- Global servers market valued at USD 140.02 billion in 2026, reflecting accelerating enterprise infrastructure investment.
- Industry projected to reach USD 254.60 billion by 2034 at a 7.76% CAGR.
- Market expanding at a consistent 7.76% CAGR through the 2034 forecast period.
- Rack servers lead the product segment driven by data center scalability and high-density deployment requirements.
- Large enterprises dominate global server procurement driven by hyperscale cloud and AI infrastructure build-outs.
- Medium enterprises represent the fastest-growing enterprise size segment as digital transformation accelerates.
- Hewlett Packard Enterprise, Dell Technologies, and IBM lead global server supply across commercial and cloud channels.
- AI workload integration and edge computing adoption are fundamentally reshaping server architecture procurement decisions.
Global Servers Market Overview
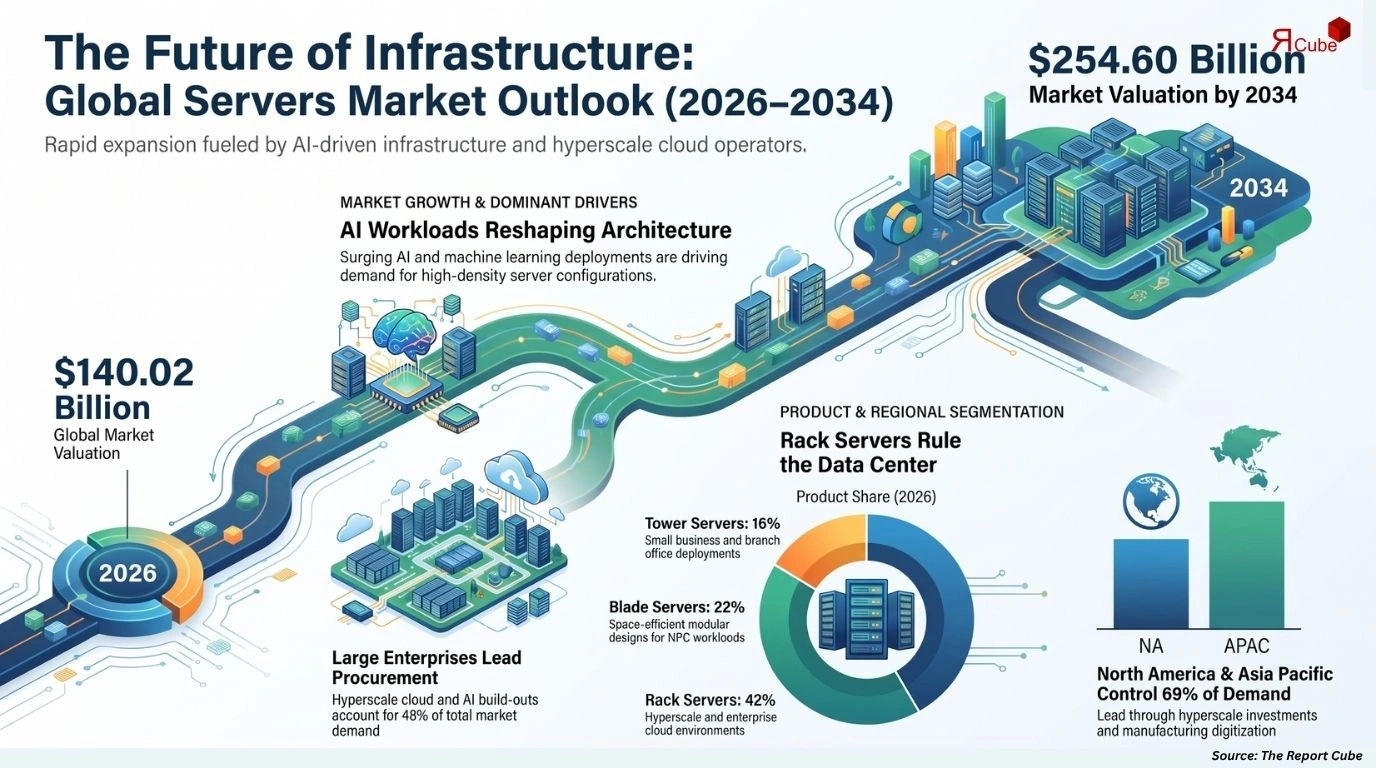
The Global Servers Market is anticipated to register a 7.76% CAGR during 2026–2034. The market size was valued at USD 140.02 billion in 2026 and is projected to reach USD 254.60 billion by 2034. A thorough Global Servers Market analysis reveals that accelerating cloud infrastructure investment, surging AI and machine learning workload deployments, and expanding enterprise digital transformation programs are collectively driving sustained demand across rack, blade, and micro server product categories. Government-backed data sovereignty initiatives across North America, Europe, and Asia Pacific are further reinforcing domestic server procurement volumes.
Hyperscale cloud operators including Amazon Web Services, Microsoft Azure, and Google Cloud are intensifying server infrastructure investments, generating substantial procurement volumes for Hewlett Packard Enterprise, Dell Technologies, and Lenovo across custom and standard server configurations. Sustainability-driven procurement practices, including energy-efficient server certification requirements and green data center mandates, are reshaping product development priorities for leading server manufacturers globally. Cisco Systems, Oracle, and Fujitsu are deepening enterprise client engagement through integrated server-storage-networking solution offerings and lifecycle management programs.
Global Servers Market Size & Forecast
|
Metric |
Details |
|---|---|
|
Market Size (2026) |
USD 140.02 Billion |
|
Market Size (2034) |
USD 254.60 Billion |
|
CAGR (2026–2034) |
7.76% |
|
Base Year |
2026 |
|
Historical Years |
2021–2025 |
|
Forecast Years |
2026–2034 |
The Global Servers Market size was valued at USD 140.02 billion in 2026 and is projected to reach USD 254.60 billion by 2034, expanding at a 7.76% CAGR through the forecast period. This trajectory outpaces broader IT infrastructure growth averages, driven primarily by accelerating AI inference and training infrastructure deployments that demand higher-density, purpose-built server configurations across hyperscale, enterprise, and edge computing environments globally.
Global Servers Market Dynamics
The Global Servers Market is shaped by a convergence of structural demand forces including AI-driven infrastructure scaling, cloud service expansion, and enterprise modernization programs. Rising investments in edge computing, sovereign cloud deployments, and hybrid IT architectures are reinforcing procurement volumes across all server product categories and enterprise size segments through 2034.
|
Factor |
Type |
Specific Impact on Market |
Magnitude |
|---|---|---|---|
|
AI and machine learning infrastructure demand |
Driver |
Accelerates procurement of high-compute rack and blade server configurations globally |
High |
|
Hyperscale cloud operator capex expansion |
Driver |
Generates large-volume server orders from AWS, Azure, and Google Cloud infrastructure programs |
High |
|
Semiconductor supply chain constraints |
Challenge |
Disrupts server production timelines and increases component costs for OEM manufacturers |
Medium |
|
Edge computing infrastructure deployment |
Opportunity |
Expands micro and tower server demand in industrial, retail, and telecommunications environments |
High |
|
Energy efficiency and green IT mandates |
Trend |
Drives adoption of power-optimized server designs and liquid cooling-compatible server architectures |
Medium |
- Growth Drivers - Explosive growth in AI model training and inference workloads is compelling enterprises and cloud operators to significantly scale server infrastructure investments. Hyperscale operators including Microsoft and Amazon are committing record capital expenditure to GPU-dense server deployments, with Hewlett Packard Enterprise and Dell Technologies capturing substantial procurement volumes across customized configurations in 2024 and 2025.
- Market Opportunities - Edge computing infrastructure represents a high-growth opportunity as telecommunications operators, industrial manufacturers, and smart city initiatives deploy distributed server nodes closer to data generation sources. The rollout of 5G networks across Asia Pacific and North America is accelerating micro and tower server procurement for latency-sensitive applications requiring local compute capabilities beyond centralized cloud reach.
- Industry Challenges - Rapidly evolving AI server architecture requirements are compressing product lifecycle timelines and increasing R&D cost burdens for incumbent server manufacturers. Liquid cooling infrastructure compatibility, power density management, and data center retrofit requirements for next-generation AI server deployments create significant capital barriers for mid-tier enterprise clients seeking modern high-performance server configurations.
Global Servers Market Trends
- Emerging Trends - Global Servers Market trends reflect the accelerating convergence of AI-optimized server designs, liquid immersion cooling adoption, and open hardware standards including Open Compute Project architectures gaining traction among hyperscale operators seeking infrastructure customization and vendor diversification beyond traditional OEM supply chains.
- Technology Trends - ARM-based server processor adoption is gaining enterprise momentum as Ampere Computing, Graviton-powered instances, and Fujitsu's A64FX architecture demonstrate competitive performance-per-watt benchmarks. Composable infrastructure platforms, NVMe-over-Fabrics storage integration, and silicon photonics-based interconnects are progressively entering enterprise server configurations targeting AI and high-performance computing workloads.
- Consumer / Buyer Trends - Enterprise procurement teams increasingly prioritize total cost of ownership, energy efficiency ratings, and AI-readiness certifications when evaluating server vendors. Buyers across financial services, healthcare, and manufacturing sectors favor server configurations offering native GPU expansion compatibility, advanced thermal management, and software-defined infrastructure management capabilities from suppliers including Dell Technologies and Lenovo.
Need Specific Data, Let’s Customize the Report for You
Request CustomizationGlobal Servers Market Segment Analysis
The Global Servers Market serves distinct product architecture requirements and enterprise deployment scales, each driven by unique infrastructure priorities, workload characteristics, and procurement budget structures. Segment-level demand varies significantly across hyperscale, enterprise, and edge deployment environments worldwide.
By Product
|
Product Type |
Estimated Share (2026) |
Key Characteristics |
|---|---|---|
|
Rack |
42% |
High-density data center deployment; dominant in hyperscale and enterprise cloud environments |
|
Blade |
22% |
Modular chassis design; space-efficient for large enterprise and HPC workloads |
|
Tower |
16% |
SMB and branch office deployments; lower infrastructure complexity requirements |
|
Micro |
12% |
Edge and IoT applications; compact form factor for distributed compute environments |
|
Open Compute Project |
8% |
Custom hyperscale architectures; cost-optimized hardware for large-scale cloud operators |
Rack servers command the leading Global Servers Market share at an estimated 42% in 2026, driven by hyperscale data center expansion and enterprise cloud infrastructure build-outs. Hewlett Packard Enterprise's ProLiant rack series and Dell Technologies' PowerEdge portfolio dominate institutional procurement across cloud and enterprise segments. Blade servers, representing approximately 22%, are primarily supplied by Cisco Systems through its UCS platform and IBM through modular enterprise configurations. Open Compute Project architectures, though the smallest segment, are gaining traction with operators seeking vendor-neutral, cost-optimized server designs for large-scale AI deployments.
By Enterprise Size
|
Enterprise Size |
Estimated Share (2026) |
Growth Outlook |
|---|---|---|
|
Large |
48% |
Steady; driven by hyperscale cloud operator capex and Fortune 500 data center investments |
|
Medium |
28% |
Fastest-growing; digital transformation and hybrid cloud adoption accelerating procurement |
|
Small |
15% |
Growing; SMB cloud adoption and managed service provider infrastructure driving demand |
|
Micro |
9% |
Emerging; edge AI and IoT application deployments sustaining niche server procurement |
Large enterprises represent the dominant end-user segment at approximately 48% of Global Servers Market demand in 2026, with hyperscale cloud operators and global corporations sustaining high-volume procurement from Hewlett Packard Enterprise, Dell Technologies, and Lenovo. The medium enterprise segment is the fastest-growing category as hybrid cloud adoption, ERP modernization, and AI integration programs expand server infrastructure requirements. Supermicro and Oracle serve medium enterprise segments with purpose-built configurations, while Fujitsu and Huawei address large enterprise and government procurement across Europe and Asia Pacific respectively.
Global Servers Market Regional Analysis
|
Region |
Estimated Market Share |
Key Growth Factors |
Consumer Trends |
|---|---|---|---|
|
North America |
38% |
Hyperscale cloud capex, AI infrastructure build-outs, federal IT modernization |
High rack server adoption, AI-optimized configurations, liquid cooling demand |
|
Asia Pacific |
31% |
Manufacturing digitization, government cloud programs, edge computing expansion |
Blade and micro server adoption, domestic OEM preference, 5G edge deployments |
|
Europe |
18% |
Data sovereignty regulations, green IT mandates, enterprise hybrid cloud investment |
Energy-efficient server procurement, EU-compliant configurations, OCP adoption |
|
Latin America |
8% |
Financial sector IT modernization, e-commerce infrastructure growth, cloud adoption |
Rack and tower server procurement, cost-efficiency emphasis, SMB digitization |
|
Middle East and Africa |
5% |
Smart city programs, sovereign cloud development, regional data center expansion |
Government server procurement, hyperscale facility build-outs, energy-efficient designs |
- North America - Accounting for approximately 38% of global demand, North America is anchored by hyperscale cloud operator infrastructure investments from Amazon, Microsoft, and Google alongside large-scale federal IT modernization programs. Hewlett Packard Enterprise and Dell Technologies maintain dominant supply positions across commercial enterprise and government procurement channels throughout the region.
- Asia Pacific - Representing the second-largest regional segment at 31%, Asia Pacific is driven by China's domestic cloud infrastructure expansion, India's rapidly digitalizing enterprise sector, and Japan's advanced manufacturing automation investments. Lenovo, Huawei, and Fujitsu hold strong regional supply positions, while government-backed data center development programs in Southeast Asia are generating new server procurement volumes.
- Europe - Holding an estimated 18% share, Europe's server market is shaped by stringent data localization requirements, EU Green Deal sustainability standards, and accelerating enterprise digital transformation investment. Hewlett Packard Enterprise, Dell Technologies, and Fujitsu serve the region's compliance-driven procurement needs, with energy-efficient server configurations and EUCS certification compatibility increasingly becoming baseline requirements.
- Latin America - Representing approximately 8% of global server market demand, Latin America's growth is propelled by Brazil and Mexico's expanding financial technology sectors, e-commerce infrastructure scaling, and increasing cloud service adoption. Dell Technologies and Lenovo hold competitive supply positions across the region's enterprise and SMB procurement segments, with tower and entry-level rack servers driving volume growth.
- Middle East and Africa - Accounting for an estimated 5% share, the region is experiencing accelerating demand from sovereign cloud initiatives in Saudi Arabia and UAE, smart city infrastructure programs, and expanding regional hyperscale data center developments. Hewlett Packard Enterprise, Huawei, and Cisco Systems are active suppliers across government and enterprise procurement programs supporting the region's growing digital infrastructure ambitions.
Global Servers Market Share & Competitive Landscape
The Global Servers Market's competitive landscape is shaped by a small number of vertically integrated OEMs holding dominant supply positions across enterprise, cloud, and government procurement segments. Key players differentiate on product portfolio breadth, AI-optimized configurations, global support infrastructure, and total cost of ownership propositions.
|
Company |
Competitive Strength |
Primary Segment Served |
|---|---|---|
|
Hewlett Packard Enterprise |
Broad ProLiant portfolio, GreenLake cloud-as-a-service model, global enterprise reach |
Large enterprise, hyperscale, government |
|
Dell Technologies |
PowerEdge portfolio depth, integrated solutions, direct enterprise sales model |
Large and medium enterprise, cloud operators |
|
IBM |
Mission-critical Power systems, hybrid cloud integration, high-security workloads |
Large enterprise, financial services, government |
|
Cisco Systems |
UCS blade architecture, converged infrastructure, network-integrated server platforms |
Enterprise blade and HPC deployments |
|
Lenovo |
ThinkSystem portfolio, Asia Pacific manufacturing scale, competitive TCO |
Large and medium enterprise, Asia Pacific |
|
Oracle |
Engineered systems, database-optimized server configurations, cloud integration |
Enterprise database and ERP workloads |
|
Fujitsu |
PRIMERGY server portfolio, Japan and European government procurement, ARM-based HPC |
Government, HPC, European enterprise |
|
Supermicro |
High-density AI server configurations, GPU-optimized designs, rapid product iteration |
AI workloads, cloud builders, HPC operators |
|
Huawei |
Asia Pacific and emerging market presence, end-to-end data center solutions |
Large enterprise, telecoms, government (non-Western markets) |
Key Companies in the Global Servers Market
Hewlett Packard Enterprise
Hewlett Packard Enterprise (HPE), headquartered in Houston, Texas, is one of the world's largest server manufacturers, operating across 170 countries with a comprehensive portfolio spanning rack, blade, and tower configurations under the ProLiant brand. In 2025, HPE expanded its AI server portfolio with enhanced NVIDIA GPU-integrated ProLiant Gen12 configurations targeting enterprise and hyperscale AI workload deployments globally. HPE's GreenLake edge-to-cloud platform differentiates the company by enabling as-a-service server infrastructure consumption models for enterprise clients seeking capital-efficient IT modernization pathways.
Dell Technologies
Dell Technologies, headquartered in Round Rock, Texas, operates as a leading global server OEM with its PowerEdge server portfolio deployed across cloud, enterprise, and government environments in over 180 countries. In 2025, Dell Technologies launched expanded PowerEdge XE9680 AI server configurations optimized for large language model training workloads, strengthening its competitive positioning against custom hyperscale server designs. Dell's direct enterprise sales model, integrated supply chain, and lifecycle management services provide structural advantages in capturing large-volume corporate procurement contracts across North America, Europe, and Asia Pacific.
Global Servers Market Recent Developments
|
Year |
Company |
Development |
|---|---|---|
|
Jan 2025 |
Hewlett Packard Enterprise |
Launched ProLiant Gen12 server family with enhanced AI workload optimization and liquid cooling compatibility |
|
Mar 2025 |
Dell Technologies |
Introduced PowerEdge XE9680L server platform targeting large-scale AI training and inference deployments |
|
Feb 2025 |
Supermicro |
Released new liquid-cooled AI server systems featuring NVIDIA Blackwell GPU integration for hyperscale operators |
Global Servers Market Future Outlook
The Global Servers Market forecast projects the market reaching USD 254.60 billion by 2034, advancing at a 7.76% CAGR driven by sustained hyperscale cloud infrastructure expansion, enterprise AI adoption, and edge computing deployment programs globally. Hewlett Packard Enterprise, Dell Technologies, and Lenovo are expected to deepen competitive positioning through AI-optimized server portfolios, liquid cooling-compatible configurations, and as-a-service infrastructure consumption models aligned with evolving enterprise procurement preferences through 2034.
Technological advancement in server architecture - including CXL memory pooling, photonic interconnects, and neuromorphic processing integration - will progressively transition from research environments to commercial deployment across hyperscale and high-performance computing segments. Sustainability certification requirements, including the EU Energy Efficiency Directive and US EPA ENERGY STAR data center guidelines, will standardize energy performance benchmarks across server product families, compelling manufacturers including Supermicro, Cisco Systems, and IBM to accelerate power efficiency innovation through the forecast period.
Global Servers Market Report Coverage
The Global Servers Market Report provides comprehensive coverage of market size, competitive dynamics, segmentation, and regional demand patterns across the 2026–2034 forecast period.
|
Report Attribute |
Details |
|---|---|
|
Market Name |
Global Servers Market |
|
Market Size (2026) |
USD 140.02 Billion |
|
Market Size (2034) |
USD 254.60 Billion |
|
Forecast Period |
2026–2034 |
|
CAGR |
7.76% |
|
Base Year |
2026 |
|
Historical Years |
2021–2025 |
|
Forecast Years |
2026–2034 |
|
Segments Covered |
By Channel, By End-Use, By Product, By Enterprise Size |
|
Regions Covered |
North America, Europe, Asia Pacific, Latin America, Middle East and Africa |
|
Key Companies |
Hewlett Packard Enterprise, Dell Technologies, IBM, Cisco Systems, Lenovo, Oracle, Fujitsu, Supermicro, Huawei, Others |
|
Report Format |
PDF, Excel, PPT |
|
Customization |
Available as per client requirements |
Why Choose This Global Servers Market Report?
- Comprehensive coverage of the global server industry spanning five product types and four enterprise size segments.
- Accurate market sizing from USD 140.02 billion in 2026 through the 2034 forecast horizon.
- Detailed segmentation analysis covering rack, blade, tower, micro, and Open Compute Project server categories.
- Regional demand breakdown across North America, Europe, Asia Pacific, Latin America, and Middle East and Africa with share estimates.
- Competitive profiling of 9 leading global server manufacturers with segment-level positioning assessment.
- In-depth analysis of AI server demand, edge computing growth, and energy efficiency trends reshaping procurement decisions.
- Forecast data supporting strategic investment, product roadmap planning, and supplier partnership evaluation.
- Research aligned with enterprise digital transformation, hyperscale cloud expansion, and global data sovereignty regulatory frameworks.
Table of Contents
- Introduction
- Objective of the Study
- Product Definition
- Market Segmentation
- Study Variables
- Research Methodology
- Secondary Data Points
- Companies Interviewed
- Primary Data Points
- Breakdown of Primary Interviews
- Secondary Data Points
- Executive Summary
- Market Dynamics
- Drivers
- Challenges
- Opportunity Assessment
- Recent Trends and Developments
- Policy and Regulatory Landscape
- Global Servers Market Overview and Forecast Analysis (2021-2034)
- Market Size, By Value, By Growth Rate (CAGR/USD Billions)
- Demand – Supply Trends
- Market Share, By Channel
- Direct
- Reseller
- Systems Integrator
- Others
- Market Share, By End-Use
- BFSI
- Energy
- Government & Defense
- Healthcare
- IT & Telecom
- Others
- Market Share, By Product
- Blade
- Micro
- Open Compute Project
- Rack
- Tower
- Market Share, By Enterprise Size
- Micro
- Small
- Medium
- Large
- Market Share, By Region
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East and Africa
- Market Share, By Competitors
- Competition Characteristics
- Revenue Shares
- Direct Global Servers Market Overview, 2021-2034F
- By Value (USD Million)
- By End-Use – Market Size & Forecast 2021-2034, USD Million
- BFSI
- Energy
- Government & Defense
- Healthcare
- IT & Telecom
- Others
- Reseller Global Servers Market Overview, 2021-2034F
- By Value (USD Million)
- By End-Use – Market Size & Forecast 2021-2034, USD Million
- BFSI
- Energy
- Government & Defense
- Healthcare
- IT & Telecom
- Others
- Systems Integrator Global Servers Market Overview, 2021-2034F
- By Value (USD Million)
- By End-Use – Market Size & Forecast 2021-2034, USD Million
- BFSI
- Energy
- Government & Defense
- Healthcare
- IT & Telecom
- Others
- Others Global Servers Market Overview, 2021-2034F
- By Value (USD Million)
- By End-Use – Market Size & Forecast 2021-2034, USD Million
- BFSI
- Energy
- Government & Defense
- Healthcare
- IT & Telecom
- Others
- Competitive Outlook (Company Profile - Partial List)
- Hewlett Packard Enterprise
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Dell Technologies
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- IBM
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Cisco Systems
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Lenovo
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Oracle
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Fujitsu
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Supermicro
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Huawei
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Others
- Hewlett Packard Enterprise
- Contact Us & Disclaimer
Top Key Players & Market Share Outlook
- Hewlett Packard Enterprise
- Dell Technologies
- IBM
- Cisco Systems
- Lenovo
- Oracle
- Fujitsu
- Supermicro
- Huawei
- Others
Frequently Asked Questions