
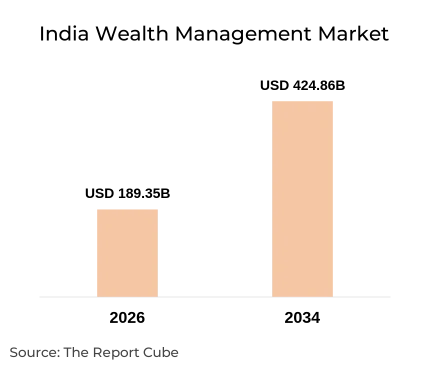
Build Your Custom Market Intelligence Report
Customize Your ReportKey Takeaways
- India wealth management market valued at USD 189.35 billion in 2026, reflecting robust affluent-client demand.
- Industry projected to reach USD 424.86 billion by 2034 at 10.63% CAGR.
- Banks lead the provider segment, supported by extensive branch networks and private banking franchises.
- High net worth individuals dominate end-user demand across India's wealth advisory landscape.
- Ultra high net worth individuals remain the fastest-growing end-user segment nationwide.
- 360 ONE WAM, Kotak, HDFC Bank, and ICICI Bank lead wealth advisory delivery in India.
- Alternatives access and digital advisory platforms are reshaping wealth manager client engagement.
Market Overview
The India Wealth Management Market Analysis values the market at USD 189.35 billion in 2026, rising to USD 424.86 billion by 2034 at a 10.63% CAGR. Rising financial assets, GIFT City initiatives, and advisory regulation support demand, while 360 ONE WAM, HDFC Bank, and ICICI Bank expand reach.
Affluent households, entrepreneurs, and non-resident Indians are shifting from deposits toward advisory-led portfolios covering equities, alternatives, and estate planning. India's emergence as a fast-growing wealth hub supports cross-border demand, while digital platforms and family office services deepen engagement. Kotak, Avendus, and Anand Rathi Wealth strengthen client acquisition through tailored offerings.
Market Size & Forecast
|
Metric |
Details |
|---|---|
|
Market Size (2026) |
USD 189.35 Billion |
|
Market Size (2034) |
USD 424.86 Billion |
|
CAGR (2026–2034) |
10.63% |
|
Base Year |
2026 |
|
Historical Years |
2021–2025 |
|
Forecast Years |
2026–2034 |
The India Wealth Management Market Size reached USD 189.35 billion in 2026 and is projected to hit USD 424.86 billion by 2034, expanding at a 10.63% CAGR. Growth is differentiated by the rapid rise of ultra-wealthy clients, alternative investment adoption, and bank-led private banking expansion into tier-2 and tier-3 Indian cities.
Market Dynamics
India Wealth Management Market Growth rests on rising financial wealth, formalization of savings, and expanding demand for advisory-led investing. Regulatory clarity, digital onboarding, and product breadth across mutual funds, alternatives, and structured solutions are strengthening provider capabilities, while banks, NBFCs, and independent platforms compete for affluent and ultra-wealthy mandates nationwide.
|
Factor |
Type |
Specific Impact on Market |
Magnitude |
|---|---|---|---|
|
Rising HNI and UHNI wealth creation |
Driver |
Expands investable surplus and demand for portfolio, estate planning, and alternatives mandates |
High |
|
Digital advisory and onboarding adoption |
Driver |
Lowers servicing costs and widens access to affluent clients beyond metropolitan centers |
Medium |
|
Tier-2 and tier-3 city wealth creation |
Opportunity |
Opens new client pools for banks and NBFCs expanding private banking reach |
High |
|
Market volatility and compliance costs |
Challenge |
Pressures advisory margins and raises suitability and disclosure obligations |
Medium |
|
Alternatives and global investing demand |
Trend |
Drives diversification into AIFs, private markets, and offshore allocations |
High |
- Growth Drivers: Rising HNI and UHNI Wealth: Business ownership, equity market participation, and asset monetization are expanding investable surpluses. Affluent households increasingly seek structured planning, alternatives access, and succession advisory from banks, NBFCs, and specialist firms such as 360 ONE WAM and Anand Rathi Wealth.
- Market Restraints: Volatility and Compliance Costs: Equity market swings can delay client allocation decisions and pressure fee revenues. Stricter suitability, disclosure, and distribution norms raise compliance expenses for smaller advisors, while fee transparency expectations narrow margins for product-led wealth distributors.
- Market Opportunities: HDFC Securities expects household financial assets to roughly triple over the next decade, with tier-2 and tier-3 cities contributing a growing share. Providers can build digital-first advisory, NRI corridors, and family office solutions targeting entrepreneurs and corporate treasuries.
- Industry Challenges: Talent scarcity among senior relationship managers, client attrition to competing platforms, and fragmented advisory quality complicate scaling. Providers must also balance personalized service with technology investments while meeting evolving investment adviser, portfolio management, and alternative fund regulations.
Need Specific Data, Let’s Customize the Report for You
Request CustomizationMarket Trends
- Emerging Trends: Among the most visible India Wealth Management Market Trends, family offices, succession planning, and alternatives-led portfolios are gaining traction. Wealth firms increasingly target entrepreneurs, promoters, and non-resident Indians through integrated onshore and offshore solutions.
- Technology Trends: Digital onboarding, AI-assisted portfolio analytics, and consolidated client dashboards are becoming standard across leading providers. Automation is expected to lower service costs and extend personalized advisory to mid-affluent segments through 2034.
- Consumer / Buyer Trends: Clients increasingly demand goal-based planning, transparent fees, and access to private markets, structured products, and global equities. Younger first-generation wealth creators favor digital engagement, while established families prioritize succession and intergenerational wealth transfer planning.
- Regulatory Trends: SEBI investment adviser and portfolio manager regulations continue tightening disclosure, suitability, and fee standards. A November 2025 Finance Ministry notification extended the Capital Gains Account scheme to 19 private sector banks, while GIFT City supports offshore wealth structuring.
India Wealth Management Market Segment Analysis
The India Wealth Management Market serves distinct client categories and provider types, each shaped by asset size, service depth, and product access. Understanding India Wealth Management Market Share across these categories shows where advisory demand and provider competition concentrate.
By End-User
- High Net Worth Individuals
- Ultra High Net Worth Individuals
- Corporates
- Others
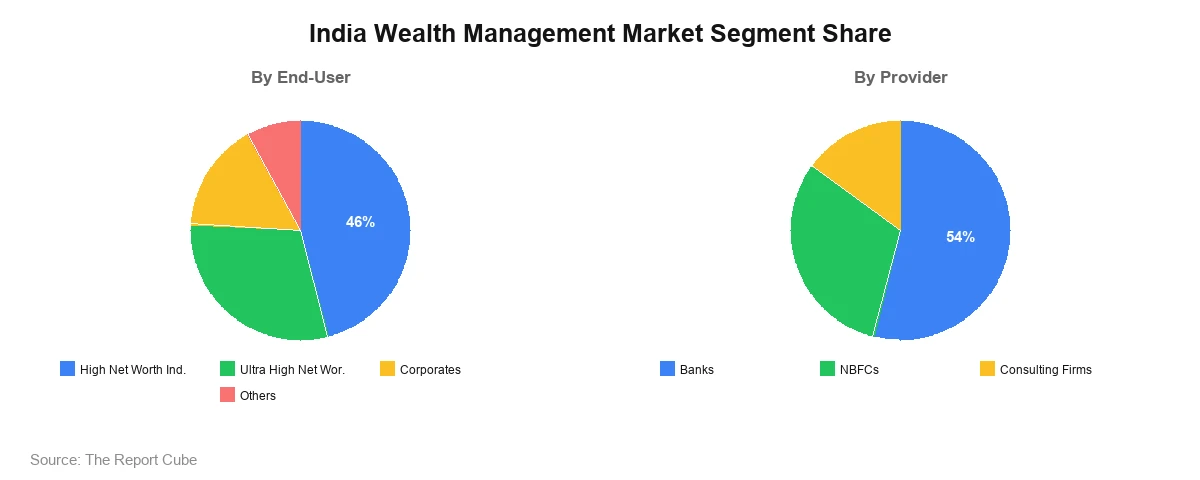
High net worth individuals lead the end-user segment with an estimated 46% share in 2026, served by Anand Rathi Wealth, Bajaj Capital, and ICICI Bank. Ultra high net worth individuals, at 30%, grow fastest through 360 ONE WAM, Kotak, and Avendus. Corporates hold 16%, while others account for roughly 8%.
By Provider
- Banks
- NBFCs
- Consulting Firms
Banks lead the provider segment with an estimated 54% share in 2026, led by HDFC Bank, ICICI Bank, and Kotak. NBFCs hold 31%, led by Aditya Birla Finance, Motilal Oswal, and 360 ONE WAM. Consulting firms represent 15%, where Avendus Capital and Morgan Stanley Financial Advisors deliver specialist advisory mandates.
Regional Analysis
|
Region |
Estimated Market Share |
Key Growth Factors |
Consumer Trends |
|---|---|---|---|
|
West India |
38% |
Mumbai financial hub, headquarters of leading wealth firms, dense promoter and UHNI base |
Alternatives, structured products, family office demand |
|
North India |
27% |
Delhi NCR business families, real estate and manufacturing wealth, NRI inflows |
Mutual fund-led planning, succession and estate advisory |
|
South India |
25% |
Bengaluru, Hyderabad, and Chennai technology, pharmaceutical, and startup wealth creation |
Digital-first advisory, private markets, ESOP-linked planning |
|
East India |
10% |
Kolkata trading and industrial families, improving advisory penetration |
Conservative allocation, debt and hybrid products, rising advisory adoption |
- West India - Accounting for approximately 38% of total demand, this region hosts Mumbai's concentration of private banks and independent wealth platforms, anchoring the India Wealth Management Market with deep promoter, corporate, and UHNI client pools.
- North India - Representing about 27% of demand, Delhi NCR and Punjab business families, real estate proceeds, and returning NRI capital sustain demand for succession planning, mutual fund-led portfolios, and estate advisory services.
- South India - Holding roughly 25% of demand, technology founders, pharmaceutical entrepreneurs, and startup employees across Bengaluru, Hyderabad, and Chennai are driving digital-first advisory and private market allocations.
- East India - Contributing approximately 10% of demand, Kolkata's established trading families and improving advisory penetration support steady, conservative wealth demand, with providers gradually expanding relationship teams.
Market Share & Competitive Landscape
The India Wealth Management Market is moderately concentrated, with private banks, independent wealth platforms, and financial groups competing for affluent mandates. Providers differentiate through product breadth, alternatives access, digital capabilities, and relationship depth.
|
Company |
Competitive Strength |
Primary Segment Served |
|---|---|---|
|
360 One Wam Limited |
Independent wealth and alternatives platform with AUM above ₹7.11 lakh crore |
UHNIs, family offices |
|
Kotak Investment Advisors Limited |
Kotak group alternate investment funds and private banking ecosystem |
UHNIs, HNIs |
|
Aditya Birla Finance Limited |
Aditya Birla Capital group synergies, lending-linked wealth solutions |
HNIs, corporates |
|
Avendus Capital Pvt. Ltd. |
Deep alternatives access for promoters and family offices |
Promoters, entrepreneurs, family offices |
|
Anand Rathi Wealth Limited |
Mutual fund-led private wealth model, listed platform |
HNIs, UHNIs |
|
Bajaj Capital Limited |
Long-established financial planning and distribution network |
HNIs, affluent households |
|
HDFC Bank Ltd. |
Nationwide reach, private banking, HDFC Tru advisory offering |
HNIs, UHNIs, corporates |
|
Morgan Stanley Financial Advisors |
Global research and cross-border investment access |
UHNIs, corporates |
|
Motilal Oswal Financial Services Ltd. |
Private wealth AUM above ₹1.95 lakh crore by December 2025 |
HNIs, UHNIs |
|
ICICI Bank Limited |
Private banking franchise, thriving family office business, digital innovation |
HNIs, UHNIs, corporates |
Key Companies in the India Wealth Management Market
360 One Wam Limited
360 ONE WAM, headquartered in Mumbai and formerly IIFL Wealth, rebranded in November 2022 and reported assets above ₹7.11 lakh crore by December 2025. In April 2025, it agreed to acquire UBS's onshore India wealth business. Its independent platform and alternatives depth strengthen positioning among ultra-wealthy families.
HDFC Bank Ltd.
HDFC Bank, headquartered in Mumbai, is among India's largest private sector lenders with nationwide reach. In October 2024, its broking arm HDFC Securities launched HDFC Tru, a wealth advisory offering for family offices, ultra-wealthy investors, and corporate treasuries. Extensive distribution and cross-selling capabilities remain its competitive strength.
Recent Developments
|
Year |
Company |
Development |
|---|---|---|
|
Mar 2025 |
Kotak Private Banking |
Reported private banking AUM growth above 30% and outlined expansion into tier-2 and tier-3 cities |
|
Apr 2025 |
360 One Wam Limited |
Agreed to acquire UBS's India wealth business for Rs 307 crore, carrying about Rs 26,000 crore of active AUM |
|
Nov 2025 |
HDFC Bank, ICICI Bank, Kotak Mahindra Bank |
Included among 19 private sector banks permitted to offer Capital Gains Account scheme deposits |
|
Dec 2025 |
360 One Wam Limited |
Reported AUM above ₹7.11 lakh crore |
|
Mar 2026 |
Anand Rathi Wealth Limited |
Received SEBI recognition of its private placement memorandum for the ARWL NIFTY Accelerator Series I AIF scheme |
Future Outlook
The India Wealth Management Market Forecast points to USD 424.86 billion by 2034, expanding at a 10.63% CAGR. Ultra-wealthy and high net worth clients will anchor demand, while 360 ONE WAM, Kotak, HDFC Bank, and ICICI Bank deepen family office, alternatives, and cross-border advisory offerings across the entire forecast period.
Artificial intelligence, integrated digital platforms, and open financial data will lower advisory servicing costs and widen reach beyond metropolitan centers. Stricter SEBI oversight, standardized fee disclosure, and growing emphasis on suitability will favor well-governed, transparent providers, while GIFT City structures expand offshore investment access for affluent Indian families through 2034.
India Wealth Management Market Report Coverage
This India Wealth Management Market Report covers historical performance, forecast projections, segmentation, regional demand, and competitive profiling for 2026–2034.
|
Report Attribute |
Details |
|---|---|
|
Market Name |
India Wealth Management Market |
|
Market Size (2026) |
USD 189.35 Billion |
|
Market Size (2034) |
USD 424.86 Billion |
|
Forecast Period |
2026–2034 |
|
CAGR |
10.63% |
|
Base Year |
2026 |
|
Historical Years |
2021–2025 |
|
Forecast Years |
2026–2034 |
|
Segments Covered |
By Type, By End-User, By Provider |
|
Regions Covered |
South India, North India, West India, East India |
|
Key Companies |
360 One Wam Limited, Kotak Investment Advisors Limited, Aditya Birla Finance Limited, Avendus Capital Pvt. Ltd., Anand Rathi Wealth Limited, Bajaj Capital Limited, HDFC Bank Ltd., Morgan Stanley Financial Advisors, Motilal Oswal Financial Services Ltd., ICICI Bank Limited, Others |
|
Report Format |
PDF, Excel, PPT |
|
Customization |
Available as per client requirements |
Why Choose This India Wealth Management Market Report?
- Comprehensive coverage of India's wealth management market across client and provider categories.
- Accurate market sizing from USD 189.35 billion in 2026 through the 2034 forecast.
- Detailed segmentation by end-user (HNIs, UHNIs, Corporates) and provider (Banks, NBFCs, Consulting Firms).
- Regional insights covering South, North, West, and East India with share estimates.
- Competitive profiling of 10 leading banks, NBFCs, and specialist wealth advisory firms.
- Analysis of alternatives, digital advisory, and family office trends reshaping client demand.
- Forecast data supporting strategic investment, partnership, and product planning decisions.
- Research aligned with India's Viksit Bharat 2047 economic ambitions.
Table of Contents
- Introduction
- Objective of the Study
- Product Definition
- Market Segmentation
- Study Variables
- Research Methodology
- Secondary Data Points
- Companies Interviewed
- Primary Data Points
- Breakdown of Primary Interviews
- Secondary Data Points
- Executive Summary
- Market Dynamics
- Drivers
- Challenges
- Opportunity Assessment
- Recent Trends and Developments
- Policy and Regulatory Landscape
- India Wealth Management Market Overview and Forecast Analysis (2021-2034)
- Market Size, By Value, By Growth Rate (CAGR/USD Billions)
- Demand – Supply Trends
- Market Share, By Type
- Financial Advice Management
- Portfolio Management
- Performance Management
- Risk & Compliance Management
- Others
- Market Share, By End-User
- High Net Worth Individuals
- Ultra High Net Worth Individuals
- Corporates
- Others
- Market Share, By Provider
- Banks
- NBFCs
- Consulting Firms
- Market Share, By Region
- South India
- North India
- West India
- East India
- Market Share, By Competitors
- Competition Characteristics
- Revenue Shares
- Financial Advice Management India Wealth Management Market Overview, 2021-2034F
- By Value (USD Million)
- By End-User – Market Size & Forecast 2021-2034, USD Million
- High Net Worth Individuals
- Ultra High Net Worth Individuals
- Corporates
- Others
- Portfolio Management India Wealth Management Market Overview, 2021-2034F
- By Value (USD Million)
- By End-User – Market Size & Forecast 2021-2034, USD Million
- High Net Worth Individuals
- Ultra High Net Worth Individuals
- Corporates
- Others
- Performance Management India Wealth Management Market Overview, 2021-2034F
- By Value (USD Million)
- By End-User – Market Size & Forecast 2021-2034, USD Million
- High Net Worth Individuals
- Ultra High Net Worth Individuals
- Corporates
- Others
- Risk & Compliance Management India Wealth Management Market Overview, 2021-2034F
- By Value (USD Million)
- By End-User – Market Size & Forecast 2021-2034, USD Million
- High Net Worth Individuals
- Ultra High Net Worth Individuals
- Corporates
- Others
- Others India Wealth Management Market Overview, 2021-2034F
- By Value (USD Million)
- By End-User – Market Size & Forecast 2021-2034, USD Million
- High Net Worth Individuals
- Ultra High Net Worth Individuals
- Corporates
- Others
- Competitive Outlook (Company Profile – Partial List)
- 360 One Wam Limited
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Kotak Investment Advisors Limited
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Aditya Birla Finance Limited
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Avendus Capital Pvt. Ltd.
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Anand Rathi Wealth Limited.
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Bajaj Capital Limited
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- HDFC Bank Ltd.
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Morgan Stanley Financial Advisors
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- Motilal Oswal Financial Services Ltd.
- Company Overview
- Business Segments
- Strategic Alliances/Partnerships
- Recent Developments
- ICICI Bank Limited
- 360 One Wam Limited
- Contact Us & Disclaimer
Top Key Players & Market Share Outlook
- 360 One Wam Limited
- Kotak Investment Advisors Limited
- Aditya Birla Finance Limited
- Avendus Capital Pvt. Ltd.
- Anand Rathi Wealth Limited.
- Bajaj Capital Limited
- HDFC Bank Ltd.
- Morgan Stanley Financial Advisors
- Motilal Oswal Financial Services Ltd.
- ICICI Bank Limited
Frequently Asked Questions